What you need to know about home loans in 2024
Understanding your options to borrow or refinance could save you time on your loan — and thousands of dollars
 4 min
Deciding on a home loan is never an easy undertaking. When adding it to the growing checklist of things to do to either jump on or move up the property ladder—amid rising interest rates and soaring property prices, nonetheless—doing your home loan due diligence is imperative in order to gain the greatest benefits your individual circumstances.
In 2024, the average home loan in Australia was $615,174, showing a 2.3% increase when compared to January 2023, according to the Australian Bureau of Statistics (ABS) data. For first-time home buyers, the average loan amount rose from $485k to $514k, revealing borrowers are taking on bigger debts than ever before to secure their dream of home ownership.


For those seeking to refinance their mortgage, activity remains high as borrowers look to switch lenders to better manage persistently high interest rates. In June 2023, the value of total refinancing between lenders was 12.6 per cent higher compared to June 2022, according to ABS data.
While Australian borrowers started the year with a 4.35 % rate, Dean Sacco, director and finance specialist at Urban Finance Co, says that the Reserve Bank of Australia has changed its language in recent months, with the expectation that the cash rate has peaked, giving buyers more confidence with their home loan repayments.
“Low stock levels are proving difficult for buyers but those who are motivated, with good incomes and good credit, will be successful in 2024,” says Sacco.
Here’s what you need to know.
What is a home loan?
When purchasing a home, a bank or a loan provider will lend money to the borrower in order to finance the purchase of a property. This is what home loan is, at its core. Of course, home loans come with certain caveats, such as a timeframe that the lender and borrower will agree on for the loan to be paid back. A payment schedule will also be decided on, which could be fortnightly or monthly, which can impact the amount of money repaid over time. And in addition, a borrower will be required to pay interest, which will be determined by the lender.
And what is refinancing? How does it work?
In its simplest form, refinancing is when you switch from your current loan to a new one, either with the same provider or a new one in order to obtain better terms on your mortgage. There are two types of refinances, which include external refinance, when you leave your current lender and switch to a new lender, and internal refinance, when you stay with your current lender, but make changes to your loan agreement.
In 2024, which bank is best for refinancing options?
While each case will be different and specific to the individuals at hand, according to Sacco, there are several banks in Australia currently offering great cashbacks for refinancing, such as ANZ and ME Bank.
“Gateway Bank, Heritage Bank and Adelaide Bank are also offering some competitive variable rates at the moment for owner occupiers,” he adds. “And Teachers Mutual, Beyond Bank and ubank are offering some competitive variable rates at the moment for investors.”
Is it better to refinance with the same lender?
If you’re looking to refinance, often, you can avoid certain refinancing costs if doing so with the same lender, but it’s always smart to shop around and compare offers available. When looking to refinance, certain lenders will also offer competitive products and rates which could prove beneficial.
Is it good to refinance a loan?
At the end of the day, you want your loan (your mortgage) on terms that work best for you. Refinancing a loan allows you to obtain better terms on your mortgage, and in the process, can not only save you money but can help you pay off your home loan sooner. “You can also access equity to pay out higher interest debts, purchase a car or invest in property,” adds Sacco.
There are some drawbacks, however. Most notably, the potential for refinancing fees which, in some cases, are unavoidable.
Does refinancing hurt your credit?
There’s a misconception that refinancing automatically affects your credit score – it’s not always the case.
“Multiple credit enquiries in a short period of time or applying for buy now, pay later debts are two examples that lower your credit score,” explains Sacco. “This signals to new lenders that you are potentially a higher risk borrower.”
—
If you are looking to for the very best home loans to consider right now — or perhaps looking to refinance to suit your current needs — here are ten home loans to consider in 2024.
1. ANZ
- Variable home loan
- Variable rates from 6.64% p.a.
- No ongoing fees
- $0 ANZ set up
2. ubank
- Variable home loan
- Variable rates from 6.14% p.a.
- Free extra repayments
- $0 application
- $0 ongoing fees
- Redraw available
3. Macquarie Bank
- Fixed home loan
- 3 year fixed rates of 5.99% p.a
- $0 application fee
- $0 ongoing fee
4. IMB Bank
- Fixed home loan
- 2 year fixed rates of 5.99% p.a
- $449 application fee
- $0 ongoing fee
- Eligible refinancers can get $2,000 cashback when switching their loan of at least $500k to IMB
5. ING Bank
- Variable home loan
- Variable rates from 6.14% p.a.
- $0 application
- $0 ongoing fees
6. Bendigo Bank
- Variable home loan
- Variable rates from 6.01% p.a.
- $0 application
- $10 per month ongoing fees
- Redraw available
7. Newcastle Permanent
- Variable home loan
- Variable rates from 6.04% p.a.
- $595 application fee
- $0 ongoing fees
- Eligible refinancers who apply online and borrow $250K+ (LVR 80% or lower) can get a $3,000 cashback
8. BCU Bank
- Fixed home loan
- 2 year fixed rate of 5.99% p.a.
- No establishment or annual ongoing fee
- 5% deposit required
9. HSBC
- Variable home loan
- Variable rates from 6.09% p.a.
- Enjoy free extra repayments, online redraw and no ongoing monthly service fees
10. UP
- Fixed home loan
- 4 year fixed rate of 5.80% p.a
- 10% deposit required
- No application, monthly or annual fees
- Talk to a broker or financial advisor for advice specific to your needs

From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Mirvac’s 45-level Trielle has topped out at Yarra’s Edge, pairing riverfront apartments with wellness facilities, private dining and resident services.
3 min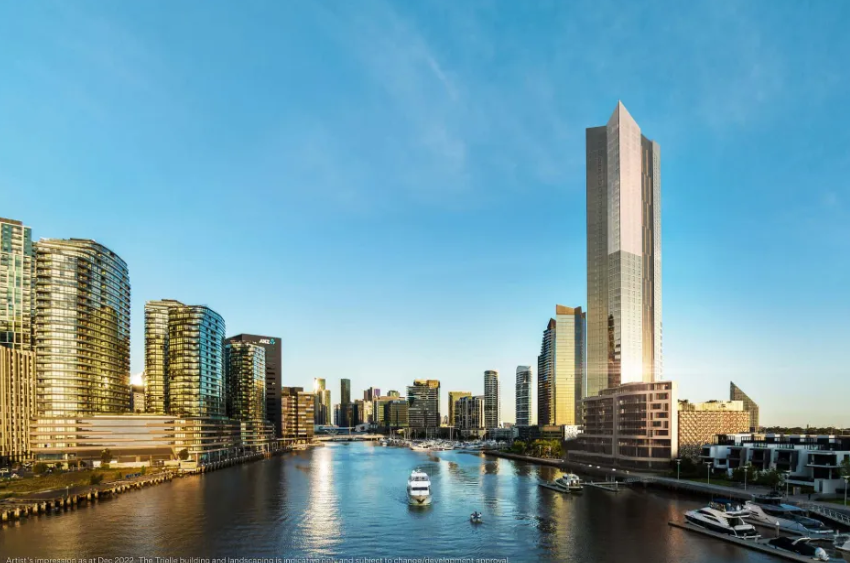
Mirvac has topped out Trielle at Melbourne’s Yarra’s Edge, with more than 70 per cent of the riverfront development sold and approximately 80 per cent of purchasers intending to make their apartment a home.
The figures, released on September 22, point to an owner-occupier audience for one of the precinct’s final residential towers. Mirvac began developing Yarra’s Edge in 2003, and its latest addition occupies one of the remaining absolute riverfront sites.
Mirvac CEO of Development Stuart Penklis said existing residents were among those moving up within the neighbourhood.
“Many purchasers already have a connection to Yarra’s Edge,” Mr Penklis said, describing buyers whose changing needs were encouraging an upgrade within the precinct.
“As one of the final residential towers within Yarra’s Edge, Trielle represents the culmination of more than two decades of creating one of Melbourne’s most established and sought-after waterfront communities,” Penklis said.
“Positioned on the Collins Street axis with absolute river frontage, Trielle offers residents a rare opportunity to enjoy sweeping views across the Yarra River, Melbourne skyline and Port Phillip Bay, while remaining seamlessly connected to the CBD. With Trielle now more than 70 per cent sold, we’re continuing to see strong demand from buyers seeking quality homes in established locations.”
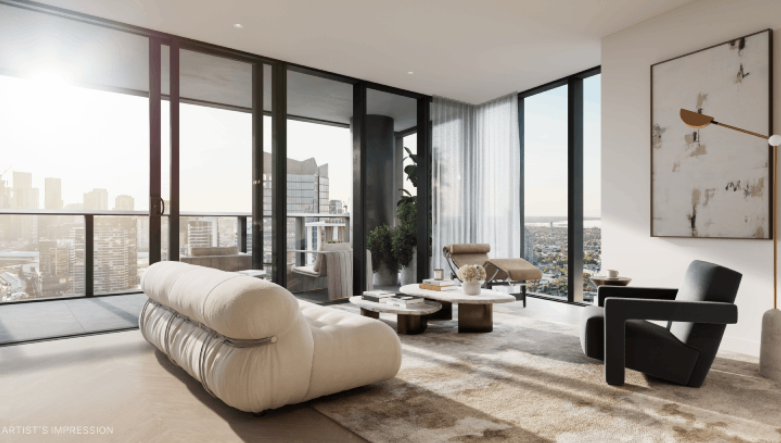
The developer also flagged a penthouse and sub-penthouse collection with larger layouts, premium finishes and broad outlooks. The planned wellness centrepiece, The Oasis, encompasses a 900-square-metre elevated urban rainforest.
Mirvac General Manager Residential Development Victoria Elysa Anderson said Trielle had resonated strongly with buyers seeking a rare lifestyle offering in Melbourne.
“Opportunities to secure a new luxury residence on a riverfront site of this calibre are incredibly rare, particularly within a community like Yarra’s Edge,” Anderson said.
“What makes Trielle unique is the combination of exceptional views, world-class residential facilities and the lifestyle that already exists around it. Residents are buying into a mature waterfront community with parks, promenades, dining, wellness and strong community connections already in place.”
The 45-level tower brings a substantial new presence to that waterfront. Its residential offering spans one-, two-, three- and four-bedroom apartments, with Signature, Prestige and Sub-Penthouse collections accommodating different household sizes. The north-facing position connects the apartments visually to the river and city beyond.
Seven storeys above the promenade, the planned Oasis combines planting and a running stream with a Scandinavian-inspired wellness club developed with spa specialist Naomi Gregory. Facilities include a 25-metre lap pool, hot magnesium pool, sauna, hydrotherapy, a gym, yoga and Pilates room, and treatment spaces.
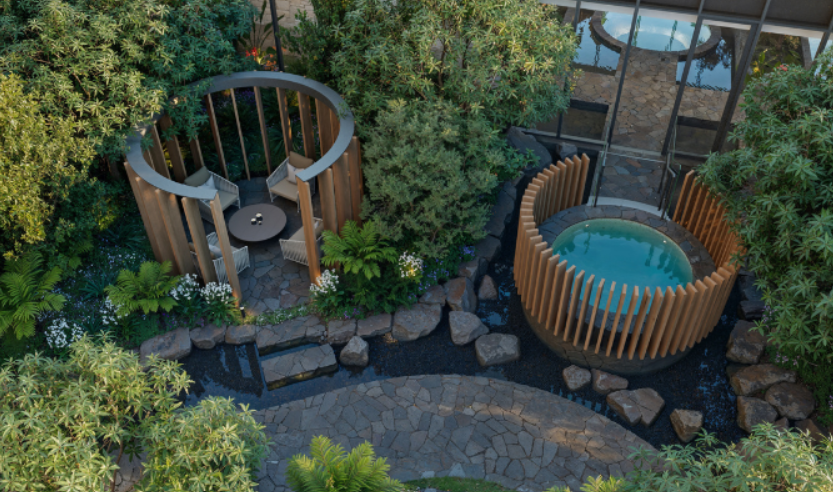
The amenity extends beyond exercise. Residents will have access to The Biblioteca library and workspaces, ground-floor work pods, and The Salone piano lounge. A private Chef’s Table dining room offers a setting for larger gatherings, while a cinema, games room and sports lounge broaden the entertaining options. Concierge services and a dog-wash area support everyday routines.
Trielle comprises a collection of one, two, three and four-bedroom residences. Reflecting strong demand from owner occupiers, approximately 80 per cent of purchasers to date intend to live in their homes, highlighting the project’s appeal to those seeking a long-term waterfront lifestyle.
Mirvac has recently delivered The Albertine, a premium apartment development on the edge of Melbourne’s CBD, and is nearing completion of Prince & Parade in Brunswick, further strengthening its portfolio of thoughtfully designed apartment communities in some of Melbourne’s most sought-after urban locations.

From gorilla encounters in Uganda to a reimagined Okavango retreat, Abercrombie & Kent elevates its African journeys with two spectacular lodge transformations.
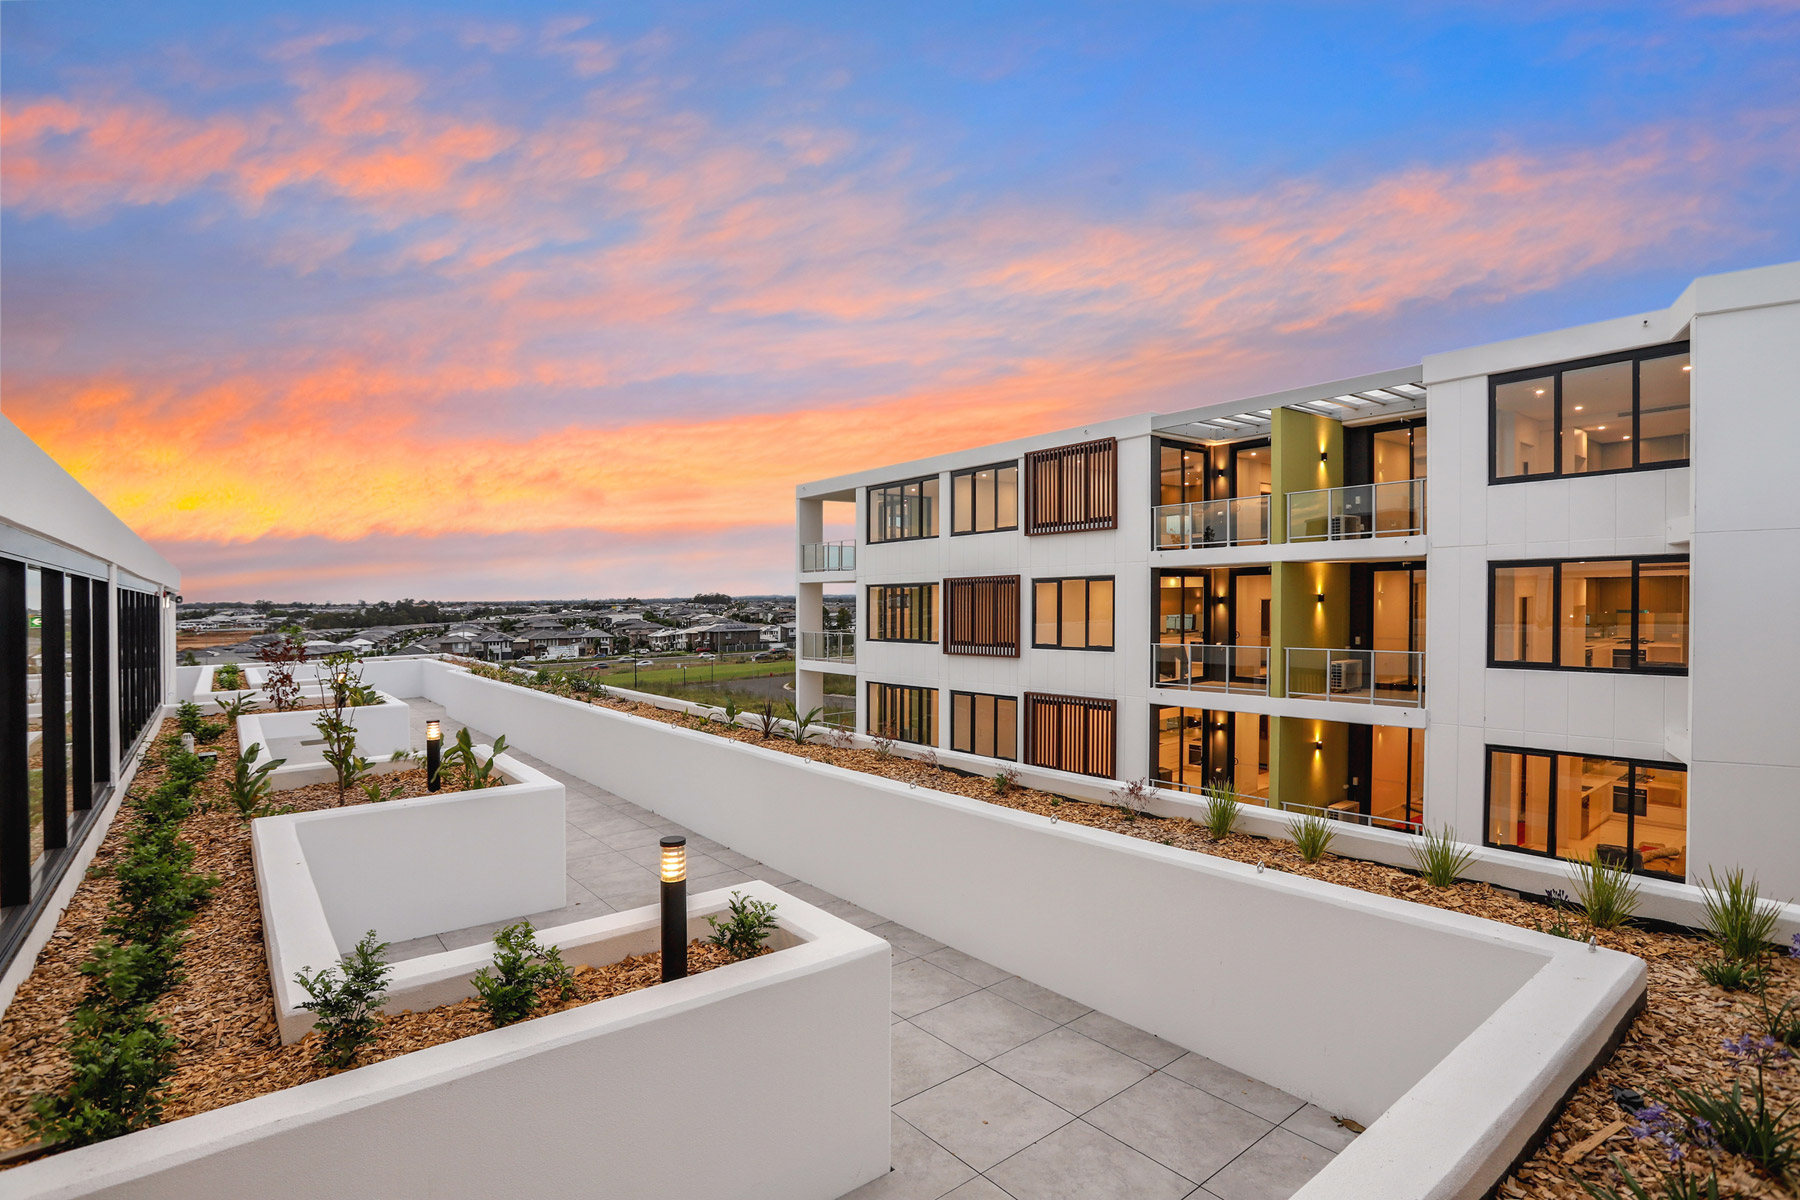
Ophora Tallawong has launched its final release of quality apartments priced under $700,000.