Australia’s top 10 most affordable regional property markets investors should watch
Whether you prefer the country or the coast, there are plenty of east coast options for cashed up buyers
 3 min
There are 10 local council areas scattered along the East Coast of Australia that offer both affordability and solid fundamentals for sustainable future growth, according to the research team at residential property network, PRD. The areas have been selected based on five criterion. They are affordability – defined as a median house price below $600,000, rising house values, strong rental yields to encourage investment, a strong pipeline of residential, commercial and infrastructure projects to facilitate local economic development, and low unemployment.
Here are Australia’s 10 most affordable regional property markets with great future potential.
Mackay, QLD
Mackay is a tropical coastal area located in north Queensland. It’s known for its closeconnection to the Great Barrier Reef. The median house price is $462,750, up 8.9 percent in 2023. Mackay attracts a lot of interstate migrants and is home to more than 120,000 people. It has a healthy economy with an unemployment rate of 3.7 percent and $1.7 billion worth of projects due to commence this year.
Toowoomba, QLD
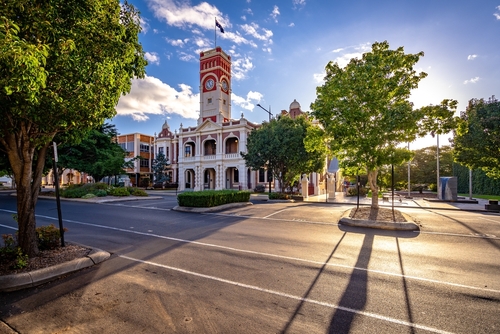
Toowoomba is located west of Brisbane and is known for its Victorian buildings, street artand surrounding national parks. The median house price is $560,000, up 10.9 percent in 2023. The city has a population of more than 180,000. The unemployment rate is 4 percentand there is $6.1 billion in projects commencing in 2024.
Townsville, QLD
Townsville is a coastal city in north-eastern Queensland. The median house price is $420,000, up 5 percent in 2023. It is home to more than 200,000 people. Unemployment is very low at 2.5 percent and there is $3.2 billion of projects commencing this year.
Dubbo, NSW
Dubbo is located west of Newcastle in the Orana Region and is home to the Western Plains Zoo. The median house price is $530,000, up 11.6 percent in 2023. The population has exploded in recent years to more than 56,000 people. The unemployment rate is just 2.2percent and the economy is thriving. There is a pipeline of $4.7 billion in projects commencing this year.
Tamworth, NSW
Located in north-east NSW, Tamworth is known for its popular annual Country Music Festival. It’s also the largest retail centre for the New England and Northwest Slopes regions. The median house price is $490,000, up 14 percent in 2023. With a population of more than 65,000 people, the economy is strong with unemployment of just 2 percent and $112.4million worth of projects commencing this year.
Griffith, NSW
Located west of Sydney and northwest of Canberra, Griffith is known for its prime produce production and wine cultivation. The median house price is $531,000, up 2.1 percent in 2023. Griffith’s population is about 27,000 people. The city boasts high economic resilience with a 2 percent unemployment rate and $258.7 million in projects in the pipeline.
Ballarat, VIC
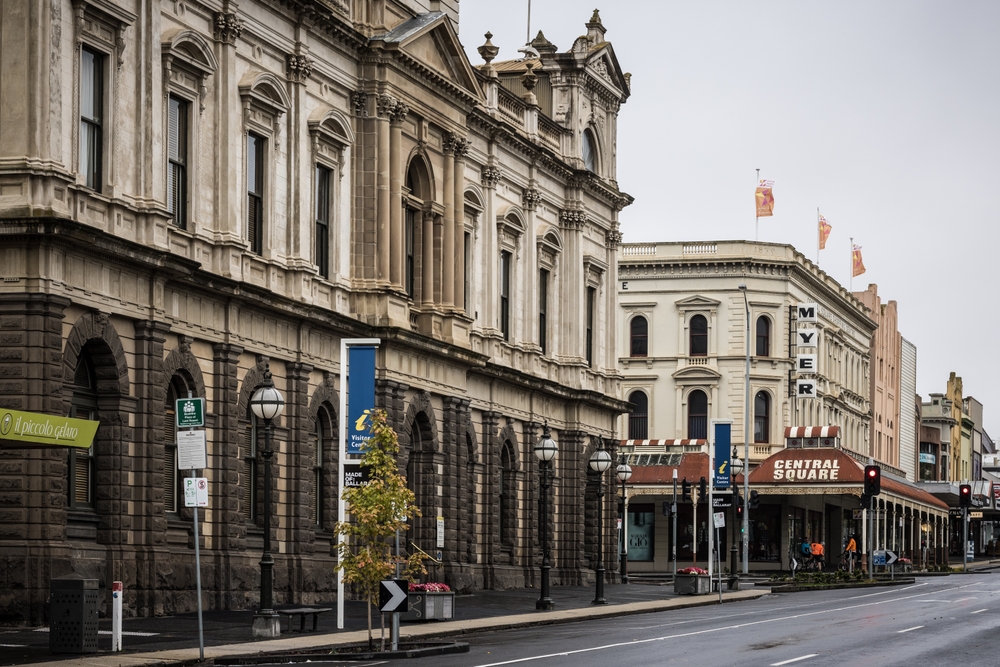
Ballarat is a 1.5–hour drive west of Melbourne. It’s popular with city commuters who move here for housing affordability and a relaxed lifestyle with easy access to the city via train. The median house price is $570,000, down 4.2 percent in 2023 but up 92.9 percent over the past decade. The city has the third highest population in Victoria at about 118,000. Ballarat has an unemployment rate of 3 percent and a total projects pipeline worth $2.3 billion for 2024.
Shepparton, VIC
Shepparton is a rural area about two hours north of Melbourne. It is popularly referred to as ‘the food bowl of Australia’. The median house price is $475,000, up 4.4 percent in 2023. The population is about 70,000. The unemployment rate is just 2 percent and there is $1.8 billion in projects for 2024.
Wodonga, VIC
Wodonga is located on the border of NSW on the southern side of the Murray River. It is approximately 320km from Melbourne and 345km from Canberra. The median house price is $567,250, up 4.7 percent in 2023. With a population of about 44,000, the city’s jobless rate is 3 percent and there is $388.2 million in development set to commence in 2024, primarily new infrastructure.
Burnie, TAS
Burnie is a bustling port city located in Emu Bay in Tasmania’s north-west. Overlooking beaches and parklands, the area is known for its rich agriculture and mining projects. The median house price is $435,000, up 3.6 percent. Despite a rising population, the unemployment rate is falling and is currently 5.6 percent. In 2024, Burnie’s project pipeline is valued at approximately $1.6 billion. A significant portion is commercial development, primarily renewable energy projects.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision.
The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty.
The first task is to calculate the impact of another 0.25 percentage-point increase. Indicative Canstar figures reported earlier this month suggest that such a move would add about $91 a month to repayments on a $600,000 loan, $122 on $800,000 and $152 on $1 million, although actual changes depend on rate, term and loan structure.
The second task is to compare the current loan with the market. Borrowers should examine the interest rate, annual package fee, offset balance, redraw rules and the revert rate on any expiring fixed portion. A lower advertised rate is not necessarily a better deal after fees, lost features or refinancing costs.
Third, test the household budget at least one percentage point above the current rate. This is not a forecast; it is a resilience exercise. Include council rates, strata, insurance, maintenance, school costs and realistic discretionary spending. Investors should also allow for vacancy and repairs rather than assuming uninterrupted rent.
Fourth, contact the existing lender before lodging multiple applications. A borrower with a sound repayment history may be able to negotiate a discount without refinancing. If the offer is weak, obtain comparable quotes and seek advice on whether changing lenders will genuinely improve the position.
Fifth, preserve liquidity. Using every available dollar to reduce principal may feel prudent, but an offset account can provide interest savings while retaining access to cash. The right structure depends on tax position and loan purpose, particularly where owner-occupied and investment debt coexist.
Borrowers considering a fixed rate face a trade-off. Fixing can provide repayment certainty, but may restrict additional repayments, offsets or early exit. Splitting a loan can diversify rate exposure without removing risk.
The worst time to examine a mortgage is after repayments have become unmanageable. A review conducted now gives borrowers more choices: renegotiate, refinance, adjust spending or build a buffer while their record remains strong.
Borrower checklist
Calculate: Repayments after a 0.25 and one percentage-point increase.
Compare: Rate, fees, offset, redraw, cashback conditions and total cost.
Review: Fixed-rate expiry, interest-only expiry and remaining loan term.
Protect: Emergency liquidity and insurance.
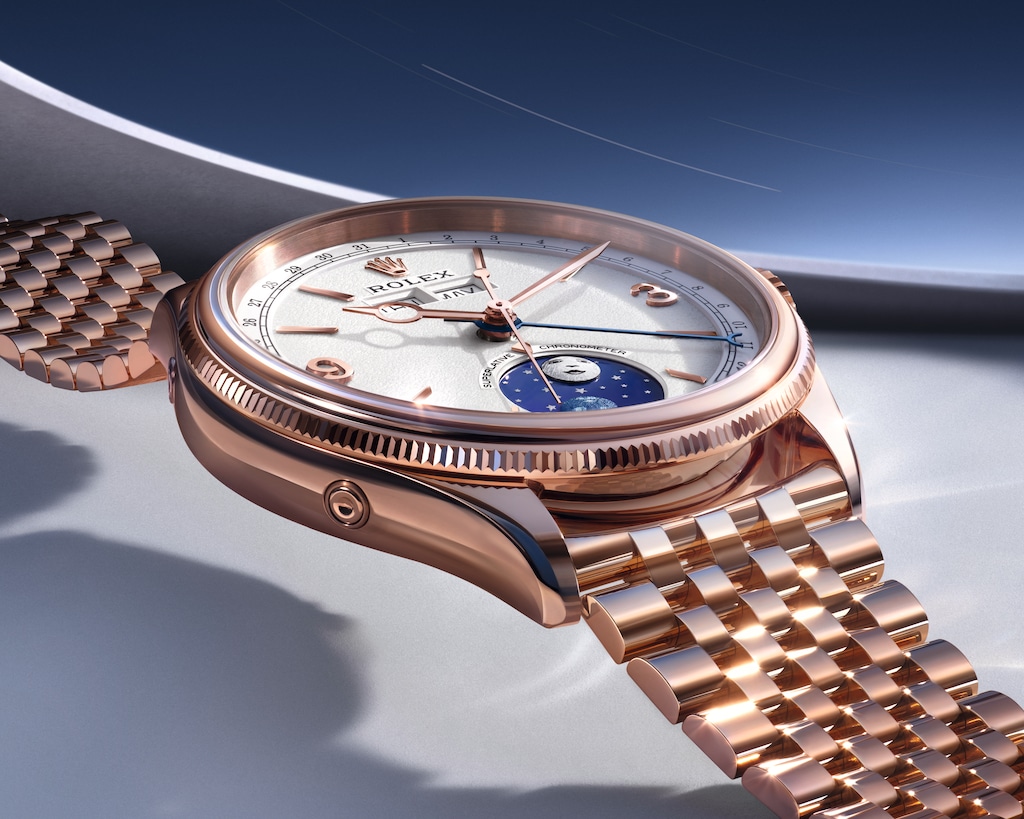
The Perpetual Padellone draws its name from the coveted reference 8171 while introducing an instantaneous complete annual calendar to Rolex’s modern Perpetual collection.
Powerhouse real estate couple Avi Khan and Kaylea Sayer welcome their daughter while balancing record-breaking careers, proving success and family can grow side by side.