The Money Habits I Learned From My Parents—for Better or Worse
We absorb our financial personalities from listening to, and watching, our parents. Sometimes they serve us well. Other times, not so much.

 4 min

My memory of when I first learned about stocks is fuzzy. I was in my early 20s, and my mother sat me down at our kitchen table, helped me open a brokerage account, and showed me how to buy and sell on the platform. The lesson I walked away with: Tread carefully, invest only “play money,” not money you need to survive, and only target companies that sell resources.
I also thought: This is too risky; I’ll never touch this account.
Years later, I still approach stocks with trepidation—no doubt coloured by that 30-minute conversation with my mom.
As I’ve talked to my family and friends, I realize that so much of what we know about personal finance—how we invest, how we spend—comes from our parents.
“We get our money personalities from our childhood,” says financial planner Angela Dorsey of Dorsey Wealth Management. “So if in our childhood there was a lot of hesitancy around it, then that shapes how you feel about money and taking calculated risks.”
Learning by watching
Sometimes, these lessons are learned through specific conversations, like the one I had with my mother. But more often than not, they come simply through observing. In fact, Dorsey says that many of her clients don’t have any money conversations with their parents. “It comes from seeing what happened to their parents, seeing what happened to their uncle,” she says. “A lot of times, they’re not even aware of it.”
But that lack of awareness comes with a price: When people don’t know where their money habits come from, they can often undermine good intentions. You may want to invest and spend wisely, but these unconscious, ingrained tendencies can create financial problems down the road. So it’s useful to uncover those unspoken lessons, and figure out which ones serve us well—and which ones don’t.
To expose those habits, Dorsey offers her clients a money-personality quiz, which can unveil attitudes about money developed from childhood. So I decided to take one. For good measure, I had my sister take it as well.
Both of us ended up falling into the “Bon vivant” pool—with traits like “Workaholics with long hours” and “Spends money on anything that saves them time.” Our issues? “Ad hoc investments,” “Panic with market ups and downs,” and “Confuse hobbies with investments.” (We both really felt that last one.)
Looking back, the traits that mark my financial personality are pretty much the same traits that my parents had. They worked long hours. They did give priority to spending on things that saved them time. They were happy to buy me new books or help me tackle a new hobby or skill. New clothes or makeup? Not so much.
Unlearning some lessons
Friends I spoke with mostly echoed what my sister and I experienced. While their parents might not have given them specific advice, they did influence their spending and budgeting tendencies just by being who they were.
“I didn’t get any money lessons from my parents, but I certainly picked up habits,” a former co-worker told me. “I saw my dad pack lunch every day for work, so I pack lunch every day for work now.” This friend was particularly thrifty in my years working with her, primarily using a debit card so as to not carry debt and eating her packed lunches as the rest of us spent $15 on salads and sandwiches.
She now has a credit card, but to this day she’d rather cobble together a lunch of office snacks than go out to buy lunch. “It has helped me in the long run because it keeps a baseline of healthy spending habits,” she says. She prefers meals out as a conscious choice for special occasions, rather than a standard practice.
Another friend watched how his parents, who were small-business owners, scrimped and saved at home. He summed up what he learned from that in three bullet points:
He says he is now trying to loosen up and feel comfortable spending some of his hard-earned money to improve his quality of life, especially as he has become more successful in his career.
This is a common lesson Dorsey says she teaches her clients to unlearn. “It’s really interesting how frequently I run into situations where they have enough, but when it comes time to spending, they’re terrified,” she says. “And so I have to tell them, ‘You have my permission to spend your money.’ ”
On the brink of burnout
For my part, I’ve certainly benefited from watching my parents’ work ethic over the years. Doing so gave me the drive to establish my own career goals. Seeing their productivity inspired my own. But in the past few years, I’ve found myself on the brink of burnout—both at work and with all my extracurricular activities.
That has led me to the realization that my work and personal lives could actually benefit more from me enjoying my weekends, and not always packing them full of events or extra work. I now know that it’s just as important to step back from things and take a moment to recharge as it is to charge ahead. And my wallet would certainly appreciate buying less crochet yarn and concert tickets.
Mostly, though, I’ve had to work to get over my stock-market fears. My mother sitting down to explain how the market works was more than what some of my friends learned from their parents. But while it was a well-intentioned lesson, it didn’t have the desired effect at the time.
As a more fully-formed adult, I began to rethink that conversation. And thanks to my colleagues and my friends, I’ve started to put money into something beyond a basic savings account. I began contributing to a Roth IRA after a friend explained the tax benefits. A former boss clued me into high-yield savings accounts. A colleague encouraged me to invest—but in more-diversified ways, such as ETFs.
And I finally logged into that brokerage account my mother helped me open. While I still veer toward the more risk-averse side, following my mother’s cautious footsteps, learning more on my own has allowed me to think of investing as a way to make my savings grow, not just a way to experiment with “play money.”
In the end, sometimes the most well-intentioned parental lessons backfire. One friend invested in specific mutual funds that his father recommended. But those mutual funds didn’t do well and started dropping in value. So when my friend was later eligible to contribute to his employer-sponsored retirement account, he chose not to—feeling burned by those earlier losses. Instead, he used his extra money to be able to live without a roommate.
While my friend eventually ended up contributing to a retirement plan, he says the earlier experience taught him that sometimes you just need to “reject the things your parents tell you to do.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
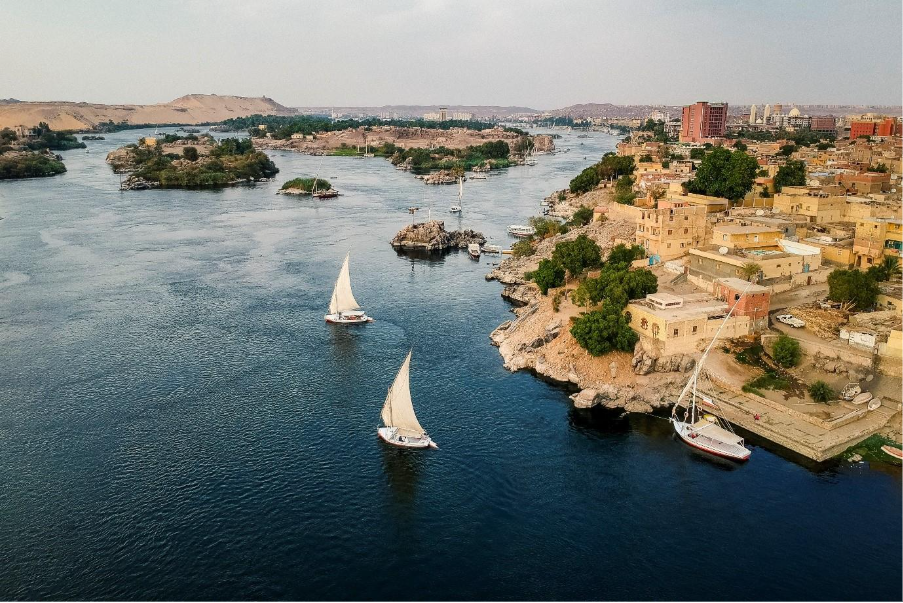
A resurgence in high-end travel to Egypt is being driven by museum openings, private river journeys and renewed long-term investment along the Nile.