Stock Futures Trade Slightly Higher as Investors Weigh Trump Shooting
 2 min

Stocks are poised for a slightly higher open on Monday, the first look at how U.S. markets will react following the failed assassination attempt on former President Donald Trump.
Trump was recovering Sunday, a day after a shooting at a campaign rally in Pennsylvania that injured Trump and left one attendee dead and two others critically injured.
Investors aren’t showing heightened concern, as far as moves in stock futures are reflecting on Sunday. At 6:46 p.m. ET, Dow Jones Industrial Average futures gained 60 points, or 0.2%, the S&P 500 futures rose 0.1%; and Nasdaq Composite futures were up 0.1%.
Republicans are converging in Milwaukee this week to formally nominate Trump as their party’s presidential candidate. The Republican National Convention is moving forward as an investigation into the shooting continues.
Futures also were extending a rally that has lifted stocks to fresh highs this year, fueled by earnings and a surge in tech shares.
Forty-five S&P 500 companies report earnings this week, including BlackRock and Goldman Sachs on Monday.
Bank of America , Charles Schwab , J.B. Hunt Transport Services , Morgan Stanley , Omnicom Group , PNC Financial Services Group , State Street, and UnitedHealth Group report earnings on Tuesday.
ASML Holding , Citizens Financial Group , Crown Castle , Discover Financial Services , Elevance Health , Equifax , Johnson & Johnson , Kinder Morgan , Northern Trust , Prologis , Steel Dynamics , Synchrony Financial , United Airlines Holdings , and U.S. Bancorp all report earnings on Wednesday.
Abbott Laboratories , Alaska Air Group , Blackstone, Cintas, D.R. Horton, Domino’s Pizza , Intuitive Surgical , KeyCorp , M&T Bank , Marsh & McLennan , Netflix , Novartis , Taiwan Semiconductor Manufacturing , and Textron report earnings on Thursday.
American Express , Fifth Third Bancorp , Halliburton , Huntington Bancshares , Regions Financial , SLB, and Travelers report on Friday.
This week’s notable economic events include Monday’s release of the Empire State Manufacturing Survey by the New York Fed. Later today, Federal Reserve Chair Jerome Powell will speak at the Economic Club of Washington, D.C.; and San Francisco Fed President Mary Daly will speak at Fortune Brainstorm Tech 2024.
On Tuesday, the Census Bureau reports June retail sales data, and the National Association of Home Builders will release its Housing Market Index for July. Also Tuesday, Fed Gov. Adriana Kuglar will speak at the National Association for Business Economics’ Economic Measurement Seminar in Washington, D.C.
On Wednesday, the Federal Reserve will release the fifth of eight Beige Books with anecdotal information on current economic conditions from the 12 regional banks. Also Wednesday, the Census Bureau will report new residential construction statistics, including housing starts and building permits, for June.
On Thursday, the Philadelphia Fed will release the Manufacturing Business Outlook Survey for July; the Conference Board will report its Leading Economic Index for June; and the Labor Department will report initial unemployment claims for the week ended July 13. Also Thursday, the European Central Bank will publish a monetary policy decision. The ECB is widely expected to keep its target interest rate at 3.75%, after cutting it by a quarter of a percentage point in June.
On Friday, Atlanta Fed President Raphael Bostic will speak at a conference co-sponsored by the Federal Reserve Banks of Dallas and Atlanta, and New York Fed President Williams will speak at a panel on monetary policy at the Central Bank of Peru’s annual conference in Cusco, Peru, on the Rewiring of the Global Economy.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
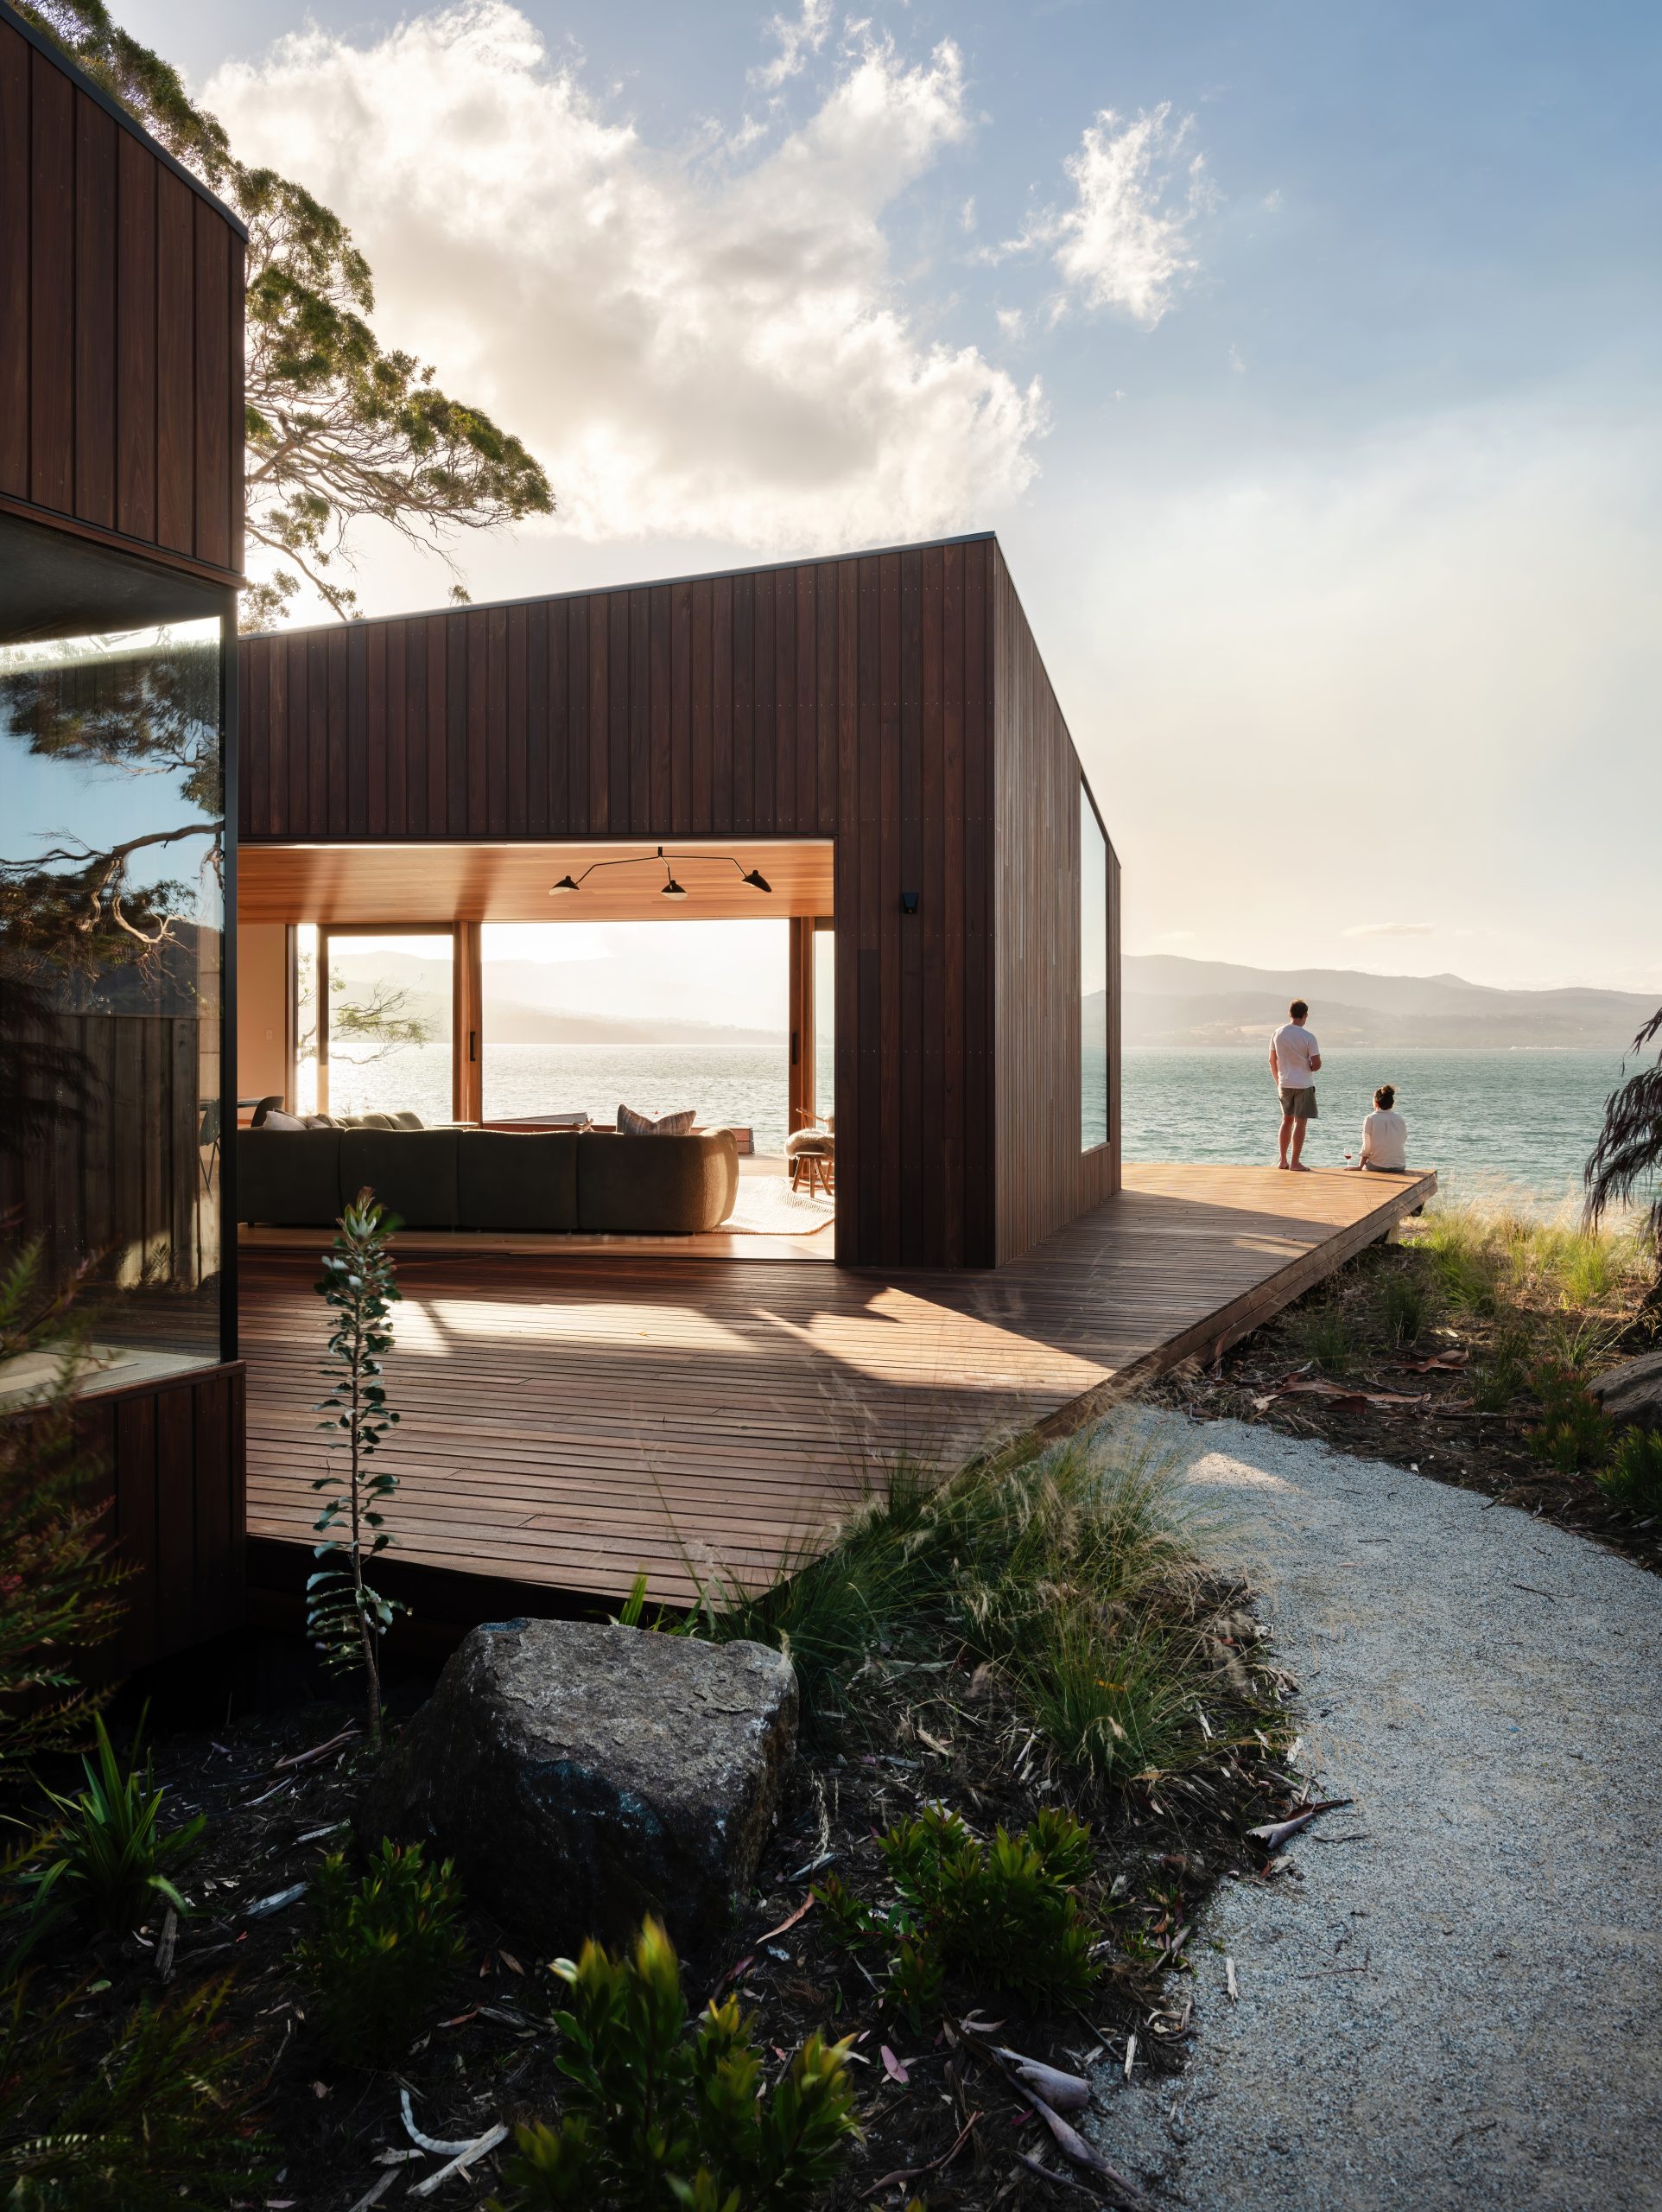
From the shacks of yesterday to the sculptural sanctuaries of today, Australia’s coastal architecture has matured into a global benchmark for design.
When the Writers Festival was called off and the skies refused to clear, one weekend away turned into a rare lesson in slowing down, ice baths included.