





‘Go Woke, Go Broke’ Review: The Worst Investments
Charles Gasparino of Fox Business excoriates the progressive pieties that dominate the modern boardroom.

 4 min
Charles Gasparino is a gladiatorial journalist. When he steps into the arena to fight a money-man or enterprise that he believes is anticapitalist or crooked, he can be brutal. Making an enemy of him is not for the faint-hearted: Watch him trade insults with his critics on social media. He was once a Wall Street reporter for this newspaper, where editors and colleagues remember him for his no-holds-barred style. Which is precisely how we’d describe the approach in “Go Woke, Go Broke,” Mr. Gasparino’s blistering account of “how corporate America became something close to a foot soldier in the progressive movement.” Now a senior correspondent at the Fox Business Network, Mr. Gasparino is also a columnist at the New York Post, whose irreverent, indignant (and often irresistible) tabloid style is very much in evidence here. (Fox, the Post and the Journal share common ownership.)
“Go Woke, Go Broke” is a takedown of “corporate wokeness,” which Mr. Gasparino describes as the “noxious ideology of progressive politics in the boardroom”—an ideology, he says, that “needs to die a thousand deaths.” The book can be seen as a demotic complement to “Woke, Inc.” (2021), by the brainy (and sometimes tiresome) former Republican presidential contender Vivek Ramaswamy. Mr. Gasparino’s is the better book for its plainspokenness: Many more Middle Americans—whose jobs have been outsourced or have been imperiled by the high-minded dictates of “diversity”—will grasp its message. These are the people who, Mr. Gasparino argues, have been shafted by the Wall Street “fat cats” who’ve grown “much fatter” by their “feeding at the ESG trough.”
ESG stands for “environmental, social, and governance”—metrics intended to direct or funnel investment in an ostensibly socially responsible direction. Mr. Gasparino is a populist-capitalist, and ESG is his bête noire, along with “diversity, equity, and inclusion” (DEI). These “leftist shibboleths” have, the author says, “warped” American business practices for nearly two decades and grew in intensity under the second Obama administration.
Mr. Gasparino traces the roots of ESG to the 1980s and ’90s, when business leaders began embracing so-called corporate social responsibility (or CSR, in its now archaic abbreviation). CSR, in time, evolved into bien-pensant notions of stakeholder capitalism, championed by the likes of Klaus Schwab, the founder of the World Economic Forum in Davos, Switzerland. Davos Man, writes Mr. Gasparino, “represents the ultimate marriage of the progressive globalist corporate citizen with the globalist progressive regulatory bureaucrat.”
All this performatively moral investing is a revolt against Milton Friedman, the economist who in 1970 stated that “the social responsibility of business is to increase its profits.” Friedman, writes Mr. Gasparino, would have hated ESG and DEI, “among the most heinously anti-American management philosophies ever developed.” (Readers of Mr. Gasparino’s robust book will realize pretty quickly that nuance is for wimps.)
Basing his book largely on a host of interviews with “company insiders,” Mr. Gasparino gives us entertaining (and informative) accounts of corporate blunders in the name of wokeness. He reminds us of the time AB InBev—the holding company for Anheuser-Busch and its beer, Budweiser—thought it would be a great idea to use a “transwoman influencer” named Dylan Mulvaney to market its top-selling Bud Light. Middle America revolted and stopped buying the beer, heretofore branded as a manly beverage. Mr. Gasparino also recounts how the discount retailer Target was punished by consumers for promoting “tuck-friendly bathing suits for men transitioning to women” alongside rainbow-colored onesies for toddlers. And Disney, recalls the author, erred politically and financially when its chief executive, Bob Chapek, embarked on a bruising battle with Florida’s Gov. Ron DeSantis and challenged the validity of a state law barring public schools from teaching sexual education to children before the fourth grade. In each case, the company’s stock price tanked and sales plummeted.
It enrages Mr. Gasparino that America’s corporate management luxuriates “in progressive causes as a side hustle.” But in some cases, he tells us, these causes are the main course. Among the villains trying to ram ESG down our throats are Larry Fink, the CEO of BlackRock; Jamie Dimon, the CEO of JPMorgan Chase; David Solomon, the CEO of Goldman Sachs; and the “ESG-obsessed” Gary Gensler, President Biden’s chairman of the Securities and Exchange Commission, whom Mr. Gasparino describes as “a male version” of Sen. Elizabeth Warren, “among the most woke, annoying, and . . . dangerous bureaucrats in government.” Add to the list Adena Friedman, the CEO of Nasdaq, which demands that companies seeking to list on its exchange disclose board-level diversity statistics and, if the need arises, explain why they don’t have a diversity of directors. Such demands aren’t, of course, slapped on Chinese companies, which are, Mr. Gasparino points out, curiously exempt from all the wokest rules. When was the last time a Chinese company was asked why it didn’t have a Uyghur on its board, or an LGBTQ+ person?
Attacking Larry Fink as “Mr. ESG,” says Mr. Gasparino, has become “a rallying cry on the populist right,” whose backlash against corporate wokeness has been so fierce that even BlackRock has started to dismount from its moral high horse. Consumers’ Research, a conservative advocacy group pushing back against ESG, derides the abbreviation as “elitists, socialists, and grifters,” as well as “erasing savings and growth”—pungent and effective put-downs. More and more investors are aware that ESG-specific funds are expensive and rarely beat the market. In fact, writes Mr. Gasparino, “they’re some of the worst investments,” even as they make it harder to tackle inflation by forcing curbs on fossil fuels. But Middle America appears to have woken up to the perils of ESG and is giving voice to its displeasure. “It’s now their Arab Spring,” says Mr. Gasparino. This may be hyperbolic overreach, even for the crusading Mr. Gasparino, but he’s confident that America’s version of a grassroots people’s revolt will end better than the one in the Middle East. Let’s pray he’s right.
Mr. Varadarajan, a Journal contributor, is a fellow at the American Enterprise Institute and at Columbia University’s Center on Capitalism and Society.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.

Formula 1 may be the world’s most glamorous sport, but for Oscar Piastri, it’s also one of the most lucrative. At just 24, Australia’s highest-paid athlete is earning more than US$40 million a year.
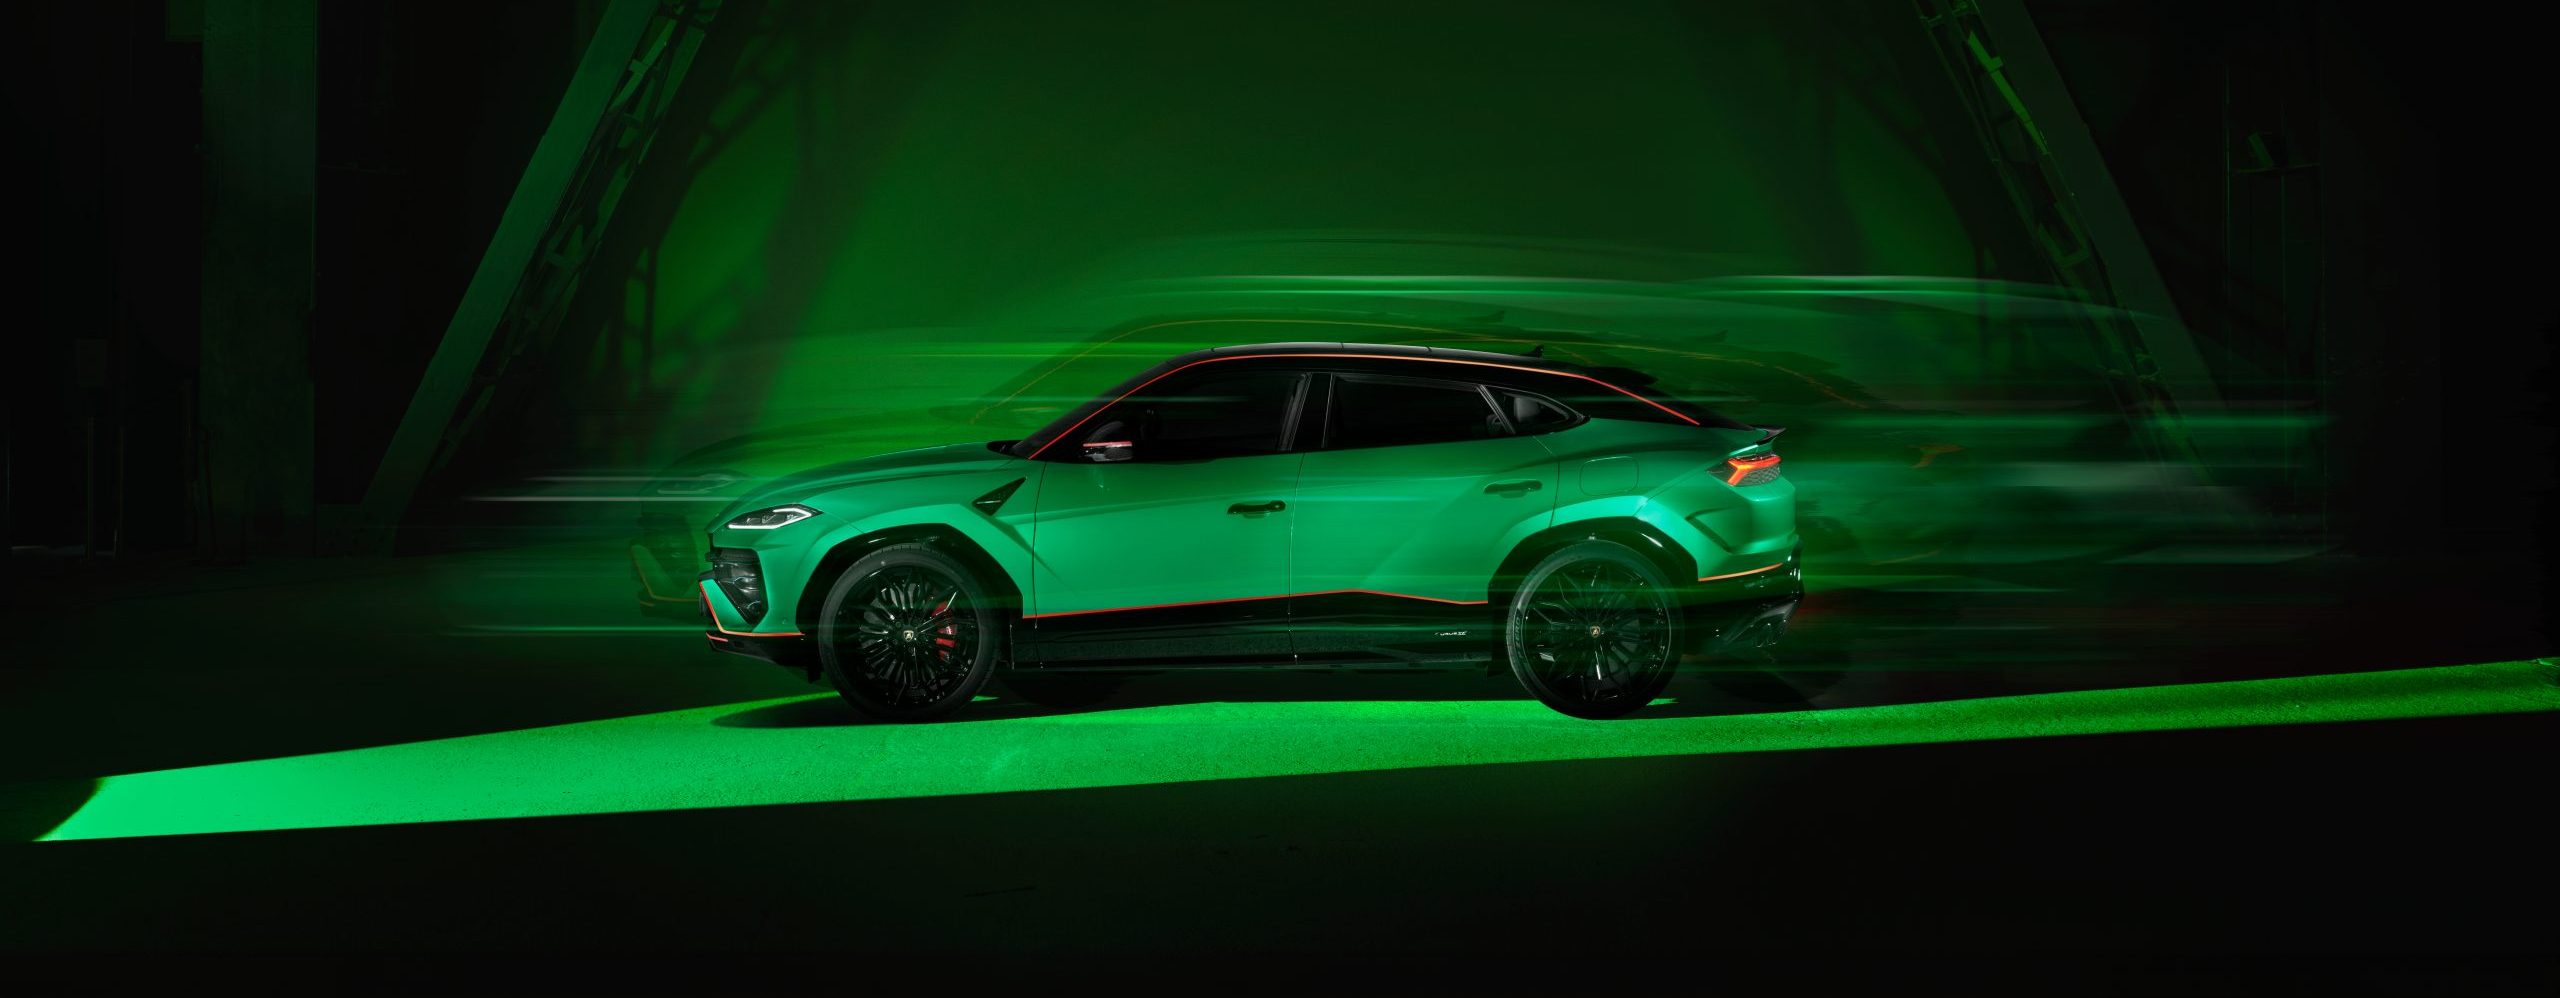
Limited to 630 units, Lamborghini’s latest Urus Capsule pushes personalisation further than ever, blending hybrid performance with over 70 bespoke design combinations.


