In Retirement, It’s Time to Put Our Costs Under the Microscope
We discovered all sorts of things we are paying for that we don’t really need or use. But there’s one cost we’re not ready to face.

 4 min
The first couple of years in retirement are often the most difficult. But they also can set the stage for how you’ll fill the years ahead—both financially and psychologically. Stephen Kreider Yoder, 67, a longtime Wall Street Journal editor, joined his wife, Karen Kreider Yoder, 68, in retirement in late 2022. In this monthly Retirement Rookies column, they chronicle some of the issues they are dealing with early in retirement .
Karen
“Um, Karen?” Steve said without looking away from his computer. He was using the unnaturally neutral tone that means he’s trying not to sound judgmental.
“Oh, no,” I responded. “What is it?”
His screen showed the month’s credit-card statement. “What’s this bill for $28?” he asked. Then, after a few clicks: “Hmm, looks like it’s each month since August last year.”
We were in the study pouring over our spending records to smoke out what we call “parasites”—recurring costs that quietly suck dollars and give little or nothing in return.
I had no idea what the $28 was for, I said, racking my brain for several minutes. “Oh, wait. Yes, last August was when my sewing machine stopped working.” I had found a website that promised advice on how to fix my Bernina Sport 802. It didn’t help, I took the machine to an expert and I forgot about the advice site.
Here it was, much later, leaching a monthly fee. I must have used the credit card thinking it was a one-off.
Parasites like this were also infesting us back when we were working. But ever since our salaries stopped, each dollar seems to have grown in value. And retirement has given us the time to finally ferret out the freeloaders and to analyse what a drain they are on our wallets.
We decided to review every credit-card transaction and bank debit of the past year—and cancel as many recurring charges as we can.
Some parasites are unwitting, like the help-site bill. Others are for services we once wanted and don’t use anymore—like our Netflix account, which we’d been talking about canceling for two years. It was just $15.49 a month, so did we really want to lose it? Yes. We pulled the plug in October. (Sorry, kids, if you were still tapping in.)
Some sponges aren’t obvious from our statements alone. I recently realised that boxes of our eco-friendly dishwasher detergent were piling up. I thought I was buying online when we ran out but had mistakenly OK’d a monthly subscription instead.
Even where a service is useful, there are sometimes free alternatives. I was paying $14.95 a month for audio books. I canceled and now borrow them free of charge from the San Francisco Public Library. We’ll save nearly $180 a year.
We began looking for leaches more broadly and identified a subspecies: the lost-opportunity parasite. After we retired, we began riding city buses and local rail more often, pulling out adult-rate transit cards we’d accumulated. Then it occurred to us that we were leaving money on the table by not getting half-price senior passes: $1.25 for the bus instead of $2.50. Duh!
More lost opportunity awaited in a stack of gift cards I had rubber-banded together in my desk drawer including several from Barnes & Noble bookstores and Peet’s Coffee. I took a bus to the nearest Barnes & Noble, learned there was $30 on the cards and did some early Christmas shopping. All together, the gift cards were storing $225.
The $28-a-month parasite tracing to my sewing machine proved easy to exterminate. I called the customer-care number, negotiated a partial refund of $84 and canceled the subscription.
That will save $336 a year, enough to pay an expert to fix my Bernina several times over.
Steve
There’s a parasite down in the garage, it occurred to me after a bill came in the mail from the DMV.
The letter asked for $162 to renew the registration on my vintage Honda CB750 for a year. I nearly paid it, as I’ve done annually, each year vowing to tune the bike up and get it back on the road within months.
It’s one of two old Honda motorcycles that I’ve written about before—how they once brought me joy in the restoring but now are mostly garage gewgaws.
Our anti-parasite crusade forced me to get honest with myself last month. I could no longer use the excuse that I’ll get to the 750 after I retire. I’ve had two years, and I’m not likely to get to it next year.
So I registered the bike for non operation at $27, saving $135. Now I need to phone our insurer and back out of the $436-a-year policy on the bike. Between those two parasitic bills, I have probably paid more than the value of the bike over the seven years that I haven’t ridden it.
Maybe I can get the other bike on the road, the CB350F. If not, I’ll assign non operational status to it when the DMV bills me for it.
Still, the hardest parasite to face may be the biggest one of all: our house.
We love being retired in San Francisco, and our thriving neighbourhood has proved to be the perfect environment for a couple of aging city slickers. We are walking distance to restaurants, shops, libraries, parks and pickleball courts, and a 20-minute bike ride to the beach or nearly any other place in a city full of vibrant districts. Circles of friends are nearby.
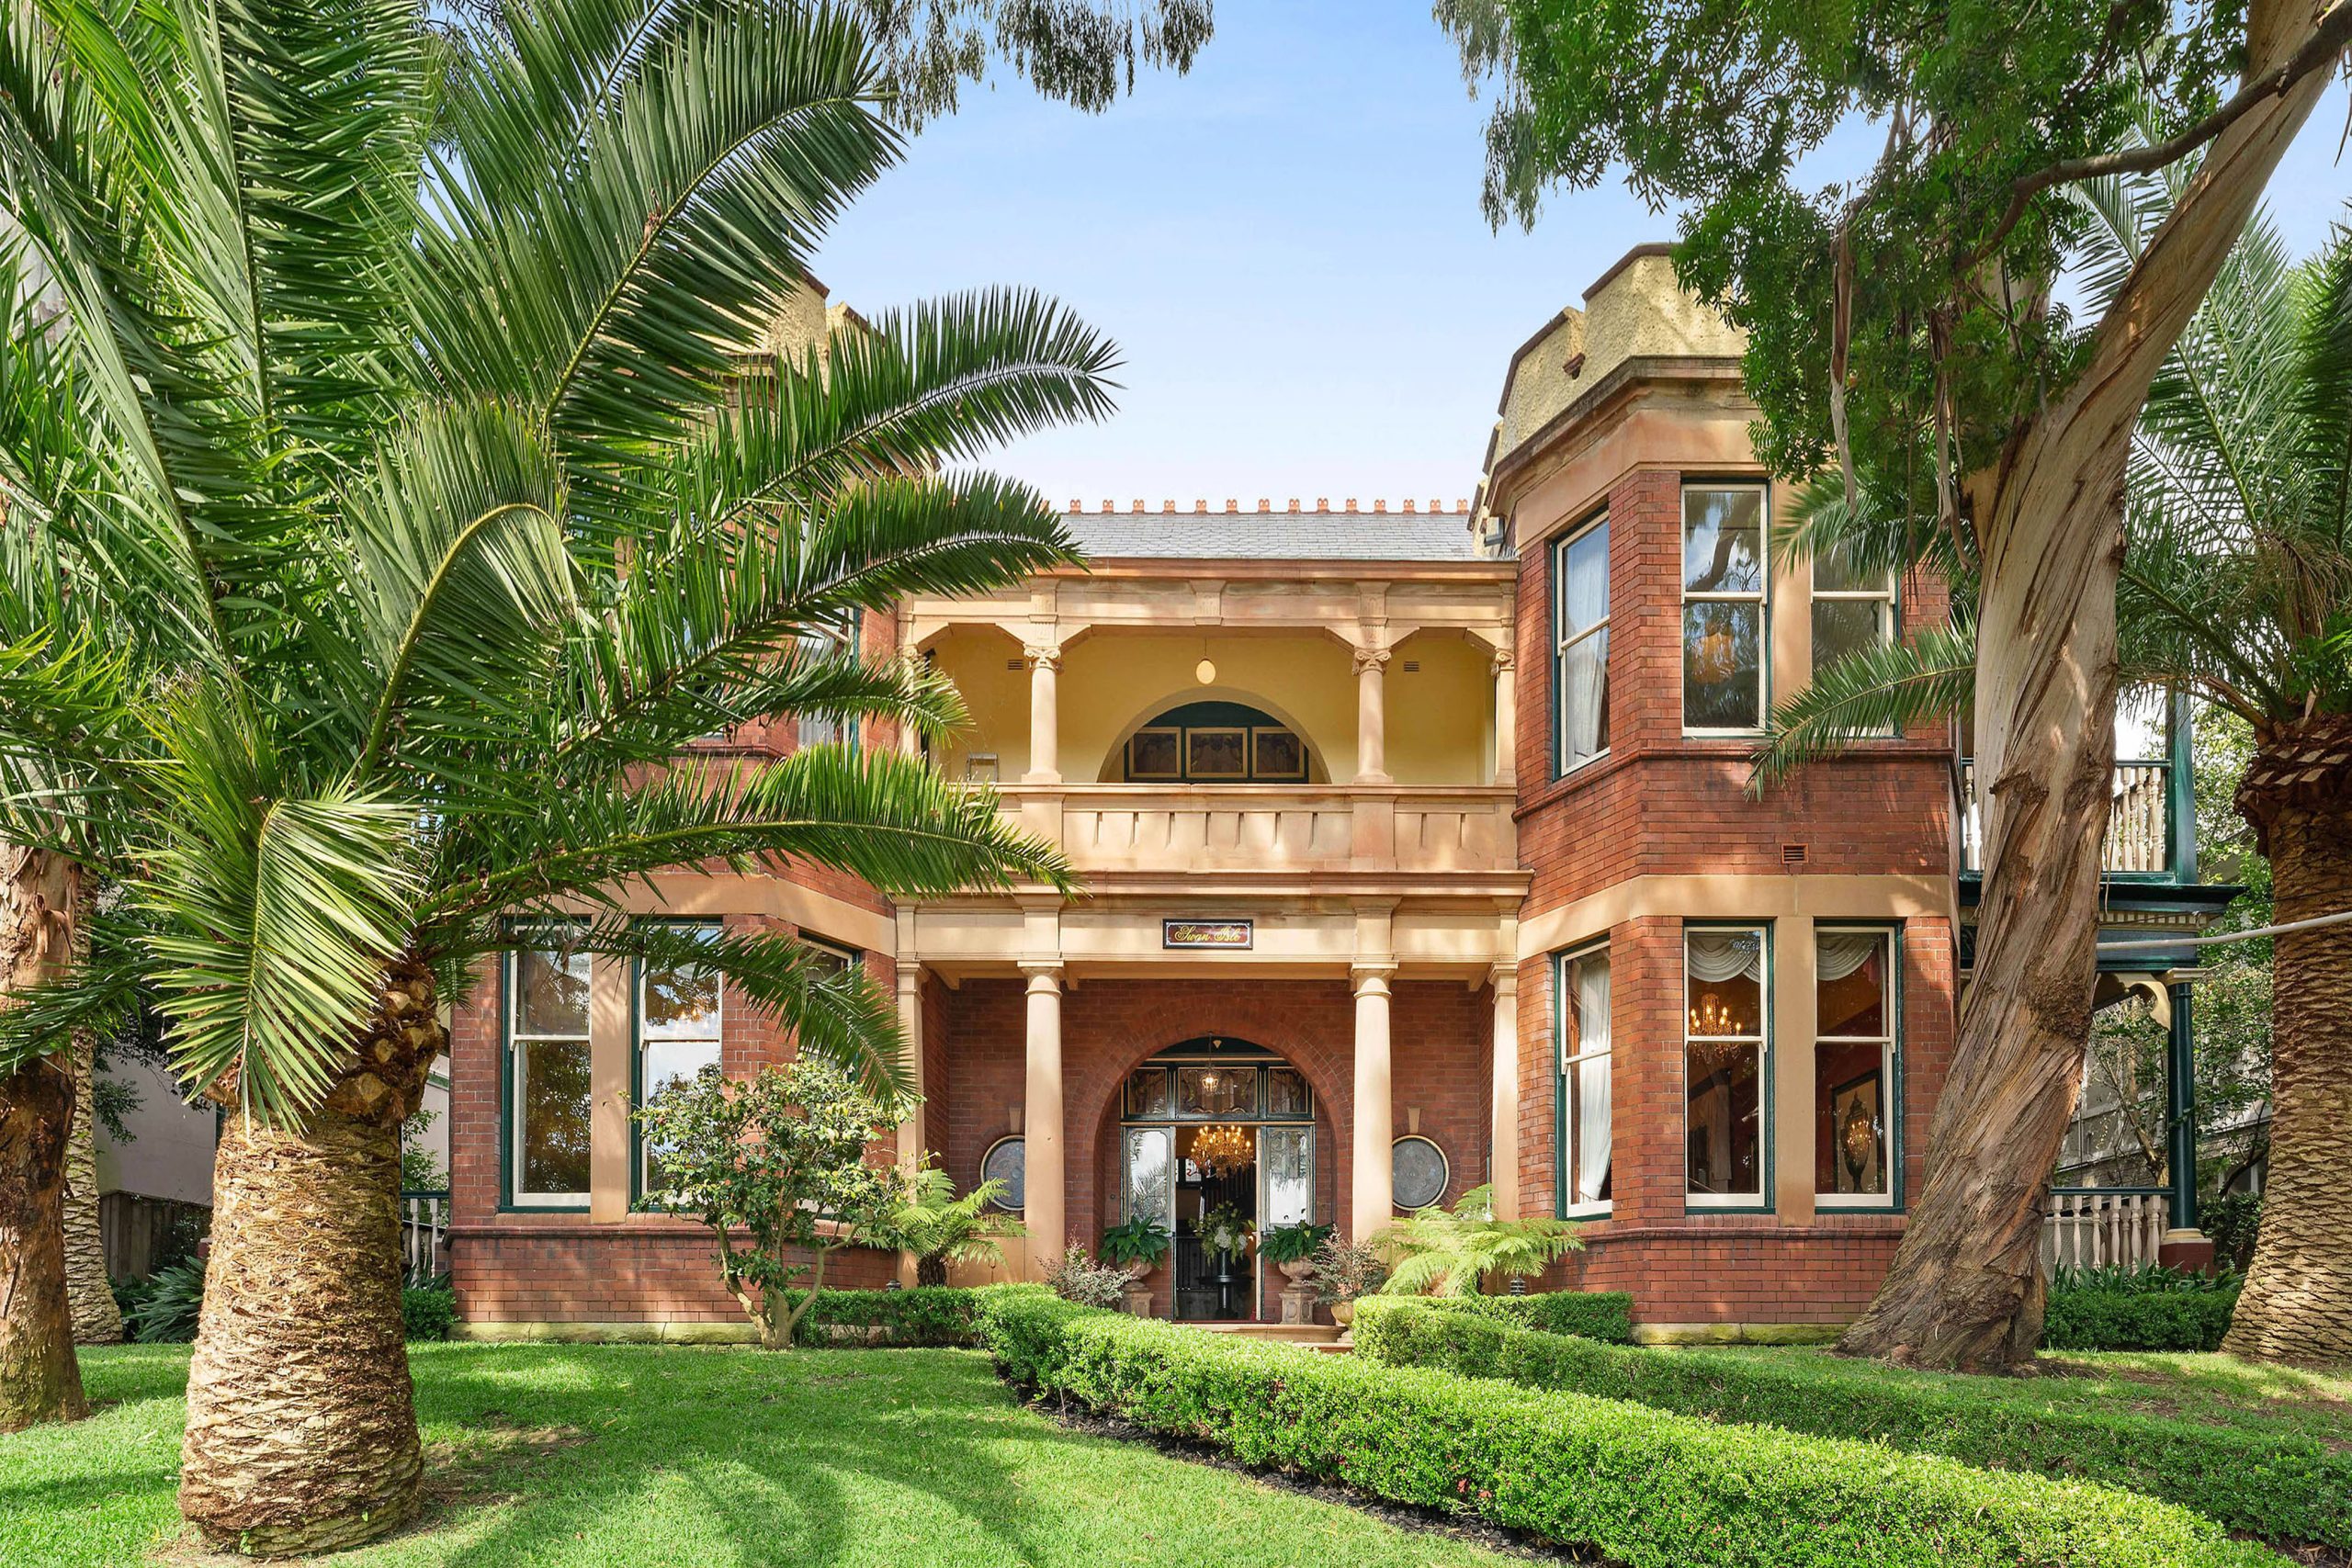
Our home is a Victorian museum piece with a classic San Francisco feel that makes us feel even more part of our city.
But it’s too big, and it is increasingly becoming a financial and psychological drain. What we dish out in mortgage payments, home and earthquake insurance, utilities and property taxes could rent us a decent house in the Midwest with money left over to travel half the year.
There’s also the constant maintenance, the bane of a vintage-house owner. Tourists and residents alike love this city’s Painted Ladies, but we owners must fight constant entropy to keep them made up with paint jobs and preserved detail.
That’s not to mention the costs within. A decrepit old breaker box had been nagging at me from the garage wall for years, silently reminding me every time I walked past that we needed to replace it with a higher-amp box that was up to modern code.
I put off the task because of the cost. I could do it myself when I had time, I imagined, and avoided thinking about it—easy to do when life was busy with workplace and family demands.
I finally hired an electrician, who came in September to replace the breaker box and the wiring that fed it. There’s still the balky ancient redwood gutter to fix, and some plumbing issues.
We’re not ready to sell out and move to the Midwest, which we might eventually do when we’re in our slower years. And we can’t stomach the pain of looking for a smaller place in San Francisco.
So we’ll live with this big parasite for now, the elephant in the room as we hunt down smaller leaches.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Powerhouse real estate couple Avi Khan and Kaylea Sayer welcome their daughter while balancing record-breaking careers, proving success and family can grow side by side.

Here’s how they are looking at artificial intelligence, interest rates and economic pressures.