Eurozone’s Economy Outpaced China and U.S. in 2022
The currency-area grew at a faster clip than its global peers, reversing traditional positions

 4 min
The eurozone economy grew faster than China and the U.S. last year, underlining how the fading Covid-19 pandemic continues to scramble traditional patterns of global growth.
Figures released by the European Union’s statistics agency Tuesday showed the currency- area’s economy grew at an annualised rate of 0.5% as higher energy costs weighed on household spending. This translated into 3.5% growth in gross domestic product for 2022 as a whole, a faster rate than seen in either China or the U.S.
This is unusual. For decades, the big three engines of the global economy have had a pretty stable ranking: China grew fastest, followed by the U.S. and then the eurozone. This all changed last year because of the staggered manner in which major economies reopened in the wake of the pandemic.
Figures released Thursday showed the U.S. economy grew by 2.1% in 2022, a sharp slowdown from the 5.9% rate of expansion recorded in 2021. Earlier this month, China’s statistics agency released figures that showed the world’s second-largest economy grew by 3%, down from 8% the previous year.
The last time that the combined national economies that make up the eurozone grew at a faster pace than that of either China or the U.S. was in 1974. The U.S. economy has typically outpaced Europe’s over recent decades largely because its population has grown more quickly. More recently, the U.S. has led Europe in the development of fast-growing technology sectors.
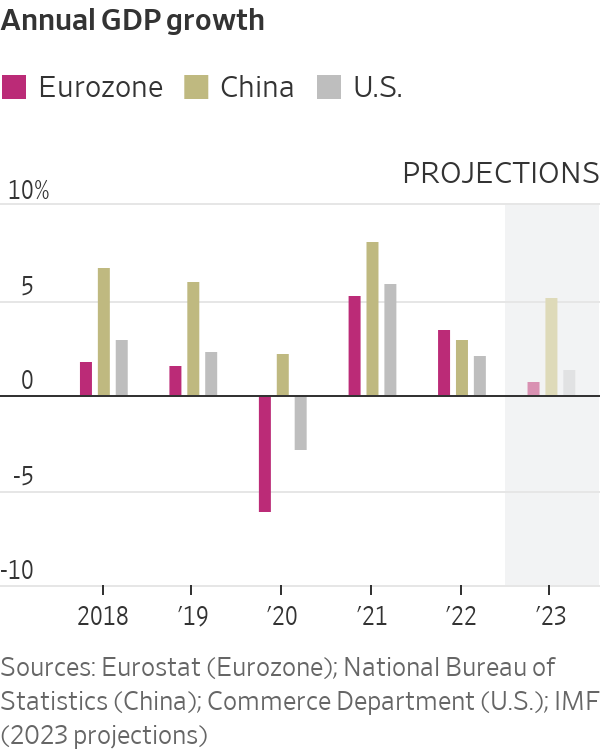
Last year’s unusual growth ranking largely reflects the impact of the Covid-19 pandemic on the world economy, with the timing of lockdowns and re openings leading to big swings in growth, as well as high rates of inflation.
It is an effect that is unlikely to last. As China abandons its zero-Covid policy, it is likely to reclaim its position as the fastest-growing of the big three economic areas. And the war in Ukraine is having a bigger impact on the economy of Europe than that of the U.S. or China, as the slowdown in the last quarter of 2022 testifies.
“2022 was just a weird, weird year,” said European Central Bank President Christine Lagarde during a panel at the World Economic Forum’s annual meeting in Davos earlier this month. “Those are not normal numbers, this is not the usual ranking that you have.”
In the eurozone, the influence of the pandemic on the economy was so strong last year that it offset that of Russia’s invasion of Ukraine and the surge in energy prices it prompted.
While China experienced a series of lockdowns in pursuit of its zero-Covid policy, the eurozone enjoyed its first full year without tight restrictions, and a boost to activity that the U.S. had experienced a year earlier.
The big three economies locked down hard in 2020. But the U.S. reopened more fully from early 2021, outpacing the eurozone and China in the first three months of that year in particular. The eurozone’s reopening boost started later, and carried over into the first half of 2022 as its key tourism industry rebounded.
This year is likely to see the pandemic continue to have a big impact on growth—this time in China. The country lifted many of its zero-tolerance pandemic controls in early December in an abrupt change of course. While that led to an increase in Covid-19 infections and deaths, it also opened the door to a sharp economic rebound in the world’s second-largest economy.
For this year, the United Nations expects China’s economy to grow by 4.8%. It expects both the U.S. and the eurozone to slow, to 0.4% and 0.2% respectively. If it is correct, the normal growth ranking will be restored, although at lower-than-normal rates of growth. And from 2024, the pandemic’s impact is set to wane, unless a more deadly, rapidly-spreading coronavirus variant emerges.
“By 2024 we should be out of the woods,” said Hamid Rashid, head of the U.N.’s global economic monitoring unit. “We are still having the lingering impact of the pandemic in 2022 and 2023.”
High inflation rates, partly a legacy of the pandemic, are also expected to fade by 2024. Inflation rates began to surge in early 2021 as the reopening of the U.S. and other economies led to a surge in demand for goods and services at a time when global supply chains were still impaired.
According to a measure of supply-chain pressures compiled by the Federal Reserve Bank of New York, the blockages caused by the pandemic reached a peak at the end of 2021, and then eased steadily through the first nine months of last year. But that improvement in supply chains stalled in the final three months of 2022 as China imposed lockdowns to counter fresh outbreaks of Covid-19. Supply chains seem set to continue their slow return to prepandemic conditions in 2023 after the zero-tolerance strategy was abandoned.
Rates of inflation around the world appear to be easing, but it has taken unusually aggressive action by global central banks to get to that point. The Federal Reserve has raised interest rates by more than 4 percentage points since March, the largest move in a single year since 1980. The European Central Bank has moved at a slower pace, pushing up its policy rate by 2.5 percentage points starting in July, but that is the fastest increase since it was founded in 1998.
Both central banks are expected to raise their key interest rates this week, with the ECB likely to tighten more than the Fed. Further increases in borrowing costs will affect businesses and households not just in the U.S. and Europe, but around the world.
“The global effects are real, but they are not taken into account by the systemically important central banks,” said Mr. Rashid at the U.N., “it is harder for developing countries to borrow and invest.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates.
The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index rose 1.71 per cent.
Information technology was the strongest major sector, up 2.67 per cent. Megaport gained 4.3 per cent, NextDC rose 3.8 per cent and Life360 added 2.9 per cent, according to the ABC’s closing market report. The move followed a record Nasdaq close and reflected renewed demand for growth assets as oil prices eased.
Consumer discretionary gained 1.29 per cent, while real estate and healthcare each rose 0.76 per cent. The simultaneous strength of technology, discretionary shares and listed property was consistent with a modest easing in market inflation anxiety, although it did not erase expectations of a possible RBA increase at the 29 September meeting.
Energy was the clear laggard, down 1.16 per cent, after Brent crude briefly fell below US$100 a barrel overnight. Origin Energy dropped about 4 per cent, Woodside lost 2.4 per cent and AGL declined 2.3 per cent. Utilities were the weakest sector overall, down 2.03 per cent.
Among larger and liquid movers, Telix Pharmaceuticals rebounded 6.85 per cent after the previous session’s sharp acquisition-related decline. IDP Education jumped 20.67 per cent and was the largest percentage gainer in the ASX 300 screen, while Catalyst Metals fell 14.37 per cent. Those moves should be checked against company announcements before publication; percentage rankings alone do not establish cause or index impact.
Mining performance was mixed. Sunrise Energy Metals rose 12.71 per cent, FireFly Metals added 5.7 per cent and Bellevue Gold gained 4.8 per cent, while Resolute Mining lost 4.44 per cent.
The Australian dollar traded near US71.18 cents late in the session. Oil remained volatile as markets assessed potential US–Iran talks, making energy prices a continuing input into inflation expectations, bond yields and the RBA outlook.
For Wednesday, investors will watch oil, offshore technology leads, Australian bond yields and any new evidence that changes the probability of a September rate rise.
Market dashboard
S&P/ASX 200: 8,757.8, up 25.9 points or 0.30 per cent.
All Ordinaries: 8,951.0, up 0.36 per cent.
Best sector: Information Technology, up 2.67 per cent.
Weakest sector: Utilities, down 2.03 per cent. Energy fell 1.16 per cent.
Material winner: Telix Pharmaceuticals, up 6.85 per cent. Megaport rose 4.3 per cent and NextDC rose 3.8 per cent.
Material loser: Origin Energy, down about 4 per cent. Woodside fell 2.4 per cent.
ASX 300 percentage leader: IDP Education, up 20.67 per cent. Confirm announcement context before publication.
ASX 300 percentage laggard: Catalyst Metals, down 14.37 per cent. Confirm announcement context before publication.
AUD/USD: Approximately US$0.7118 late in the session.
Next catalyst: RBA policy decision on 29 September, oil-price volatility and offshore technology trading.
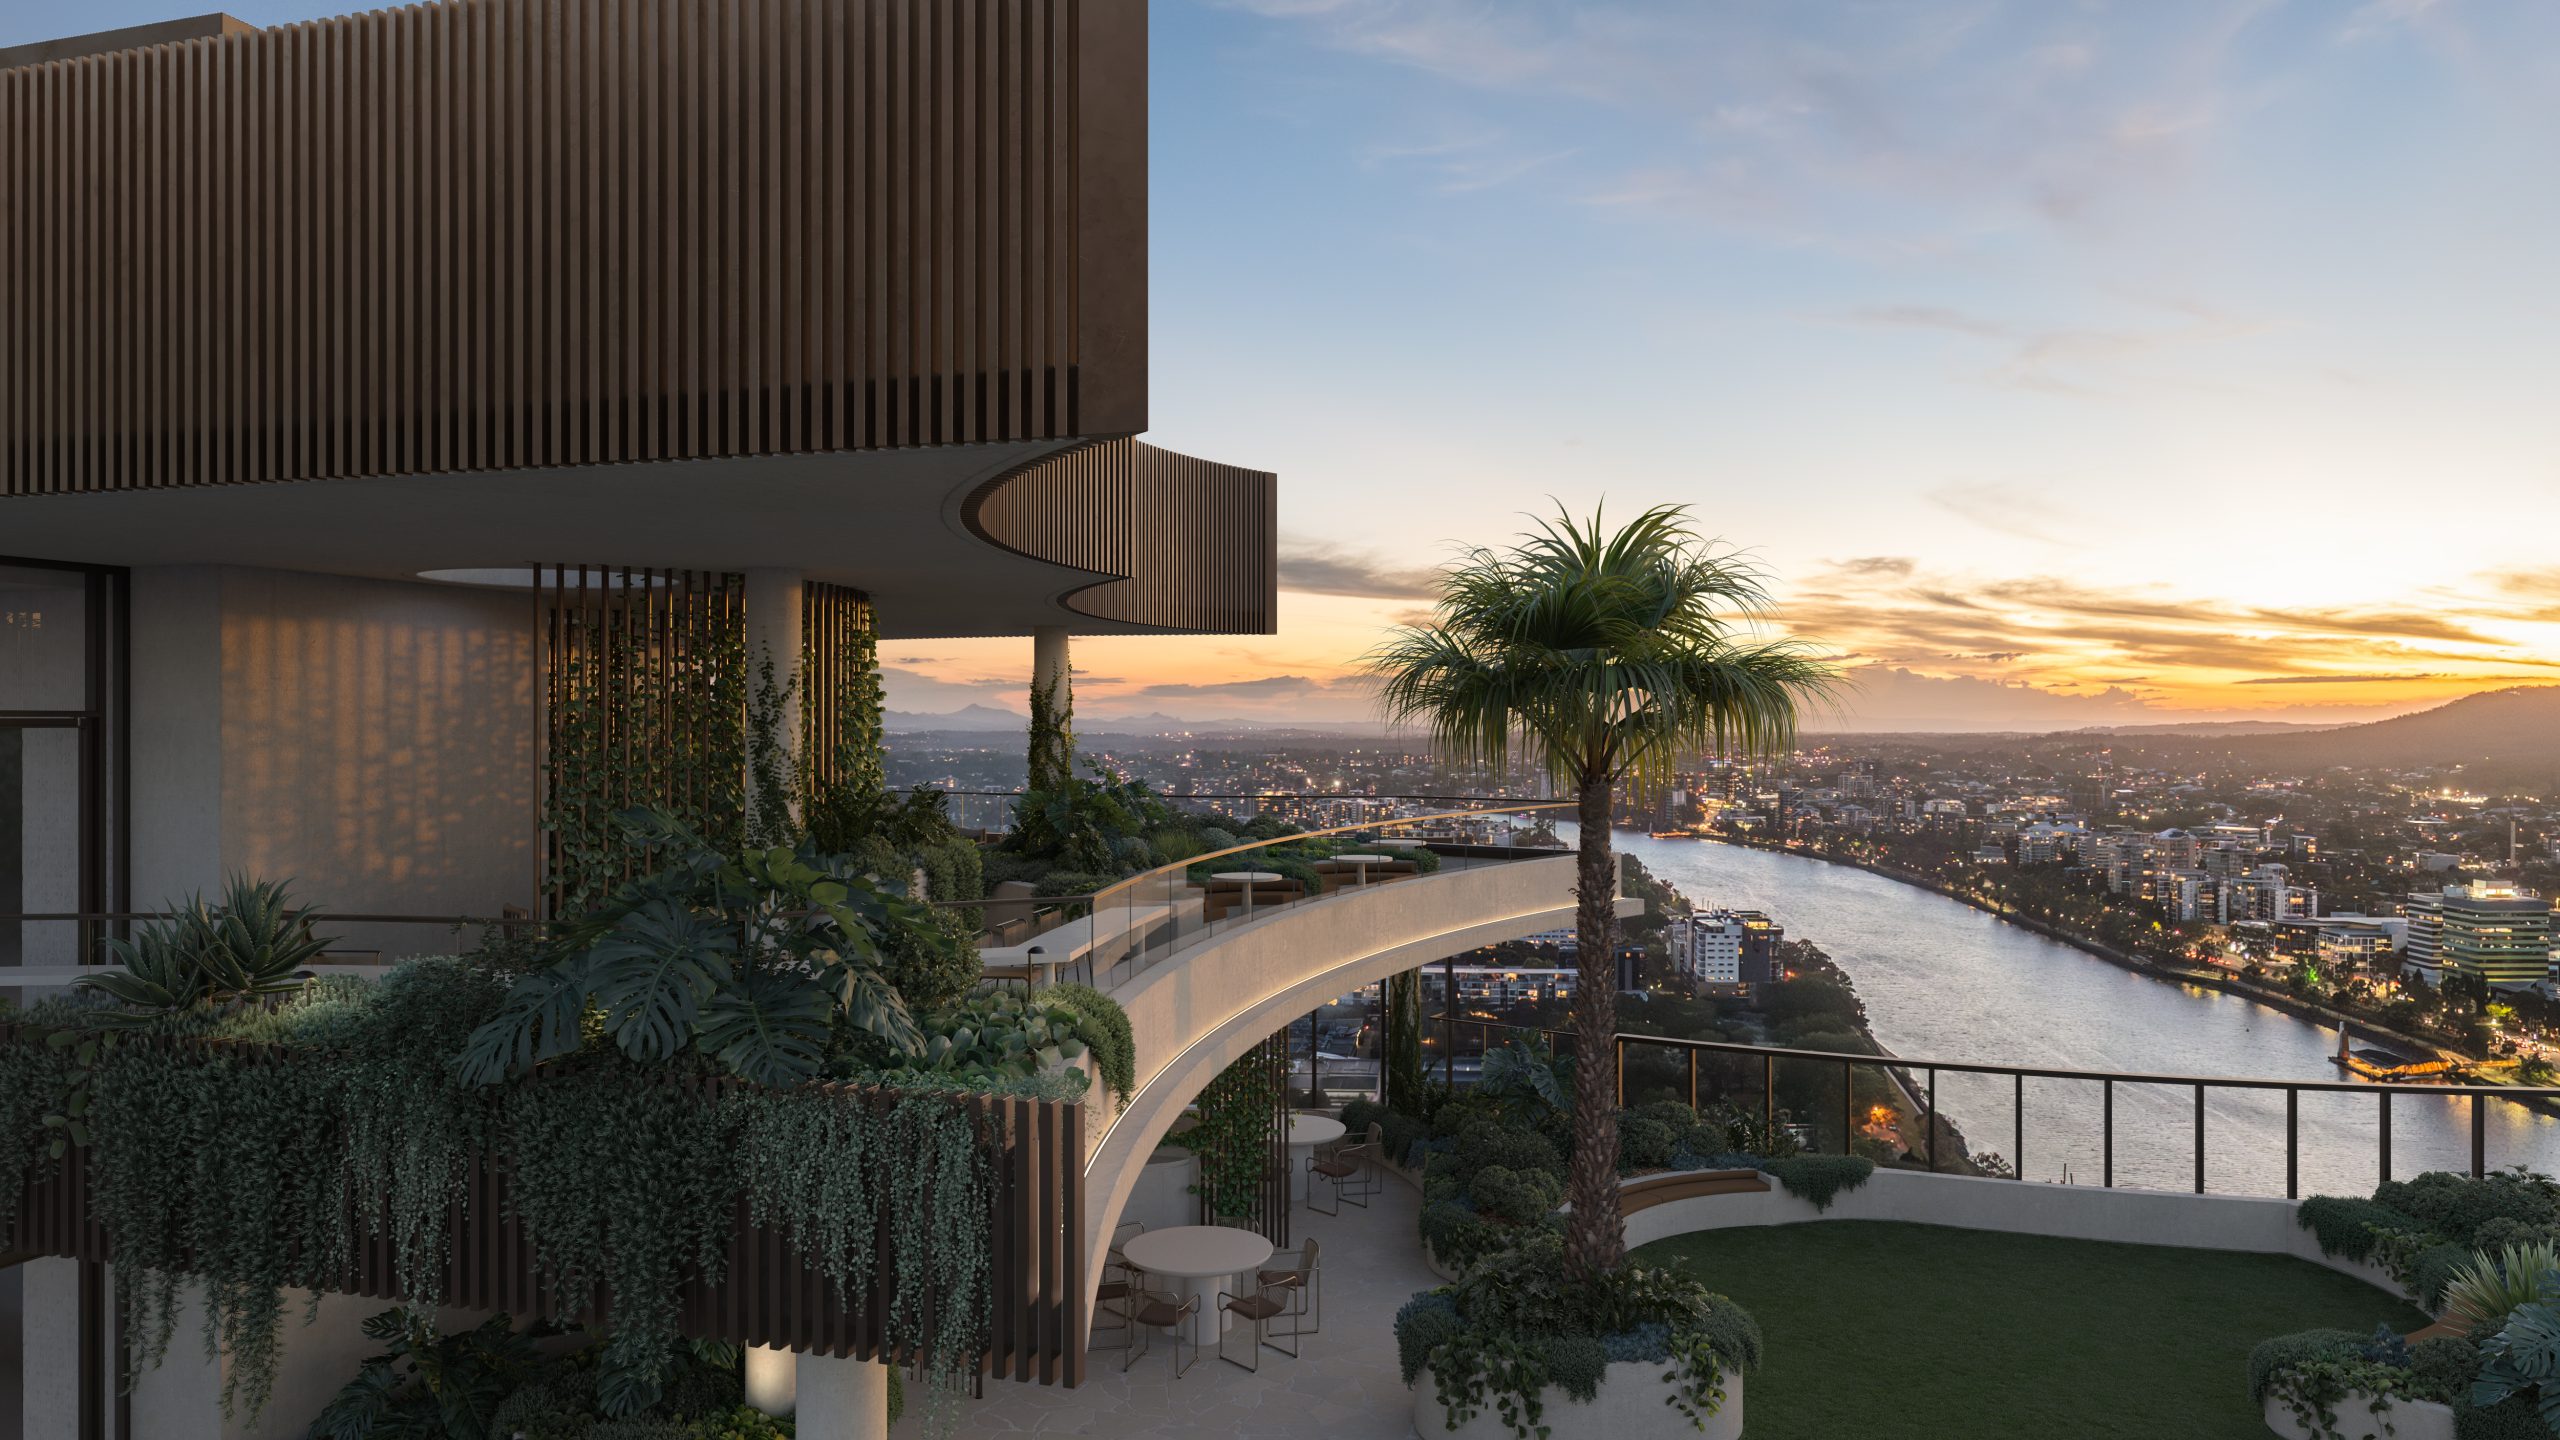
Set on one of the city’s last absolute riverfront sites, The Riversdale by Mosaic combines irreplaceable waterfront ownership with one of Brisbane’s most significant residential opportunities.
Rising rates, construction inflation and shrinking investor confidence are pushing Australia deeper into a dangerous housing spiral that monetary policy alone cannot fix.