China’s EV Juggernaut Is a Warning for the West
Competitive pressure and creativity have made Chinese-designed and -built electric cars formidable competitors

 4 min
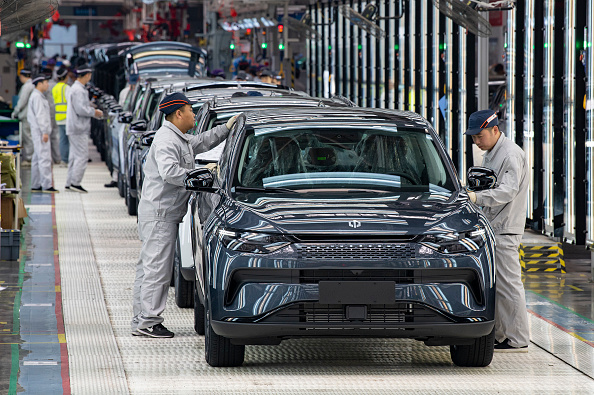
China rocked the auto world twice this year. First, its electric vehicles stunned Western rivals at the Shanghai auto show with their quality, features and price. Then came reports that in the first quarter of 2023 it dethroned Japan as the world’s largest auto exporter.
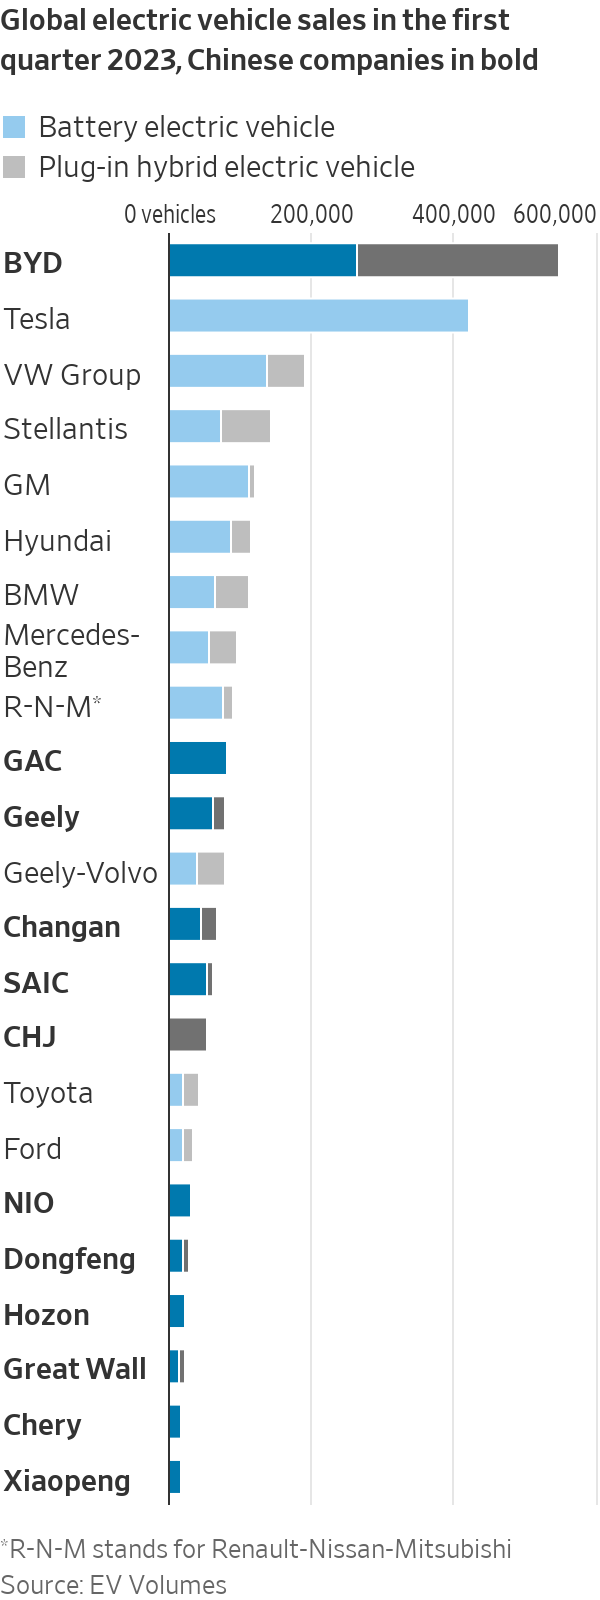
How is China in contention to lead the world’s most lucrative and prestigious consumer goods market, one long dominated by American, European, Japanese and South Korean nameplates? The answer is a unique combination of industrial policy, protectionism and homegrown competitive dynamism. Western policy makers and business leaders are better prepared for the first two than the third.
Start with industrial policy—the use of government resources to help favoured sectors. China has practiced industrial policy for decades. While it’s finding increased favour even in the U.S., the concept remains controversial. Governments have a poor record of identifying winning technologies and often end up subsidising inferior and wasteful capacity, including in China.
But in the case of EVs, Chinese industrial policy had a couple of things going for it. First, governments around the world saw climate change as an enduring threat that would require decade-long interventions to transition away from fossil fuels. China bet correctly that in transportation, the transition would favour electric vehicles.
In 2009, China started handing out generous subsidies to buyers of EVs. Public procurement of taxis and buses was targeted to electric vehicles, rechargers were subsidised, and provincial governments stumped up capital for lithium mining and refining for EV batteries. In 2020 NIO, at the time an aspiring challenger to Tesla, avoided bankruptcy thanks to a government-led bailout.
While industrial policy guaranteed a demand for EVs, protectionism ensured those EVs would be made in China, by Chinese companies. To qualify for subsidies, cars had to be domestically made, although foreign brands did qualify. They also had to have batteries made by Chinese companies, giving Chinese national champions like Contemporary Amperex Technology and BYD an advantage over then-market leaders from Japan and South Korea.
To sell in China, foreign automakers had to abide by conditions intended to upgrade the local industry’s skills. State-owned Guangzhou Automobile Group developed the manufacturing know-how necessary to become a player in EVs thanks to joint ventures with Toyota and Honda, said Gregor Sebastian, an analyst at Germany’s Mercator Institute for China Studies.
Despite all that government support, sales of EVs remained weak until 2019, when China let Tesla open a wholly owned factory in Shanghai. “It took this catalyst…to boost interest and increase the level of competitiveness of the local Chinese makers,” said Tu Le, managing director of Sino Auto Insights, a research service specialising in the Chinese auto industry.
Back in 2011 Pony Ma, the founder of Tencent, explained what set Chinese capitalism apart from its American counterpart. “In America, when you bring an idea to market you usually have several months before competition pops up, allowing you to capture significant market share,” he said, according to Fast Company, a technology magazine. “In China, you can have hundreds of competitors within the first hours of going live. Ideas are not important in China—execution is.”
Thanks to that competition and focus on execution, the EV industry went from a niche industrial-policy project to a sprawling ecosystem of predominantly private companies. Much of this happened below the Western radar while China was cut off from the world because of Covid-19 restrictions.
When Western auto executives flew in for April’s Shanghai auto show, “they saw a sea of green plates, a sea of Chinese brands,” said Le, referring to the green license plates assigned to clean-energy vehicles in China. “They hear the sounds of the door closing, sit inside and look at the quality of the materials, the fabric or the plastic on the console, that’s the other holy s— moment—they’ve caught up to us.”
Manufacturers of gasoline cars are product-oriented, whereas EV manufacturers, like tech companies, are user-oriented, Le said. Chinese EVs feature at least two, often three, display screens, one suitable for watching movies from the back seat, multiple lidars (laser-based sensors) for driver assistance, and even a microphone for karaoke (quickly copied by Tesla). Meanwhile, Chinese suppliers such as CATL have gone from laggard to leader.
Chinese dominance of EVs isn’t preordained. The low barriers to entry exploited by Chinese brands also open the door to future non-Chinese competitors. Nor does China’s success in EVs necessarily translate to other sectors where industrial policy matters less and creativity, privacy and deeply woven technological capability—such as software, cloud computing and semiconductors—matter more.
Still, the threat to Western auto market share posed by Chinese EVs is one for which Western policy makers have no obvious answer. “You can shut off your own market and to a certain extent that will shield production for your domestic needs,” said Sebastian. “The question really is, what are you going to do for the global south, countries that are still very happily trading with China?”
Western companies themselves are likely to respond by deepening their presence in China—not to sell cars, but for proximity to the most sophisticated customers and suppliers. Jörg Wuttke, the past president of the European Union Chamber of Commerce in China, calls China a “fitness centre.” Even as conditions there become steadily more difficult, Western multinationals “have to be there. It keeps you fit.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From Italian vegetable-tanned leather to real-world training insight, Australian brand PK9 Gear is redefining what luxury means for discerning dog owners.
As interest rates, inflation and market sentiment fluctuate, investors are being urged to focus on data, not panic.