Why the Drivers of Lower Inflation Matter
Competing effects of central banks, healing supply chains affect recession odds

 4 min
Recent good news on inflation has ignited a debate over how much central banks’ interest-rate increases are responsible.
The answer matters for where inflation and interest rates are headed. The Federal Reserve and the European Central Bank in the past week lifted their benchmark interest rates to 22-year highs and left the door open to additional increases.
If higher rates weren’t responsible for the progress on inflation to date, that suggests central banks may be able to lower them before a painful recession sets in.
Central banks generally see their influence on inflation coming through higher rates damping the demand for goods, services and workers, which leads to higher unemployment. That in turn puts downward pressure on prices and wages.
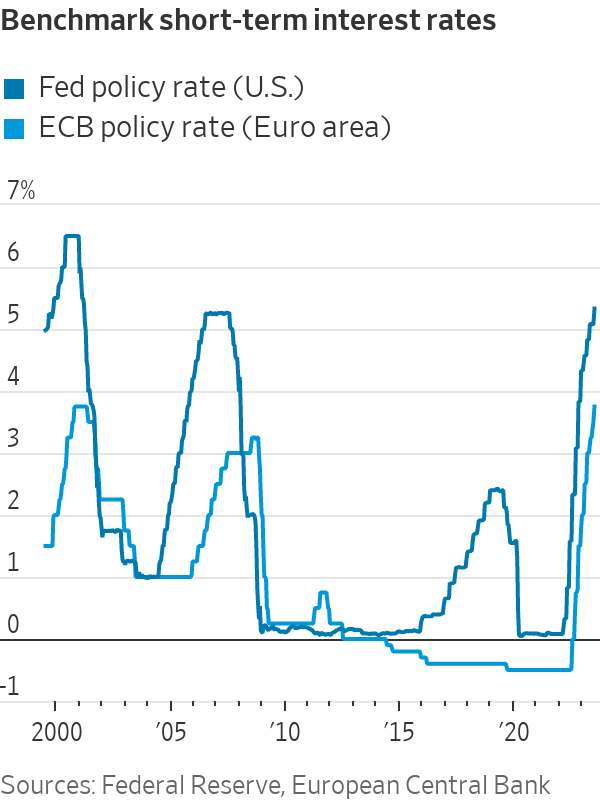
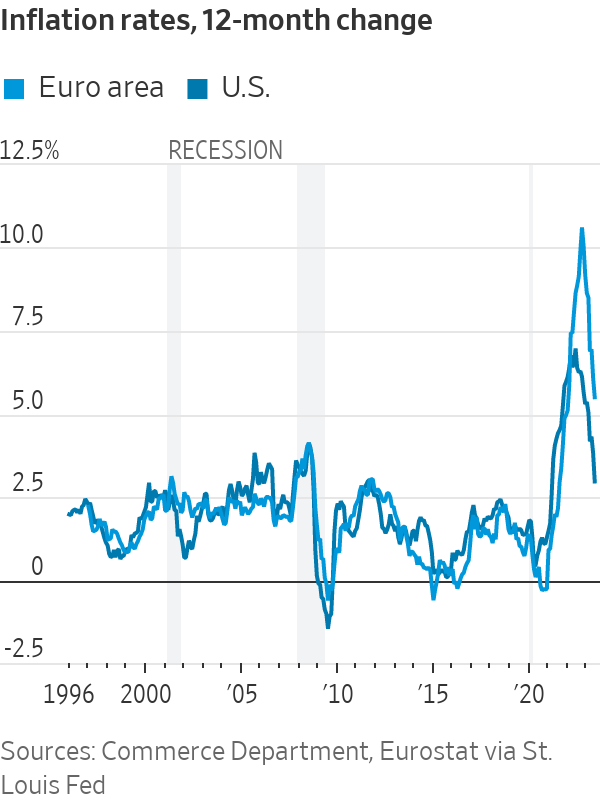
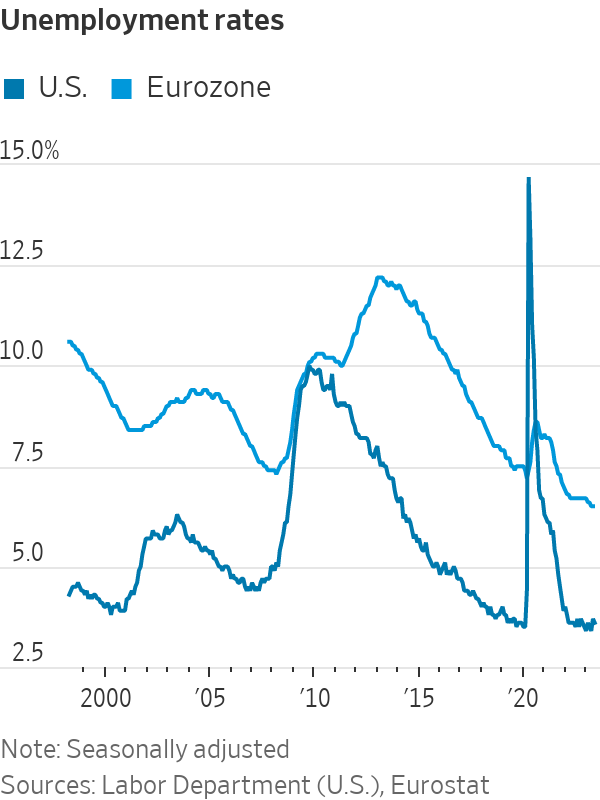
Only the second part of that sequence has occurred. Inflation fell to 3% in the U.S. in June, according to the Fed’s preferred gauge, the personal-consumption expenditures price index, down from 7% one year earlier. Yet the unemployment rate, at 3.6% in June, has held steady for the past year.
In the eurozone, inflation declined to 5.5% in June, the lowest level in nearly 18 months, and unemployment has drifted to the lowest in more than 25 years.
There are competing explanations for this.
One camp argues that inflation has been mostly driven by supply shocks that are going away on their own—much as a postwar surge in the late 1940s unwound by itself. The ripple effects gave the illusion of broader, more persistent price increases.
Take the auto market. Sellers weren’t able to meet pent-up demand two years ago, leading to huge price increases, which in turn spawned higher prices later on for car repairs and auto insurance.
Similarly, a surge in household formation during the pandemic sent up housing prices and rents.
The first camp attributes most of the recent decline in inflation to the ebbing of these one-time supply disruptions, not rate increases, which are supposed to work through the labor market. “It’s calling into question a lot of the old assumptions,” said Lindsay Owens, executive director at the Groundwork Collaborative, a liberal think tank.
A second camp, which includes most economists, disagrees. They say monetary policy kept demand for goods, services, and labor lower than otherwise, taking pressure off strained supply chains and allowing price pressures to ease.
Interest rates can also influence behaviour. The prospect that central bankers would risk a recession to bring down inflation may have influenced expectations of price- and wage-setters, including corporate executives who plan annual budgets for investment and hiring.
Jamie Dimon, chief executive of JPMorgan Chase, warned one year ago of an economic “hurricane” as central banks accelerated rate increases. “You’d better brace yourself,” he said in June 2022, and pledged the bank would be “very conservative” with its balance sheet.
“Inflation is coming down precisely because the Fed avoided more excess demand growth, and they anchored inflation expectations,” said Angel Ubide, head of economic research for global fixed income at Citadel, a hedge-fund firm.
Inflation would be higher now if not for Fed rate increases, “and maybe still rising,” said Karen Dynan, an economist at Harvard University.
In 2021, supply-chain constraints meant even marginal increases in demand led to unusually large price increases. The reverse might be true now: Marginal decreases in demand can bring down prices faster, particularly if more supply is becoming available.
The car market illustrates how monetary policy has been transmitted. Rising rates raised monthly payments, damping demand and robbing sellers of pricing power. In addition, since March, banks appear to be rejecting more car-loan applications.
“That’s leading to a new group of people getting squeezed out of the market, and therefore, it’s playing a role putting downward pressure on prices,” said Julia Coronado, founder of economic-advisory firm MacroPolicy Perspectives.
In Europe, economic growth has stalled since late last year. Business surveys in the past week suggest that growth is weakening sharply, especially in manufacturing, which is most sensitive to interest rates.
The net share of banks reporting increased loan demand declined to a record low in the three months through June, according to an ECB survey of banks. Credit growth to households is the lowest since mid-2016.
Asked at a news conference on Thursday about the transmission of ECB rate increases to growth and inflation, President Christine Lagarde said that in the financial system, “a lot has been transmitted. A lot. We know that. In the economy at large, not as much yet.”
A report published by German insurer Allianz identifies three different forces on the U.S. inflation rate since the second quarter of 2022. Higher inflationary pressures from consumption growth, strong labor markets and government spending added 4 percentage points; fading supply-chain disruptions subtracted five points, and Federal Reserve actions subtracted another five. The net impact was that inflation fell 6 percentage points, whereas it would have fallen only one point without the Fed’s actions.
Fed Chair Jerome Powell said rate increases are “working about as we expect, and we think it’ll play an important role going forward” in bringing down prices for the most labor-intensive services.
Monetary policy has also affected the labor market, but this has shown up in declining job-vacancy rates rather than rising unemployment, some economists say.
Hiring plans in the eurozone services sector are dropping rapidly, according to a survey this month by the European Commission, the European Union’s executive body.
“The labor market is normalising on both sides of the Atlantic, reflecting the impact of higher rates,” said Stefan Gerlach, a former deputy governor of Ireland’s central bank.
The debate over the effect of rate increases also matters for how much further, if at all, central banks need to lift them. Optimists underestimated how much strong demand lifted inflation two years ago. Pessimists may be overestimating the importance of constraining demand to bring it down now.
Gerlach expects inflation to continue declining as higher rates sap demand. “I’m worried central banks have done too much,” he said. “They may have felt embarrassed about having misunderstood inflation the first time.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Queensland-based builder-developer MAYD has unveiled an exclusive first look at its anticipated ultra-luxury North Kirra mixed-use project as it lodges a minor amendment with the City of Gold Coast Council. The project sits across a 4,742sqm amalgamated landholding spanning seven parcels at 2–6 Pacific Parade and 27–33 Golden Four Drive, Bilinga, which MAYD secured in …
Continue reading “MAYD”s North Kirra Plans Unveiled Ahead of Early 2027 Launch”

A luxury lifestyle might cost more than it used to, but how does it compare with cities around the world?