Do You Have What It Takes to Be a ‘Personality Hire’?
Productivity comes second for charming employees who make workplaces more fun

 4 min
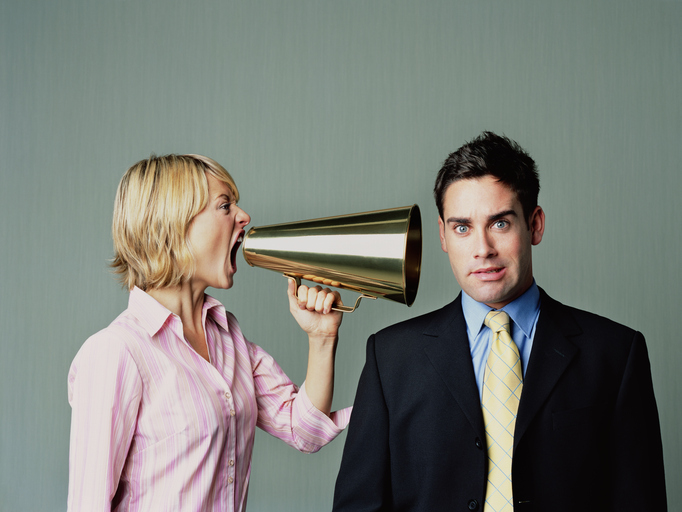
If you get further on charm than skill and carry a workload light enough to float atop your bubbly demeanor, then you might be a “personality hire.”
Charismatic employees lay the foundations of positive corporate cultures—or leave teammates to pick up the slack. While some people proudly advertise themselves as personality hires on LinkedIn, others roll their eyes.
“It’s annoying,” says Lauren Gomes Atwood , a project manager in upstate New York. “They always have time to hang out in the hallway, but when do they sit down and work?”
Atwood, 39 years old, says she worked with a personality hire in a previous job. Though fun to be around, the person eventually generated resentment and, after winning a promotion , prompted several co-workers to quit, she says.
Atwood started a remote job last month and says her search took longer than expected, partly because interviewers seemed as interested in her vibe as they were in her experience. She describes herself as matter-of-fact and says she doesn’t give off the effervescence some employers appeared to be looking for.
Bosses want the warm-and-fuzzies as the mood at work is generally sour . One-third of U.S. employees say they’re engaged in their jobs—near an all-time low, according to Gallup’s annual report on the state of the workforce, released this month. Half of workers say they feel a lot of stress, and 49% are interested in new job opportunities or actively applying.
With so many lonely, unhappy charges, bosses are desperate for good workplace energy. They say camaraderie is hard to build on hybrid schedules, so they prize upbeat employees whose energy is (hopefully) infectious.
Michael Zachary , a security manager at Pratt & Whitney, says he learned the value of a winning disposition in the Navy. He noticed qualities like collegiality and willingness to learn often proved more critical to new recruits’ success than natural talent.
Certain roles at the defence contractor where he works now are highly specialised and must be filled by the most technically qualified candidates, he says. But others, like data-entry clerks, could be performed adequately by dozens of applicants.
“In that case, I’m going to hire the nicest person to be part of the group,” says Zachary, 38.
Meme to management strategy
The concept of a personality hire—like quiet quitting and lazy-girl jobs before—crystallised on social media. Few have captured the essence better than comedian Vienna Ayla, who plays a Miss Congeniality type in skits that have been viewed tens of millions of times on TikTok and Instagram.
The running joke is that her all-style-no-substance character contributes nothing, until she becomes a hero through schmoozing. In one bit, she gets her team a deadline extension by buttering up the chief executive. In another, she calls in a favour from the mayor, who happens to be her workout partner in an “ass and abs” exercise class.
Ayla, 27, tells me she hears from viewers who work with people like her character. Many feel frustrated, while others concede that personality hires can prove their worth in key moments, despite their lack of hustle.
“I kind of admire that type of person who doesn’t get so worked up but still manages to save the day,” says Ayla, who describes her real-life persona as type A.
Businesses don’t want caricatures, but many judge applicants differently than they did during hiring sprees a couple of years ago, says Brian Vesce , co-founder and CEO of RefAssured, a candidate-reference startup.
Skill was king during the talent war of 2021 and 2022, but recent layoffs suggest a lot of companies believe they have enough, or even too many, capable employees.
“We are seeing more employers looking for the right personality when a role opens up,” Vesce says.
Sensing the shift, he launched RefAssured last year in an attempt to measure characteristics in job candidates that are often called “intangibles.” Using the company’s software, references answer a series of questions about how an applicant communicates, handles stress, takes feedback and manages conflict. The responses yield a candidate’s soft-skill rating on a five-point scale.
Customers include 10 of the country’s 100 largest staffing agencies, Vesce says, and he expects to triple that total by year-end.
Red flag or badge of honour
Personality hires are a growing presence in tech, as efficiency-minded companies seek engineers who can also make time with customers, says Lorde Astor West , founder of RadHash, which makes back-end software for startups. But people who excel at gabbing about technology products usually aren’t the best coders, in her experience.
“The life of the party might be an individual who isn’t as capable, and now you have other team members who are having to make up the difference and fix mistakes,” she says.
Astor, 49, leads a team of about 100 employees and contractors and says she’s developed an appreciation for the snippy or introverted people who get things done. Give her a pricklebush over a personality hire any day.
Others wear the personality-hire label proudly. They say keeping their energy up takes effort and makes people around them better.
Danielle Norris calls herself a “personality hire meets hard work” on LinkedIn. She tells me emotional intelligence is among the top qualities she brings to her role as a marketing manager at the Jonus Group, a recruiting firm for insurance and finance companies. In meetings, she says she’s able to sense when a colleague is hesitant to share an idea and can help put that person at ease with a smile or encouraging word.
That leads to greater collaboration and results, according to Norris, 32.
“I bring the vibes,” she says. “I’m always looking to have a good time, but I’m still able to drive my team to success.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Three completed developments bring a quieter, more thoughtful style of luxury living to Mosman, Neutral Bay and Crows Nest.

An opulent Ryde home, packed with cinema, pool, sauna and more, is hitting the auction block with a $1 reserve.