How to Complain at Work the Right Way and Get Ahead
Speaking up gracefully can impress your boss and help solve problems fast

 4 min
Want to advance your career? Learn to complain well.
Stay silent and you’ll stew in resentment and let burgeoning problems fester. Speak up and you can alert leaders to hidden issues, fix the frustrating parts of your job and show you’re ready for the next step up.
Of course, you have to do it gracefully—or risk becoming the department whiner.
“You really don’t want to come in as, ‘Woe is me,’” says Dina Denham Smith, a San Francisco-area executive coach who works with clients such as DocuSign Inc. and Adobe Inc.
In recent months, she has heard from leaders frustrated by hefty workloads and head counts hollowed out by layoffs. Some managers and employees are irked by negative performance reviews they see as unfair, as companies move on from an era of gentle feedback and look for new ways to cull the ranks.
Ms. Smith advises clients to approach their bosses armed with potential solutions. Stick to the facts, and the impact the problem is having on the business. If your team is too small, what projects are suffering? What opportunities are you having to forgo because of this roadblock?
Lay out what you have tried so far to show you have taken initiative. Don’t be accusatory or gossipy. Pitch your proposed fix, but leave the door open for their input.
“Do you see other paths?” Ms. Smith recommends asking. If you rally your manager’s help in figuring out a solution, she will be more bought in and fight harder to get the change done with her higher-ups.
The words you use matter, says Jim Detert, a professor at the University of Virginia’s Darden School of Business and author of a book about speaking up at work. He advises avoiding overly definitive statements such as, “It’s obvious we should fix this,” or “It’s so clear we have a problem,” so you don’t alienate anybody who might think it’s ambiguous.
Other triggering phrases involve frequency, for instance, “You never do this,” or “You always do that.” The person you’re complaining to will immediately focus on trying to disprove your point, Dr. Detert says.
“You lose credibility because now you’ve sort of exposed yourself as exaggerating or ignoring inconvenient data,” he says.
Start statements with “we,” not “I,” showing you’re on the same team. To link ideas, use “and” not “but.” For example, instead of saying “I know this is your baby, but we need to move on,” try, “We’ve had a great start, and I have some ideas to take it to the next level.” The listener will feel less threatened, Dr. Detert says.
Remember that fielding complaints can be exhausting for the boss, who is often bombarded daily by pleas for resources, gripes about teammates and vaguely passive-aggressive demands from the head of that other department.
“We’re your workplace, not your babysitter,” says Ted Blosser, chief executive of WorkRamp, a maker of training software. Over the past several years, he says he has dealt with employee grumbles about everything from the company’s optional holiday party to burnout in folks’ personal lives.
These days, with the mood in tech shifting, he advises managers to keep conversations with workers centred on the nine to five. Constructive complaints about the business are fine in doses, he says, recommending workers focus 90% of their communication to higher-ups on general updates and showing they are doing the work. For the remaining sliver that is griping, be positive and concise, he says, and come armed with data to show the problem you are highlighting matters.
For instance, one of Mr. Blosser’s managers scheduled a 15-minute Zoom chat with him to point out that the company’s sales pitch was weak. She tallied up customer reactions and pinpointed the exact slides that weren’t resonating, he says. She didn’t blame the marketing team for the original language that wasn’t working. Impressed with her candour and proposed solution (new slides that ended up closing sales), Mr. Blosser now goes to her when he needs advice.
In addition to impressing a higher-up, complaining well could improve your performance.
A recent study by researchers including Dr. Detert found that sales employees at an insurance company who vented to peers about problems posted a 10% decline in performance. When workers took issues to their bosses, their performance increased by up to 15%. Instead of wasting time grousing, they brought the problem to someone who could do something about it, Dr. Detert says.
Unleashing your complaints without restraint can backfire. When Matt Plummer was denied a promotion at a previous consulting job, he immediately launched into a speech about how being passed over sent a message to all high-performers at the firm. He warned there would be an exodus as a result.
“As you can imagine, it didn’t go over well,” says Mr. Plummer, now the head of Zarvana, a coaching and corporate training firm. Though he earned the promotion during a subsequent review cycle, he says, the senior leader he complained to ignored him for months.
Now, when frustrated by criticism or a project gone awry, he forces himself to pause before deciding what to share.
Adam Steel, a scientist in the Baltimore area, used his commute to a previous employer to vent to an audience of one. There, in the privacy of his car, he would rehearse his points out loud.
“I would have these kinds of fictional arguments,” he says.
The exercise got the emotion out, and he’d sometimes realise his concerns were petty or easily slapped down by counterpoints. At the office, Dr. Steel would stress-test his complaints again with a close circle of peers, gauging whether the offending issue was affecting only him.
If so, he would stand down. If not, he’d speak up to his bosses. Calmly.
“So much depends,” he says, “on how you do it.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From mud baths to herbal massages, Fiji’s heat rituals turned one winter escape into a soul-deep reset.
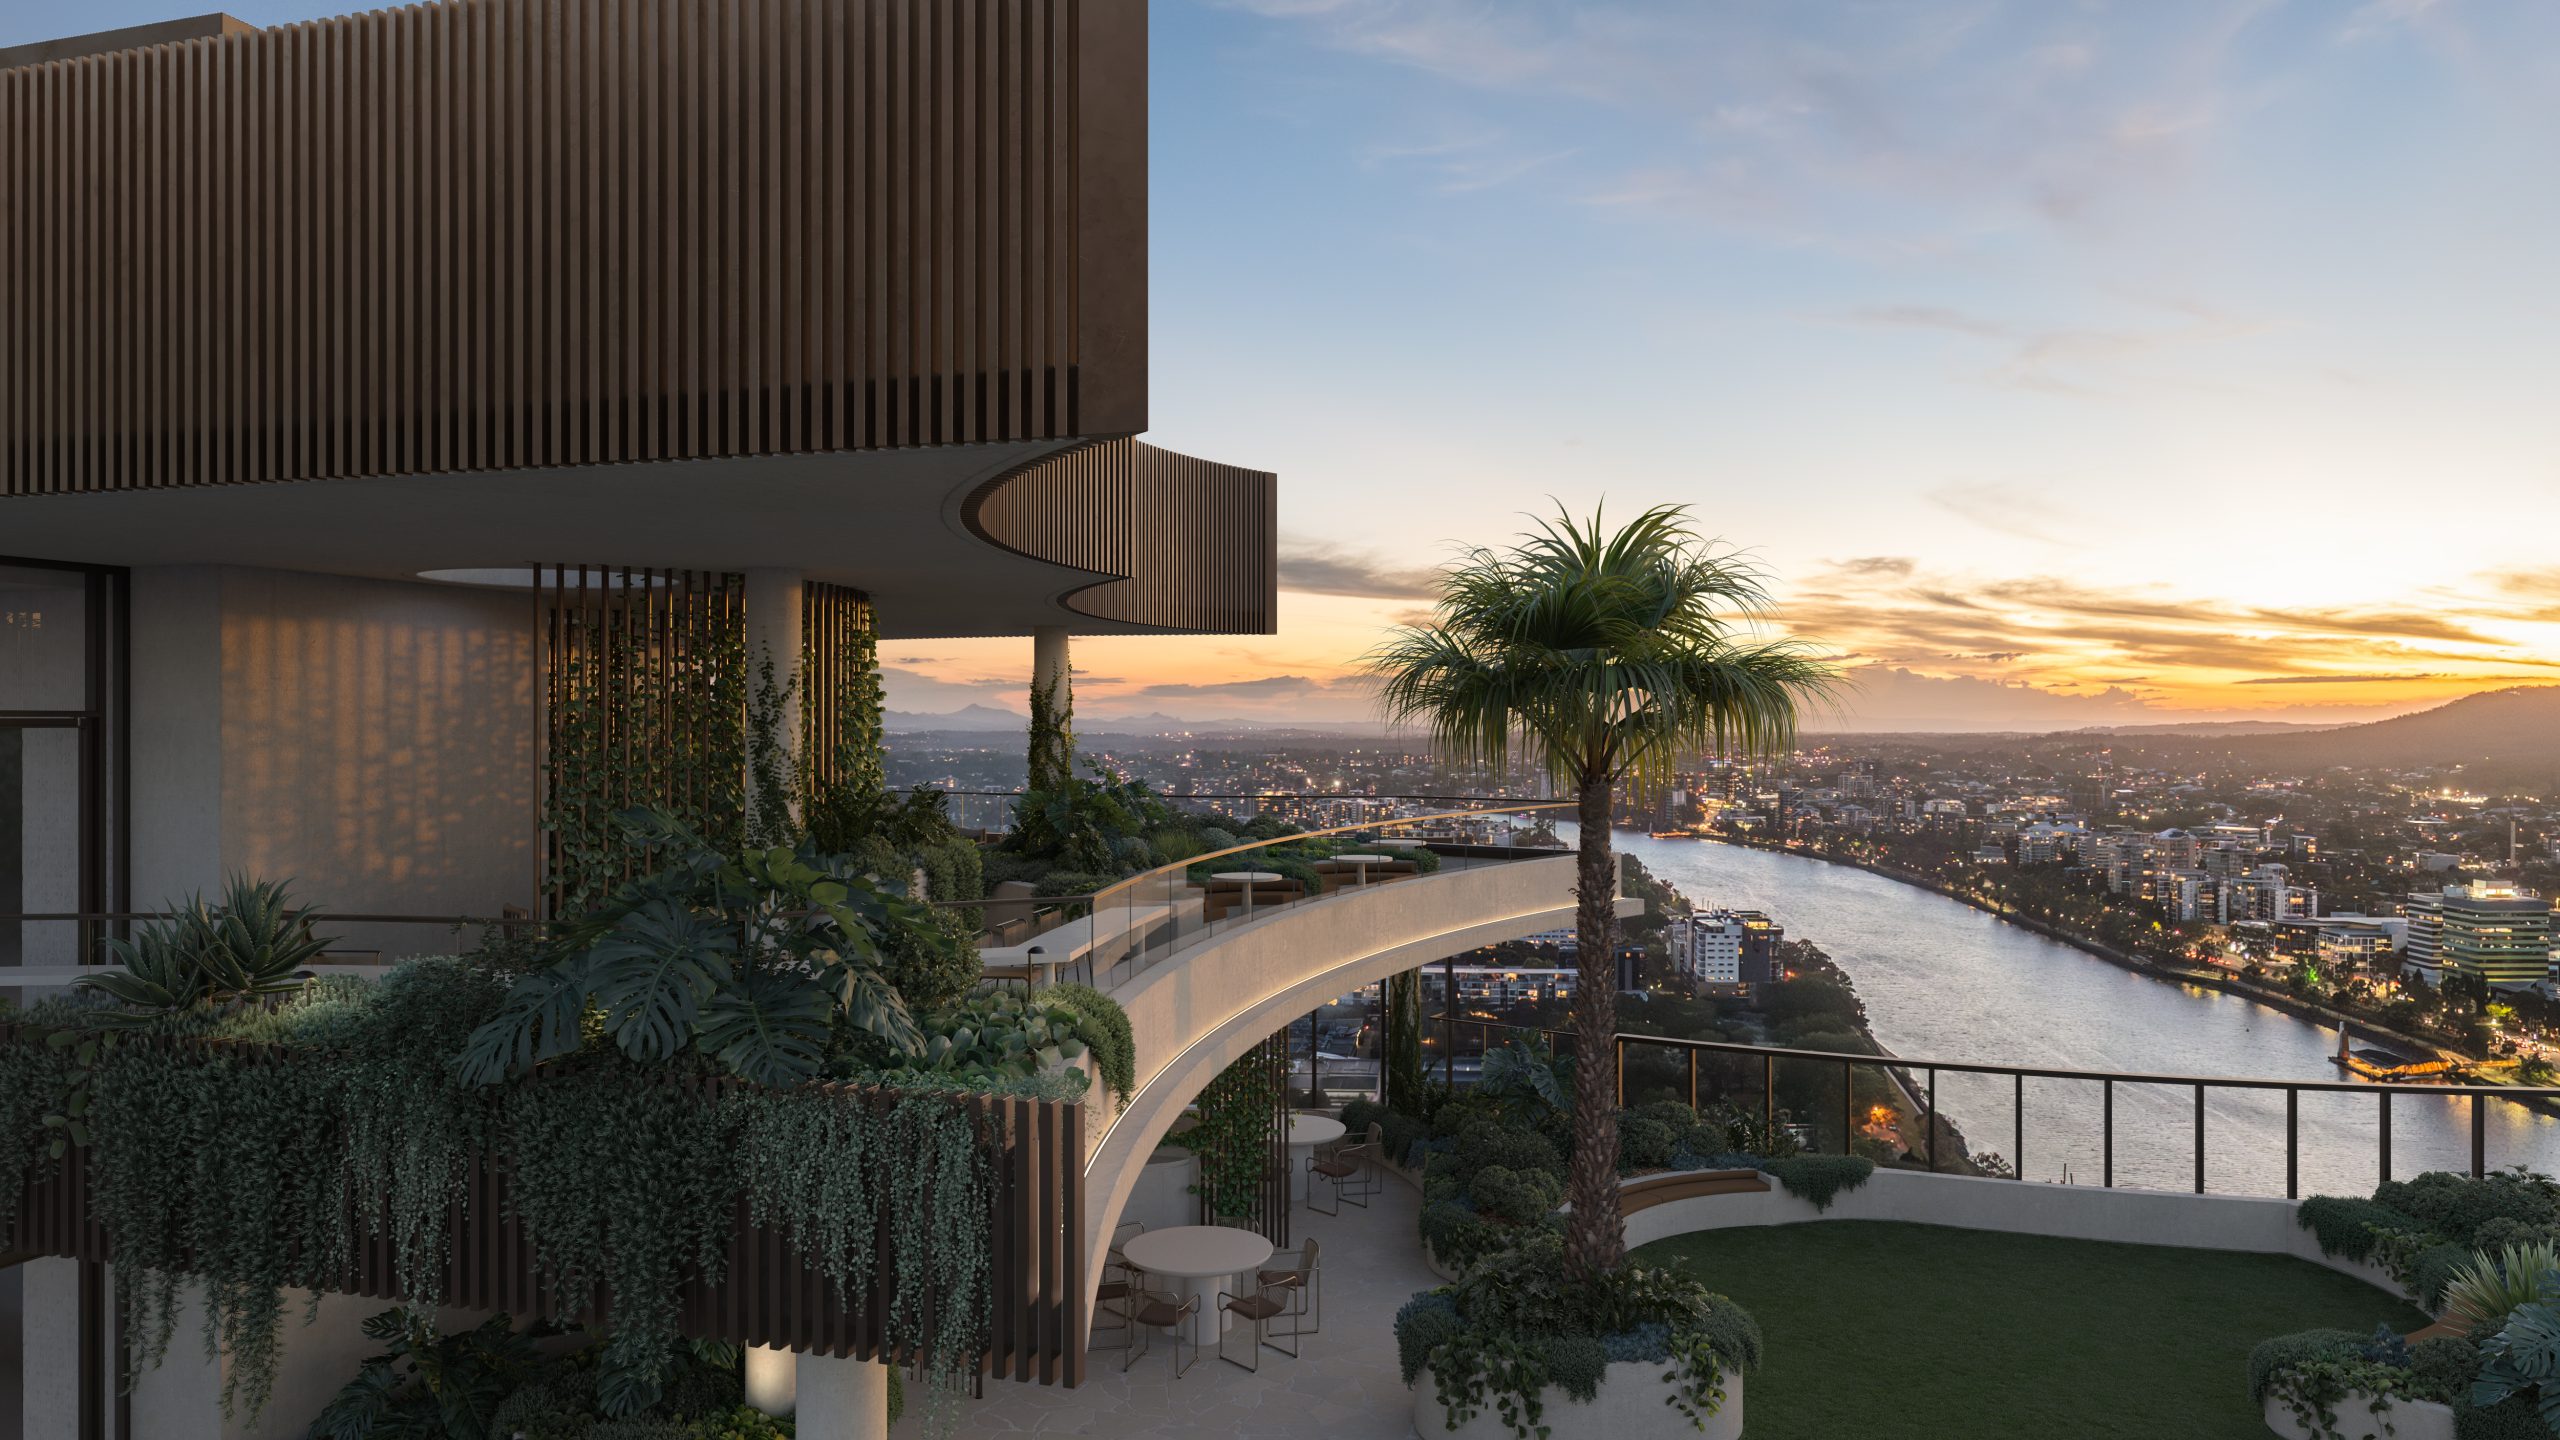
Set on one of the city’s last absolute riverfront sites, The Riversdale by Mosaic combines irreplaceable waterfront ownership with one of Brisbane’s most significant residential opportunities.