Sweden Has a Caffeinated Secret to Happiness at Work
Workers and bosses alike are trying to figure out ways to reinvigorate work life. Could a cherished Swedish coffee ritual be the answer?

 4 min
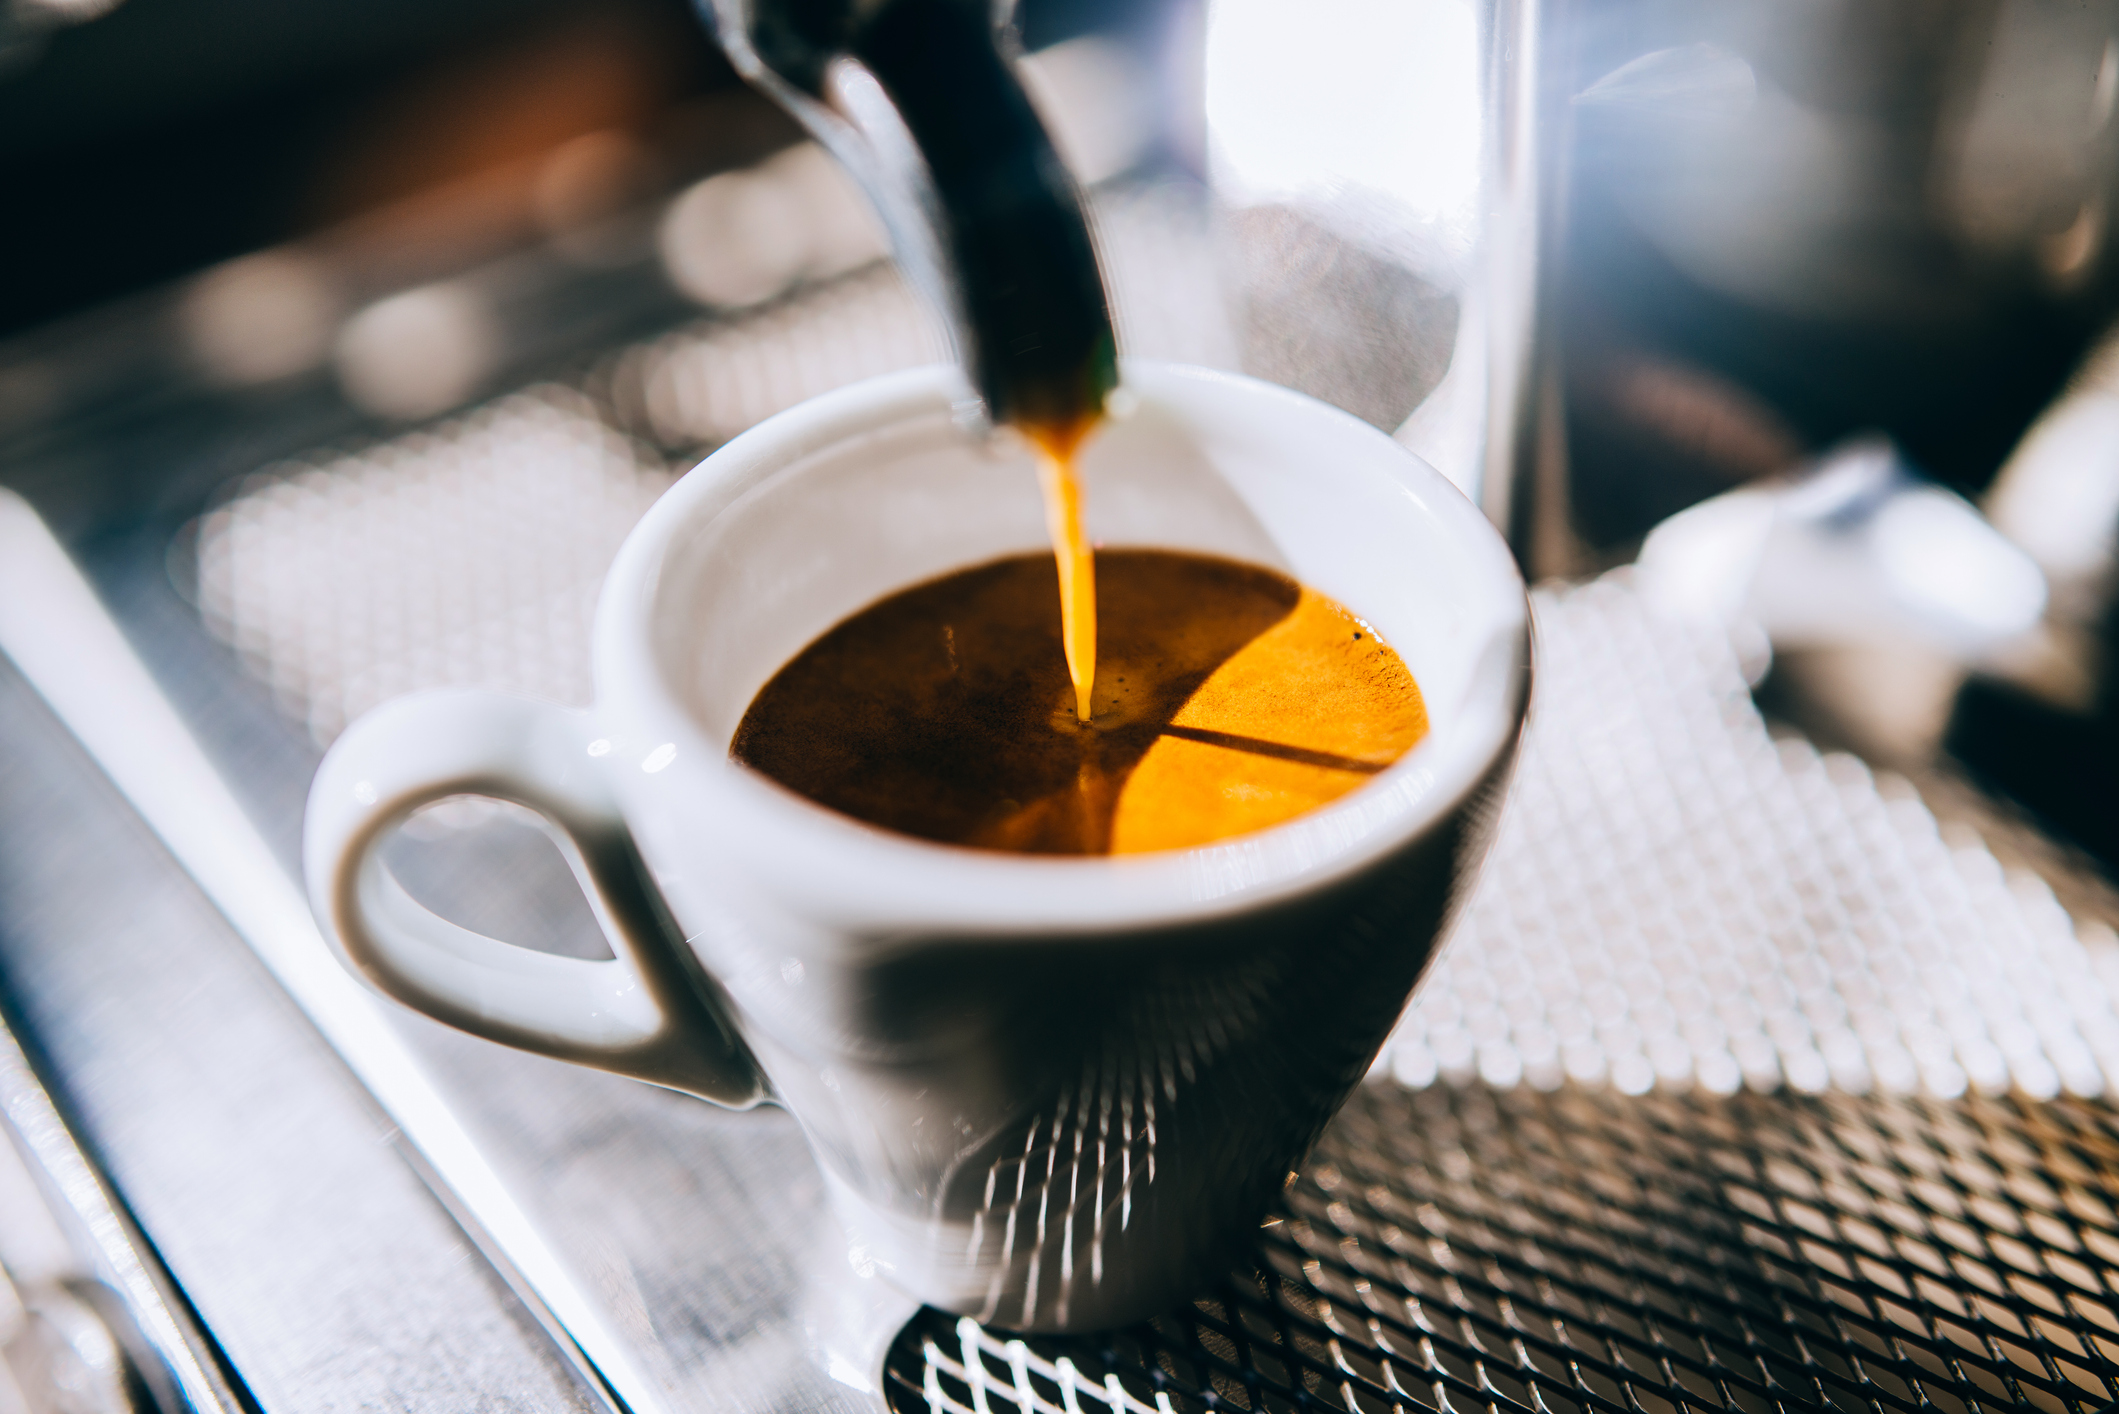
Would work be better if we all took a collective coffee break?
Workers in Sweden certainly think so. There, work life has long revolved around fika, a once- or twice-a-day ritual in which colleagues put away phones, laptops and any shoptalk to commune over coffee, pastries or other snacks. Swedish employees and their managers say the cultural tradition helps drive employee well-being, productivity and innovation by clearing the mind and fostering togetherness.
Now, as bosses and workers elsewhere try to reinvigorate office life and flagging job satisfaction, fika fascination is seeping into other workplaces.
The Grand, a New York-based career and leadership coaching platform, summons its all-remote staff of 10 every other Friday for coffee and conversation over Zoom. London-based Hubble, a website for finding flexible workspaces, took up the tradition after being introduced to it by a Swedish staff member.
“Everyone has an excuse to log off and let their hair down,” said Tushar Agarwal, chief executive of Hubble, where staff gather the last Thursday of every month for baked goods, chitchat and, of course, coffee.
A recent product offering—for part-time office space with new contract terms—sprang from a discussion that took place during fika, says chief of staff Charlie Bastier. It’s now one of the fastest-growing revenue streams, he says.
Not a Starbucks run
The pressure to make tweaks to the daily ritual is particularly acute in the U.S. Employees continue to report feeling less engaged in their jobs than in pre pandemic times, Gallup data show.
In addition, bonding with colleagues has become harder and less of a priority for many people in the hybrid world of work. Some employers worry the lack of social cohesion is harming company culture and operations.
At The Grand’s regular fika, staffers take turns hosting, leading with casual conversation or a board game such as Code Names or a drawing competition. The Grand’s co-founder Rei Wang says that fika allows her to spend time with her staff, making her a better leader.
“Learning more about their passions and their geniuses helps me understand and collaborate with them,” she says.
Pronounced “fee-kah,” the Swedish culture of breaking for coffee involves much more than a schlep to Starbucks. It’s meant to be a deliberate pause to provide space and time for people to connect. Many Swedish companies build a mandatory fika into the workday, while the Embassy of Sweden in Washington holds one for staff weekly. IKEA, promoting its Upphetta coffee maker on the corporate website, extols the virtues of fika: “When we disconnect for a short period, our productivity increases significantly.”
“Fika is where we talk life, we talk everything but work itself,” said Micael Dahlen, professor of well-being, welfare and happiness at the Stockholm School of Economics. The ritual helps drive trivsel, he says, a term that means a combination of workplace enjoyment and thriving. The concept is so fundamental to Swedish workplaces that many companies in Sweden have trivselcommittees, he said.
Dahlen said he suspects a pandemic-era drop in office fikas contributed to a sharp decline in Swedes’ happiness at work. Just over half of workers in Sweden reported a high level of job satisfaction in 2022, according to Eurostat, compared with 69.5% in 2017.
A productivity booster
There’s some evidence that communal coffee breaks help boost productivity. In a study of call centre workers at Bank of America, researchers at the Massachusetts Institute of Technology found that teams that scheduled 15-minute breaks together were 18% more communicative with one another through the workday than groups with staggered breaks.
Annual turnover, likewise, was 12% among teams that held collective coffee breaks versus 40% among other workers. In all, the teamwork fostered via the breaks led to an estimated $15 million in increased annual productivity, says lead researcher Ben Waber.
“People who are in a tight knit social group have higher levels of trust,” said Waber, who has since founded a behavioural analytics company called Humanyze.
Hubble employees take turns baking and get a stipend of about $20 for supplies for the company’s monthly fikas. Last week, 26 staff members gathered in a communal area away from desks and cubicles.
Kate Mehigan, an account manager, brought in homemade arancini balls and Eliot Dixon, an account team lead, laid out a Basque cheesecake from a recipe he’d found online. Some people played ping pong.
Fleur Sylvester, a Hubble account executive, used the time to quiz a colleague on training advice for running a half-marathon. Sylvester says when she joined the company over a year ago the gatherings were invaluable for helping put faces to names.
“You get an opportunity to speak to other team members that you don’t get to talk to on a day-to-day basis,” Sylvester said. “When you’re online you don’t get the opportunity to have those chats.”
Peter Linder, head of thought leadership in North America for Swedish telecom giant Ericsson, recently introduced the fika concept to Jason Inskeep, senior director at management consulting company Slalom. The two men had initially met on a joint panel discussion, and Linder wanted to congratulate Inskeep on his new job at Slalom. He sent Inskeep a Zoom invite for a 20-minute fika one-on-one.
“I didn’t know what it was,” Inskeep said.
The vibe of the midmorning conversation—which meandered from the future of artificial intelligence to Inskeep’s own feelings navigating a new company culture—was different from the usual business tête-à-têtehe said. Bouncing ideas back and forth in a relaxed way left him feeling energised the rest of the morning.
“It was a mix of coffee shop and barber shop,” he said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
High-end homeowners are choosing to upgrade rather than relocate, investing in bespoke design, premium finishes and long-term lifestyle value.
Limited to 630 units, Lamborghini’s latest Urus Capsule pushes personalisation further than ever, blending hybrid performance with over 70 bespoke design combinations.