





The Global Fight Against Inflation Has Turned a Corner
Falling inflation across industrialized countries opens the door for central banks to start cutting interest rates next year

 5 min
Inflation is falling faster than expected across advanced economies, marking a turning point in central banks’ two-year battle against surging prices.
Declines in consumer price growth, to below 5% in the U.K. last month and around 3% in the U.S. and eurozone, are fueling expectations that central banks could take their feet off the brakes and pivot to cutting interest rates next year.
That would provide welcome relief to a global economy that is struggling outside the U.S., increasing the prospects of a soft landing from a historic series of interest-rate increases without large increases in unemployment. Europe, in particular, is on the brink of recession.
Yields on government debt in Europe and the U.S. have slumped as investors start to price in earlier interest-rate cuts.
For months this year, economists puzzled over why growth and inflation hadn’t slowed more in response to interest-rate hikes. Now, there is growing evidence that higher borrowing costs are biting hard with a delay.
“It’s definitely a turning point for inflation,” said Stefan Gerlach, a former deputy governor of Ireland’s central bank. “Investors may be surprised at how rapidly central banks cut interest rates next year, maybe by one-and-a-half percentage point.”
The sharp declines in inflation across continents underscore how common factors drove up prices in the first place, especially the Covid-19 pandemic and Russia’s war in Ukraine. These crimped global supply chains, reduced the number of people in the workforce and fueled energy price increases, especially in Europe. As those forces subside, price pressures naturally ease.
Inflation was also given a boost by demand-side factors, such as trillions of dollars of government stimulus spending in the U.S., as well as pent-up demand and savings from consumers that accumulated during the pandemic. That, economists say, is why underlying inflation remains strong nearly four years after the start of the pandemic, and why rate increases were needed to bring it down.
Lower inflation “shows the effect of increasing rates by 4 or 5 percentage points,” Gerlach said. “Team Transitory were wrong,” he added, referring to a debate among economists over whether high inflation would subside by itself, a camp to which he belonged. “Our idea was that inflation would fall back without an increase in interest rates.”
Even countries where inflation has proved the most stubborn, such as the U.K., have started to show progress. Consumer prices rose 4.6% in October compared with the year-ago month, a drop from the 6.7% rate of inflation recorded in September and the slowest increase since October 2021, the statistics agency said Wednesday. Economists had expected to see a decline to 4.8%.
“The U.K. no longer looks like such a major outlier when it comes to inflation,” said Bruna Skarica, an economist at Morgan Stanley.
News of the U.K. decline followed Tuesday’s report of a larger than expected drop in U.S. inflation to 3.2% in October. The eurozone also reported a decline in inflation to 2.9% in October from 4.3% in September. Consumer prices were lower than a year earlier in Belgium and the Netherlands.
The cooling of consumer prices has persuaded some European policy makers that the battle to tame inflation has been won, and in a shorter period of time than in the 1970s, when a comparable surge in prices occurred.
“We’re in the process of exiting the inflationary crisis,” said France’s Bruno Le Maire before meeting with his fellow European Union finance ministers last week. “In a little under two years, Europe will have managed to control inflation, which weighs on our citizens, which weighs on households, especially the less wealthy.”
Investors are also more optimistic. They are pricing in interest-rate cuts by the Federal Reserve and European Central Bank starting next spring, and by the Bank of England next summer, according to data from Refinitiv.
Markets had priced a 30% probability of another rate increase by the Fed, from its current level of 5.25% to 5.5%, until publication of U.S. inflation data on Tuesday. That probability has now fallen to 5%, according to Deutsche Bank analysts. The prospect of a Fed rate cut by May soared from 23% on Monday to 86% by Tuesday‘s close.
Central bankers are more cautious after being surprised last year by the persistence of inflation. The Bank of England last month said it is too soon to think about cutting interest rates, having forecast that inflation would reach its 2% target in late 2025. Central bankers also point to the still-rapid rise in wages and the risk of higher energy prices if the conflict between Israel and Hamas spreads to other parts of the Middle East.
Morgan Stanley’s economists expect to see the Bank of England start to cut rates beginning next May, followed by the Federal Reserve and the European Central Bank in June. Regardless of the exact timing, there is a growing consensus that inflation is on the wane and lower interest rates will follow.
“We expect widespread declines in inflation and interest rates in 2024 across advanced economies,” Michael Saunders, a former BOE rate setter, wrote in a note to clients of Oxford Economics.
If so, it would raise the question of whether central banks overdid it with rate increases, especially in Europe.
Economists say those hikes are working their way through the economy, weighing on lending and spending. Job creation is slowing and unemployment is edging higher on both sides of the Atlantic, curbing wage growth. Households are becoming more reluctant to spend, as higher interest rates make it more advantageous to save, economists say. That weighs on growth prospects over the coming months.
U.S. retail sales fell 0.1% in October from a month earlier, the Commerce Department said Wednesday. That is the first decline since March and comes after a 0.9% increase in September. In the eurozone, industrial output declined by 1.1% in September from the previous month, official data showed on Wednesday.
The decline in inflation will be welcome news for political leaders, even if it has yet to boost their popularity.
While global factors contributed to the worst of the inflation surge and most of the recent decline, domestic economic conditions are likely to matter most as central banks enter the final stage—the so-called “last mile”—of getting inflation down to their targets of around 2%.
In the U.S., inflation is ebbing, as the labor market and consumer spending cool but remain solid. This has bolstered forecasts that price pressures will keep easing without a recession.
In Europe, the economic backdrop is more challenging. The continent faces headwinds to growth, from slowing global trade and sluggish growth in China, a critical export market, to efforts by governments to slow spending. Germany’s constitutional court on Wednesday ruled against a move by Chancellor Olaf Scholz‘s government to repurpose €60 billion in unused pandemic funds to finance green energy initiatives, creating a large hole in the state budget.
European households have also been more reluctant than their U.S. counterparts to spend pandemic-era savings. All that could lead to a deeper downturn and sharper drop in inflation in Europe, prompting earlier rate cuts by the ECB.
Despite the likelihood of lower interest rates ahead, a return to the period of ultra low interest rates that preceded the pandemic is deemed unlikely by many economists and investors, reflecting rising geopolitical tensions and demographic pressures.
Workforces are likely to shrink across major economies, including China, over the coming years as millions of baby boomers retire, driving up wages. And friction between China and the West will likely raise manufacturing costs as companies shift factories to other countries.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
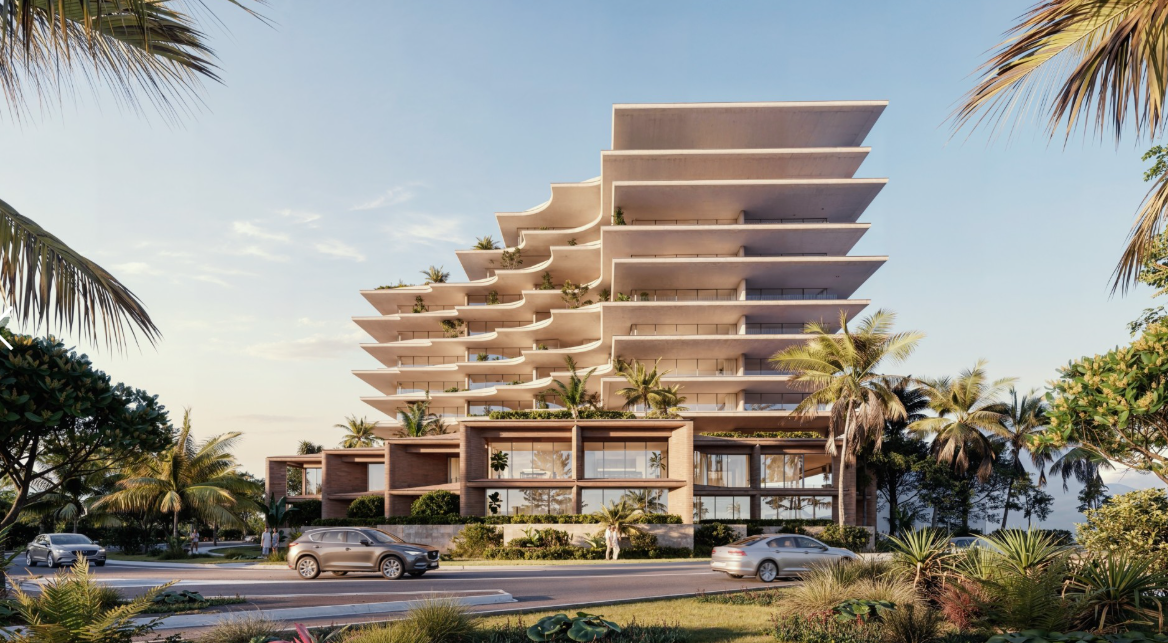
Queensland-based builder-developer MAYD has unveiled an exclusive first look at its anticipated ultra-luxury North Kirra mixed-use project as it lodges a minor amendment with the City of Gold Coast Council. The project sits across a 4,742sqm amalgamated landholding spanning seven parcels at 2–6 Pacific Parade and 27–33 Golden Four Drive, Bilinga, which MAYD secured in …
Continue reading “MAYD”s North Kirra Plans Unveiled Ahead of Early 2027 Launch”
Limited to 630 units, Lamborghini’s latest Urus Capsule pushes personalisation further than ever, blending hybrid performance with over 70 bespoke design combinations.


