What It’s Like to Retire in Istanbul
After living for 25 years in New York, a couple moved to Turkey. Despite some challenges, they are glad they did.

 4 min
In 1979, my wife and I married in Detroit and immediately moved to New York City. That was our home for 25 years—until we retired and later moved to Istanbul in 2004.
Why do we live in Turkey? Turks themselves frequently ask us, often with an air of incredulity.
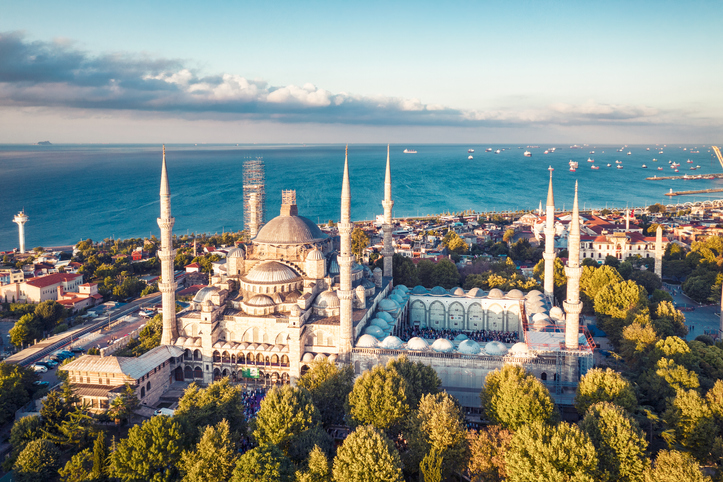
Even as a young child I was interested in history. It became my dream to live close to the centres of the Ancient World. I love that the district where we now live, on the Asian side of the Bosporus, across from Constantine’s acropolis, was once known as Chalcedon. The town appears on the 13th-century Mappa Mundi, whose reproduction hangs on our office wall.
But most important, we have found a sense of community here that seems increasingly rare in big cities of the West. In our neighbourhood, Moda, we walk almost every day—to our bakery, butcher and fruit-and-vegetable markets, to our restaurants and bank, doctors and barbers—all places where we are known and greeted. People stop us to say hello.
The neighbourhood is expensive by local standards, especially for housing. Our apartment cost $500,000 years ago, and we have spent $100,000 more on changes and renovations. Real-estate agents tell us that today we could ask $1.5 million if we were to sell. A monthly fee of less than $300 covers our heating, maintenance of the common areas, gardening, a large outdoor swimming pool and the salary and payroll taxes of the building’s live-in super.
Our large living-room windows look out on the Sea of Marmara and the western sky. This view is the main reason we bought our apartment. Often, cruise ships glide past, or a supertanker heading for the Black Sea. In the distance we can see the Hagia Sophia, a mighty edifice in both size and history. Built in the sixth century as an Orthodox cathedral, it later became a mosque, then a museum, only to become a mosque again in 2020.
We no longer own a car. If we can’t walk to it, there are taxis and other forms of public transportation. Istanbul’s funky street life is improvised, hectic and refreshingly unregulated. We love it and miss it when we travel elsewhere.
It’s a short walk along the seaside to the ferry that takes us to the European side of the city in 20 minutes. On the boat, vendors pass through with tea and juices. Where we disembark, more vendors sell roasted chestnuts, mussels with savoury stuffing, roast corn, and fish sandwiches. Old men sell lottery tickets, and fortunetellers use live rabbits to select slips of paper of the kind found in fortune cookies.
We didn’t choose Turkey seeking an inexpensive lifestyle, but it is what we were lucky to get. Because our income is in dollars, the plunging value of the Turkish lira has worked in our favour despite high inflation. The two of us can have a full meal without alcohol in a fine restaurant for about $25. Turkish cuisine is good and plentiful in our neighbourhood restaurants, but Chinese, Japanese and Italian dishes have become options, too.
It has been relatively easy to make friends with Turks and fellow expats. We have a social life that is easy and rewarding. Many of our friends are younger than us and are a great help at times—particularly in dealing with government bureaucracy.
To live as foreigners in Turkey requires a residence permit that the government renews every two years. It’s a Byzantine process—we can truly say that here—that is never the same twice and can become fraught with tension as we try to figure out and obtain the changing documentation required. At times like this, it is good to have a Turkish friend to help us.
We exercise at our local gym, where I pump iron three mornings a week and my wife, Kay, does Pilates. Healthcare has become a large issue as we’ve grown older. For some years I had private insurance equivalent to what I would have had in the U.S. Although Kay, who is eight years younger than I am, remains insured through the same company, that insurer cancelled me when I turned 75. Since then, I have paid my healthcare costs in a private hospital out of pocket. The wonder is that I’ve gotten first-class healthcare, including an important operation, for a cost we could easily afford. I’ll add that Istanbul’s private hospitals are very modern, comfortable and easy to navigate.
We feel safe here. It is a comforting thing to be able to walk through our neighbourhood, even at night, without fear. The city historically has been subject to destructive earthquakes, such as those that recently ravaged parts of southeastern Turkey and Syria. But, so far, we’ve experienced no tremors of any consequence.
The winter here is rainy and cold, but it rarely freezes. Spring and autumn are long, and there is plenty of heat in July and August.
There are, to be sure, some challenges.
Although public transportation is plentiful, it can be maddening as well. The system lacks the same convenience one finds in a city like New York.
Turkish isn’t a simple language to learn—at least for us. Partly this is the fault of our ageing brains and hearing. But I also find that Turks are prone to speak quickly.
As for shopping, while international products are more available than before, our choices are still limited. Also, many products are of a lesser quality than what we were used to in the U.S.
We have to manage our financial affairs by long distance, and this can be frustrating at times.
Finally, while the internet and email are great, we miss not seeing our friends and family in the U.S. more often.
On balance, though, we are more than satisfied with our lives here. Our travels have taken us to many countries, and we know that no place is perfect.
Retirement gives one the opportunity to discern the themes and through-lines of our lives. As I reflect on the key choices I’ve made in life, I realise that what I’ve chosen most often is a sense of freedom and a variety of experience. Our expatriate life is one of those choices.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From bushland greens to valley reds, the country’s most awarded designers are proving that the best colour palette was never on a swatch card; it was outside the window all along.
Powerhouse real estate couple Avi Khan and Kaylea Sayer welcome their daughter while balancing record-breaking careers, proving success and family can grow side by side.