Why Businesses Can’t Stop Asking for Tips
Employers far beyond restaurants rely on the practice to avoid paying higher wages; testing customer limits

 5 min
American businesses have gotten hooked on tipping.
Tip requests have spread far beyond the restaurants and bars that have long relied on them to supplement employee wages. Juice shops, appliance-repair firms and even plant stores are among the service businesses now asking customers to hand over some extra money to their workers.
“The U.S. economy is more tip-reliant than it’s ever been,” said Scheherezade Rehman, an economist and professor of international finance at George Washington University. “But there’s a growing sense that these requests are getting out of control and that corporate America is dumping the responsibility for employee pay onto the customer.”
Some businesses that are new to tipping said they have turned to the practice to try to retain workers in a competitive job market while also keeping their prices low. Asking for tips allows them to increase worker pay without raising their wages.
Consumers seeing tip prompts at every turn say they are overwhelmed—and that worker wages should be business owners’ responsibility, not theirs.
Sixteen percent of the 517 small businesses surveyed by employee-management software company Homebase for The Wall Street Journal ask customers to leave a tip at checkout, up from 6.2% in 2019.
Payroll company Paychex, which provides software for thousands of businesses in leisure, hospitality, retail and other service industries, said more employees are receiving tips as a portion of their pay than at any time since the company started tracking tipping in 2010. As of May, 6.3% of workers whose employers used the software earned tips, compared with 5.6% in 2020. The number remained relatively flat between 2016 and 2020.
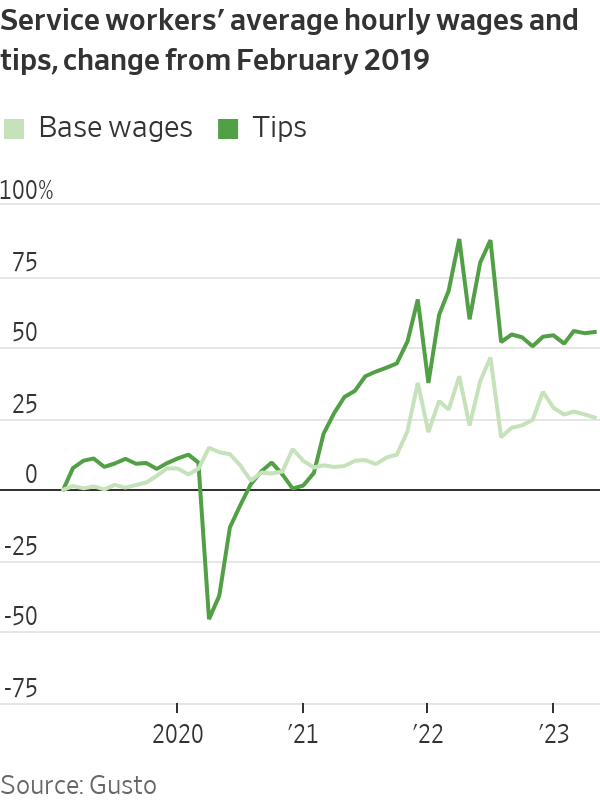
As of June, service-sector workers in non-restaurant leisure and hospitality jobs made $1.35 an hour in tips, on average, up 30% from the $1.04 an hour they made in 2019, according to an analysis of 300,000 small and midsize businesses by payroll provider Gusto.
Tips now increase wages for service workers by an average of 25%, compared with 20% between 2019 and 2020, according to Gusto. In May, the average hourly service-industry worker earned $16.64 an hour in base wages and $4.23 an hour in tips.
During pandemic lockdowns, customers of many service businesses began tipping to acknowledge workers who put themselves at risk. Rehman said that made businesses reliant on the practice. Employers with already tight margins say there’s no going back.
“With businesses still preparing for the possibility of a recession, they don’t want to lock into higher wages,” said Jonathan Morduch, a professor of public policy and economics at New York University. “Tipping gives them more flexibility.” He said the practice pushes the financial risk that employers would ordinarily shoulder onto workers.

“Businesses are happy to let workers earn more from tips, especially when there’s no pressure to raise the tipped minimum,” he said, referring to the $2.13 an hour plus tips many bar and restaurant workers across the country earn.
Holding on to workers has been especially difficult in the services sector, particularly since the pandemic. Lodging and food service have had the highest quit rate for workers since July 2021, consistently above 4.9% per three months, the U.S. Chamber of Commerce said in a May 2023 report. The quit rate for the retail trade industry isn’t far behind, around 3.3% so far in 2023. In May 2023, the overall quit rate for workers was 2.6%, according to the Bureau of Labor Statistics.
Dan Moreno, founder of Miami-based Flamingo Appliance Service, decided in 2020 to add an option for customers to tip his employees, reasoning that his home-repair technicians were taking health risks by entering customers’ homes during the pandemic.
About one-third of customers now leave a tip of between 10% and 20%, Moreno said. The requests add an average of $650 a year to his 182 technicians’ salaries, about 1% of their total yearly income.
Rising costs, he said, persuaded him to retain the option after the pandemic abated.
“You wouldn’t believe the margins we operate with,” he said. Competition for workers is fierce. Were he to eliminate the gratuity prompt, he said, he would have to raise prices beyond the 18% he already has, on average, since 2019—likely costing him clients.
He knows the requests might turn off some customers, but as the son of a repair technician and a former technician himself, he said, he tries to do as much as he can for his workers.
Within the food-service industry, tips as a share of compensation are rising faster at limited-service establishments such as bakeries and coffee shops than at full-service ones, according to Gusto.
At the Main Squeeze Juice Co. in Mandeville, La., tips add $3 to $5 to workers’ hourly pay, which starts at $10. Owner Zachary Cheaney said he added the option when he opened the location in 2020.
“We can’t just say, ‘Oh, we’re going to charge $2 extra’ instead of having tips, because we have a duty to our customers to have a very fair price point,” said Cheaney, who also consults for Main Squeeze’s corporate office. If customers think the price is too high, he said, they won’t return. Asking them to tip, he said, is different because it’s optional.
“If customers completely stopped tipping, we would be forced to pay employees more, and it would be hard on us as business operators in this crazy environment of rising costs,” he said.
The juice bar’s general manager, Tiffany Naquin, said tips make up about one-tenth of her $46,000 annual pay. Workers like tips, she said, “in all industries. It’s that little extra.” Knowing a customer will see a gratuity screen at the end motivates employees, she said. “If you give employees incentives, they are going to give you better work,” she said.
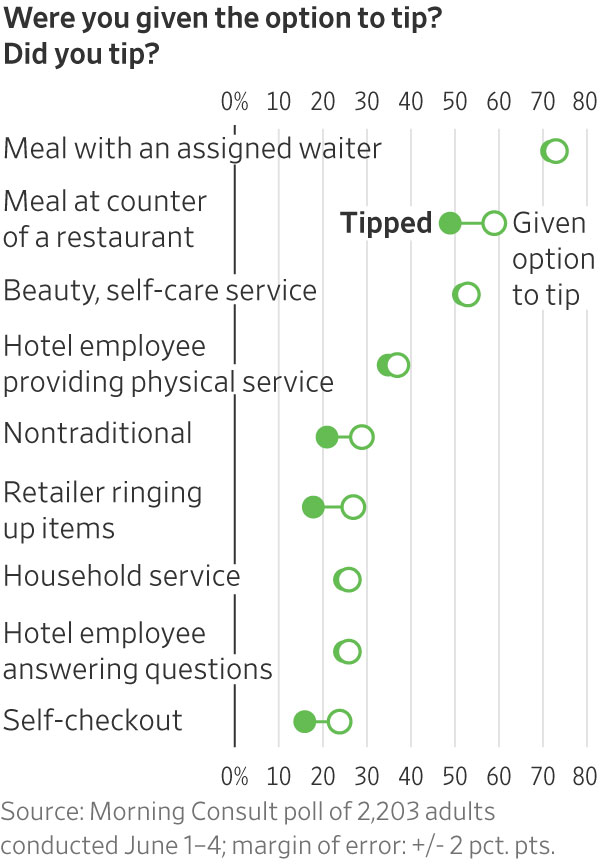
Checkouts that include a tip screen are more awkward for customers than for workers, she said. She understands if someone declines to tip, she said, and she wouldn’t let that affect the quality of service.
Morduch, the New York University economics professor, said that while most people tend to think of tips as steady income, many businesses fluctuate seasonally—which means employee pay goes up and down. Service workers who receive tips, he added, are often lower income and struggle to deal with such volatility.
Saru Jayaraman, a labor advocate and director of the Food Labor Research Center at the University of California, Berkeley, said that boosting tips without increasing base pay is bad for workers. If customers stop tipping, she said, worker pay effectively declines, which it wouldn’t if employees got a raise.
“Employers think they’re being smart by using tipping instead of raising wages,” she said. “But really they’re risking losing staff, because it’s pissing consumers off and the employees are the ones who have to deal with it.”
A May survey of about 2,400 Americans by financial services company Bankrate found that consumers are tipping less often than they did at the height of the pandemic. Forty-one percent of respondents said businesses should pay their employees better rather than rely so much on tips. Roughly a third said tipping culture is out of hand.
Denver retiree Mary Medley, though, said she sees being a generous tipper as part of her economic responsibility. For her, it isn’t about how difficult a task was, but whether she can lighten someone else’s financial burden, even a little.
“It’s not my job to figure out where it goes or how it gets distributed,” she said. “But if they’re giving me the opportunity to participate in supporting a business in a tangible way, I’ll do so.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.

Three-Michelin-starred chef Massimiliano Alajmo will host an intimate Mediterranean sailing aboard Crystal Serenity, redefining fine dining at sea.