





5:01 and Done: No One Wants to Schmooze After Work
Office happy hours, client dinners and other after-hours work gatherings lose their lustre as more people feel the pull of home

 3 min
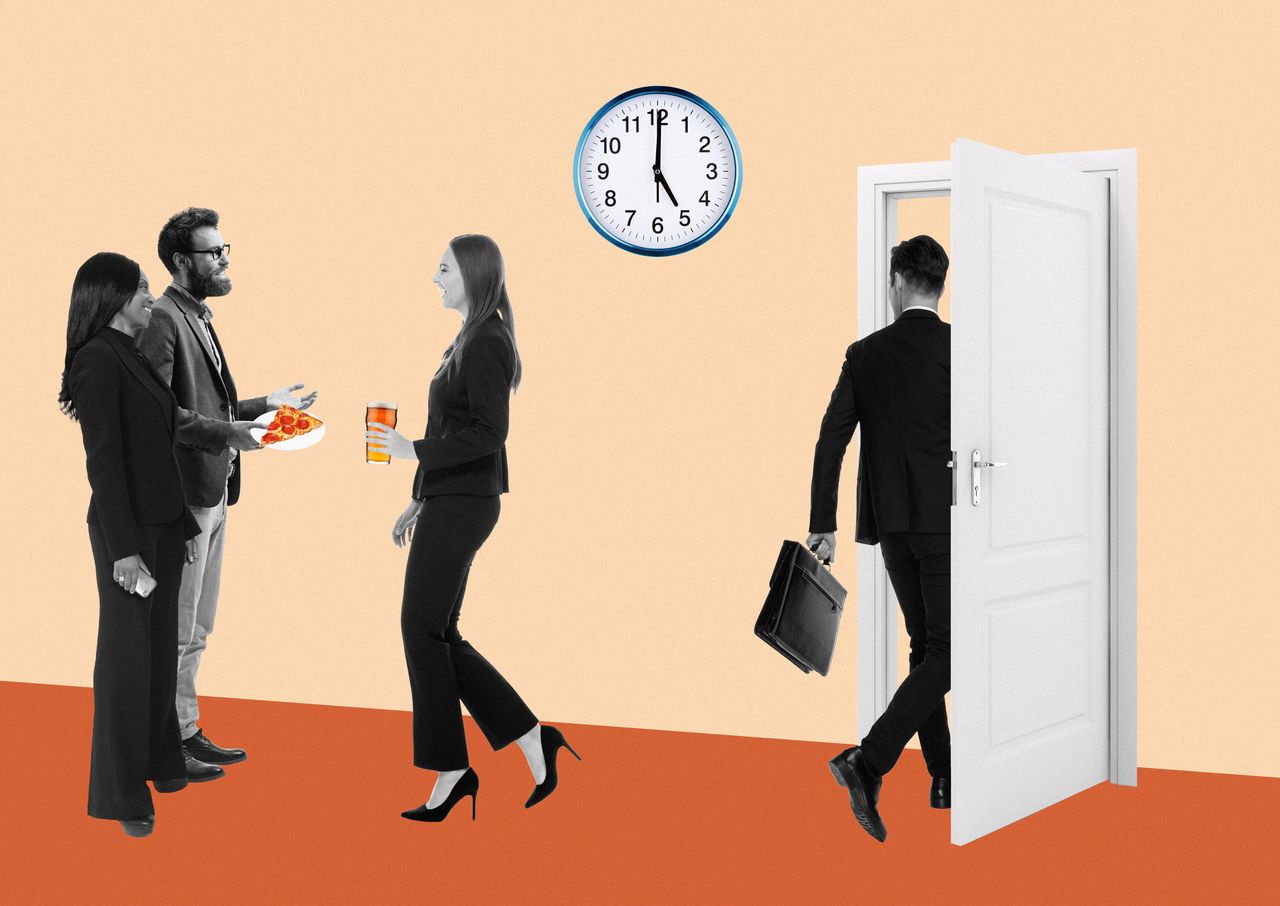
Patience for after-hours work socialising is wearing thin.
After an initial burst of post pandemic happy hours, rubber chicken dinners and mandatory office merriment, many employees are adopting a stricter 5:01-and-I’m-done attitude to their work schedules. More U.S. workers say they’re trying to draw thicker lines between work and the rest of life, and that often means clocking out and eschewing invites to socialise with co-workers. Corporate event planners say they’re already facing pushback for fall activities and any work-related functions that take place on weekends.
“The flake-out rate is so much higher at events now,” says Gretchen Goldman, a research director in Takoma Park, Md.
This summer Goldman sent an invite to 100 colleagues for casual after-work drinks at some picnic tables just outside the office as a goodbye party. She was taking a new job with the federal government. Fewer than 10 showed up.
“I guess people are just busy,” she says.
The pandemic altered eating and drinking habits, and pandemic puppies, now fully grown dogs, have to be walked on a schedule. With fewer people back in offices, there are fewer impromptu happy hours and a lack of interest in staying out late with colleagues, some bosses and workers say.
Andy Challenger oversees employees who participate in the fantasy football league at his outplacement firm, Challenger, Gray & Christmas. When some of them floated the same game plan as prior years—an in-office pizza party that goes past 11 p.m. as everybody drafts their favourite players—the pushback was swift. This season, the pizza arrived at 4:30 p.m. and everyone was finished and out of the office by 6 p.m.
“Normally that would have been the starting time,” he says.
For decades, an unspoken rule of office culture has been that much of work happens outside the 9-to-5 window. Getting ahead often requires being known outside the building and having organisational allies—the type of networking that’s helped by showing up for dinner with the boss and getting relaxed face time with co-workers at happy hours, says Jon Levy, a New York City-based consultant who advises organisations on connection and culture.
Now, even the go-getters are saying no to after-hours schmoozing opportunities.
The thinking is: “That 20th happy hour isn’t going to produce anything better for me,” Levy says.
People are less jazzed about eating out once they are home, and many got pretty good at making dinner during the pandemic, says David Portalatin, food industry adviser at Circana Group, a market research firm.
“When the consumer stretches and builds new muscles, they don’t abandon those behaviours completely,” he says.
In the past year, U.S. consumers had 264 million restaurant dinners after leaving work, which is down 43% from 2019 levels, according to Circana. And reservations are now earlier: In 2023, 26% of after-work restaurant dinners happened before 6 p.m., compared with 21% in 2019.
Barbara Martin hosts bimonthly evening soirees for clients of her marketing firm, Brand Guild. Traditionally, cocktails start flowing around 6:30 p.m. and the mingling could last until 9 o’clock—or beyond. But last Thursday she pulled the start time forward to 5:30 p.m. sharp.
“‘I’d love to come to these if you could do them earlier,’” Martin says she’s heard again and again this summer. “Nobody wants to overbook themselves until 10 p.m. on a weeknight anymore.”
Attitudes don’t appear to be changing as the summer vacation season ends. Kay Ciesla is helping organise an all-staff gathering for 80 people at the American Immigration Lawyers Association, the Washington, D.C., nonprofit where she works as a governance executive. She is considering an ax-throwing theme, and serving finger foods and cocktails.
“I’m already getting pushback,” she says of spending precious time that bleeds into personal hours on team building. Due to scheduling conflicts the group can’t gather until December. One employee voiced concern that the socialising could turn into a superspreader event ahead of Christmas travel.
Doug Quattrini, an event planner in the Philadelphia area, has already booked six Christmas parties. What’s different this year, he says, is that most are on weekdays, in the office—and end at 8 p.m.
“Nobody wants to take up people’s Fridays, Saturdays and Sundays,” says Fausto Pifferrer, co-owner of Blue Elephant Catering in Saco, Maine, near Portland, which has booked several office holiday parties for Monday through Thursday.
Younger Americans are drinking less. The share of people between 18 and 34 who said they “ever” drink alcohol has fallen to 62% from 72% two decades ago, according to Gallup data.
Caroline Wong, the chief strategy officer at Cobalt, a cybersecurity company in San Francisco, quit drinking in her early 30s and tries to plan social gatherings sans alcohol. A team off-site next month will be a tour of waterfalls near Portland, Ore. She’s noticed things wrap up earlier when there’s no drinking involved.
“It’s like, ‘You know what, we hung out for 90 minutes. We’re good and I’ll see you tomorrow,’” Wong says. “I think there’s something awesome about that.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
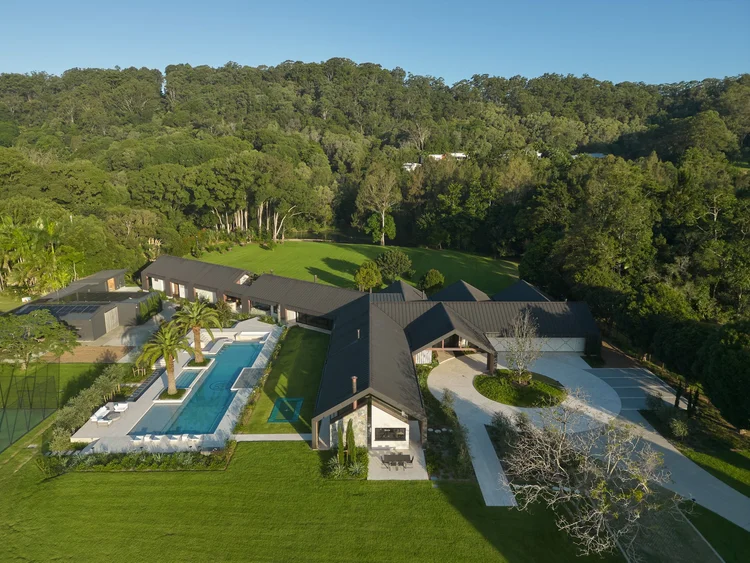
Margot Robbie may have travelled from a Queensland farm to the highest reaches of Hollywood, but a reported $28 million property deal suggests the Gold Coast has never lost its hold on her. The Australian actor and producer is believed to be the mystery buyer of Redwood, a seven-acre Currumbin Valley estate transformed into the …
Continue reading “Margot Robbie Reportedly Behind $28 Million Currumbin Valley Homecoming”

From Italian vegetable-tanned leather to real-world training insight, Australian brand PK9 Gear is redefining what luxury means for discerning dog owners.


