China’s Fading Recovery Reveals Deeper Economic Struggles
Ballooning debt, tepid consumption and worsening relations with the West to weigh on growth, economists say

 6 min
China’s era of rapid growth is over. Its recovery from zero-Covid is stalling. And now the country is facing deep, structural problems in its economy.
The outlook was better just a few months ago, after Beijing lifted its draconian Covid-19 controls, setting off a flurry of spending as people ate out and splurged on travel.
But as the sugar high of the reopening wears off, underlying problems in China’s economy that have been building for years are reasserting themselves.
The property boom and government over investment that fuelled growth for more than a decade have ended. Enormous debts are crippling households and local governments. Some families, worried about the future, are hoarding cash.
Chinese leader Xi Jinping’s crackdowns on private enterprise have discouraged risk-taking, while deteriorating relations with the West—exemplified by a new campaign against international due-diligence and consulting firms—are stifling foreign investment.
Economists say these worsening structural problems are hobbling China’s chances of extending the growth miracle that transformed it into a rival to the U.S. for global power and influence.
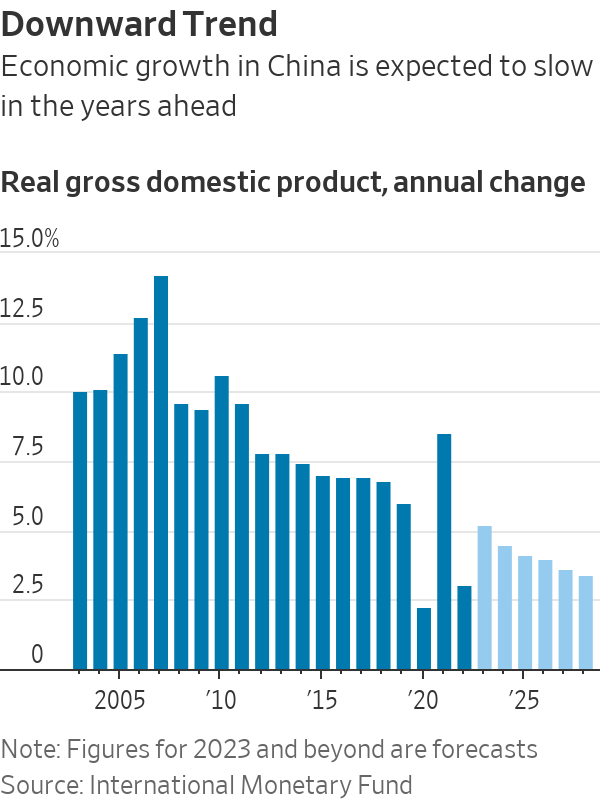
Instead of expanding at 6% to 8% a year as was common in the past, China might soon be heading toward growth of 2% or 3%, some economists say. An ageing population and shrinking workforce compound its difficulties.
China could drive less global growth this year and beyond than many business leaders expected, making the country less important for some foreign companies, and less likely to significantly surpass the U.S. as the world’s biggest economy.
“The disappointing recovery today really suggests that some of the structural drags are already in play,” said Frederic Neumann, chief Asia economist at HSBC.
China’s economy expanded at an annual rate of 4.5% in the first quarter, boosted by the end of Covid-era restrictions.
Yet more recent signals suggest the revival is ebbing. Retail sales rose 0.5% in April compared with March. A bundle of data on factory output, exports and investment came in much weaker than economists were expecting.
More than a fifth of Chinese youths aged 16 to 24 were unemployed in April. E-commerce companies Alibaba and JD.com reported lacklustre first-quarter earnings. Hong Kong’s Hang Seng Index, dominated by Chinese companies, is down 5.2% year to date, and the yuan has weakened against the U.S. dollar.
Most economists don’t expect China’s problems to lead to recession, or derail the government’s growth target of around 5% this year, which is widely seen as easily achievable given how weak the economy was last year.
McDonald’s and Starbucks have said they are opening hundreds of new restaurants in China, while retailers including Ralph Lauren are launching new stores.
A boom in electric-vehicle production allowed China to surpass Japan as the world’s largest exporter of vehicles in the first quarter. Beijing’s industrial policies and China’s manufacturing prowess mean it is still finding ways to succeed in some major industries.
“We still have confidence in the long-term growth story of China,” said Phillip Wool, head of research at Rayliant Global Advisors, an asset manager with $17 billion under management. He said the country’s transition to one that relies more on domestic consumption instead of exports will help keep it on track.
Still, many economists are growing more worried about China’s future.
The big hope for this year was that Chinese consumers would step up spending, as the main drivers of China’s past growth—investment and exports—languish.
But while people are spending somewhat more after almost three years of tough Covid-19 controls, China isn’t experiencing the kind of surge other economies enjoyed when they emerged from the pandemic.
Consumer confidence is low. More important, some economists say, is that Beijing hasn’t been able to meaningfully change Chinese consumers’ long-running propensity to save rather than spend—a response to a threadbare social-safety net that means families must sock away more for medical bills and other emergencies.
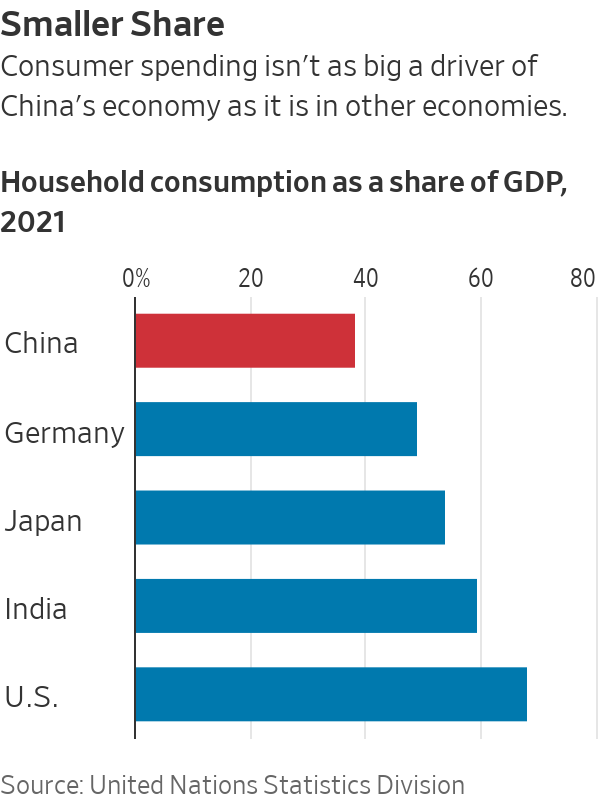
Chinese household consumption accounts for around 38% of annual gross domestic product, according to United Nations data, compared with 68% in the U.S.
“Consumer-led growth has always been a bit of an aspirational target” for China, said Louise Loo, China lead economist in Singapore at Oxford Economics, a consulting firm. Now, it might be even harder to achieve, she said, given how cautious Chinese consumers are coming out of the pandemic.
Although Beijing is trying to make it easier to borrow this year, lending data indicate households prefer to pay down debt than take on new loans.
In March, Zi Lu dipped into her dowry and paid off the remaining 1.2 million yuan, equivalent to about $170,000, on her mortgage for an apartment she bought in Shanghai two years ago. Working for an e-commerce retailer, she said sales have been underwhelming this year. Lu said she is anxious and wants to reduce her debt burden.
“I’m scared of getting laid off out of the blue,” she said.
Also looming over the economy is its massive debt pile.
Between 2012 and 2022, China’s debt grew by $37 trillion, while the U.S. added nearly $25 trillion. By June 2022, debt in China reached about $52 trillion, dwarfing outstanding debt in all other emerging markets combined, according to calculations by Nicholas Borst, director of China research at Seafarer Capital Partners.
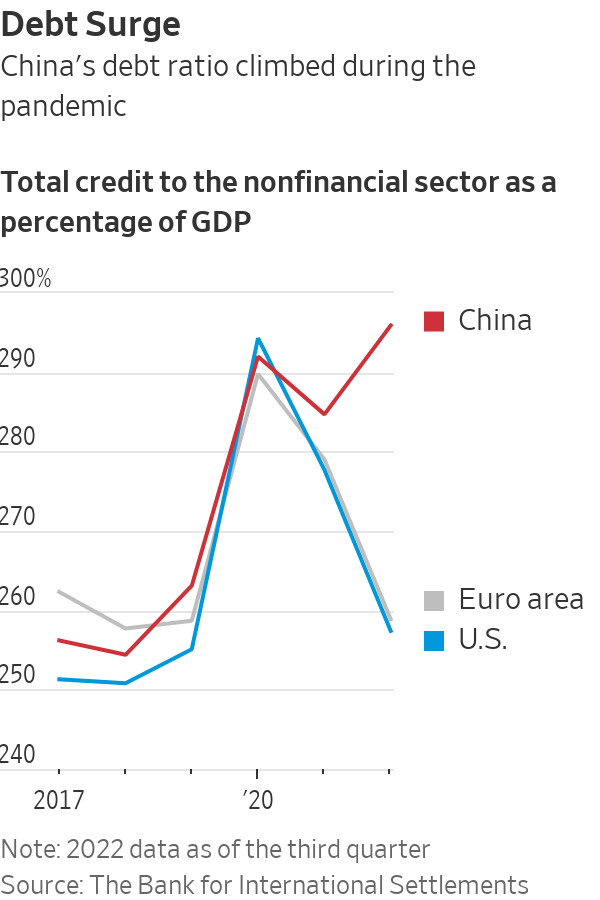
As of last September, total debt as a share of GDP hit 295% in China, compared with 257% in the U.S., data from the Bank for International Settlements shows.
Viewing the debt buildup as a threat to financial stability, Xi has made deleveraging a centrepiece of his economic policy since 2016, weighing on growth.
To help deflate the country’s housing bubble, regulators imposed strict borrowing limits for property developers from late 2020. Property development investment fell 5.8% in the first quarter of this year despite policy efforts to stem the pace of the slide.
Two-thirds of local governments are now in danger of breaching unofficial debt thresholds set by Beijing to signify severe funding stress, according to S&P Global calculations. Cities across the country from Shenzhen to Zhengzhou have cut benefits for civil servants and delayed salary payments in some cases for teachers.
These problems are deepening when China’s appeal as a destination for foreign firms is waning, data show, as tensions rise with the U.S.-led West.
Foreign direct investment into China tumbled 48% in 2022 compared with a year earlier, to $180 billion, according to Chinese data, while FDI as a share of China’s GDP has slipped to less than 2%, from more than double that a decade ago.
Competition for investment with countries including India and Vietnam is heating up as firms seek to diversify supply chains, partly in response to the risk of disruption from conflict between the U.S. and China.
Jens Eskelund, president of the European Union Chamber of Commerce in China, said uncertainty over China’s long-term economic prospects is another factor in companies’ investment decisions.
“Naturally, it dampens the willingness to go out and invest in additional capacity if you are not super optimistic about the economic outlook,” he said.
Reforms to foster more productive, private-sector activity have stalled under Xi, who is placing greater emphasis on security than economic growth. Beijing has tightened regulation of sectors including technology, private education and real estate, leaving many business owners unwilling to invest more.
In the first four months of this year, fixed-asset investment made by private firms grew 0.4% from a year earlier, compared with 5.5% growth in the same period in 2019.
Chinese leaders have dialled up rhetoric to reassure entrepreneurs and investors. Li Qiang, China’s No. 2 official and new premier, said in March that China will open further to foreign players, and told Communist Party officials to treat private entrepreneurs as “our own people.”
Economists are split over whether policy makers, who have held off on launching large-scale stimulus as they did in 2008 and 2015, will resort to more aggressive stimulus now. Some, including economists from Citigroup, expect China’s central bank to cut interest rates in the coming months to lift sentiment.
Others say that Beijing’s restraint stems from fear of compounding already-high debt levels, and that more stimulus might do little to trigger demand for credit anyway.
Jeff Bowman, chief executive of Cocona, which makes temperature-regulating materials used in apparel and bedding, said he is still optimistic about China. He said that during a recent two-week business trip to Taiwan and China, customers who were focused on China’s domestic market were far more upbeat than their counterparts exporting to the U.S. or Europe, who he said “are hurting for sure.”
He said that Cocona, based in Boulder, Colo., plans to set up a subsidiary in China to expand its business there.
But many analysts still wonder where the growth will come from.
“The big question is, have we reached the point where awareness of the structural slowdown is becoming a near-term issue for confidence? Then it’s a bit of a vicious cycle,” said Michael Hirson, head of China research at 22V Research, a New York-based consulting firm.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A&K Sanctuary unveils Kitirua Plains Lodge, a sustainability-focused luxury property shaped by landscape, local craft and contemporary safari architecture.
Porsche has revealed a one-off 911 GT2 RS that brings the extraordinary silhouette of its 935/78 “Moby Dick” racing car onto the road. Created by Porsche Sonderwunsch with Manthey, the commission began with a near-new GT2 RS. The owner requested greater performance, a Slantnose profile and a rear wing influenced by the limited 911 GT3 …
Continue reading “Porsche Builds a Road-Going “Moby Dick” From a 911 GT2 RS”