Don’t Be a Jerk at Work. (But Don’t Be Too Nice, Either.)
How devolving into people-pleasing can hold back your career

 4 min
How nice should you be at work?
We’ve supposedly moved on from the era of the militaristic chief executive who barks orders and threats. Most of us agree: We don’t like jerks. Be kind, we implore our kids.
Then we get to the office. We’ve got direct reports to rally, colleagues in other departments to convince and bosses who claim they want honest feedback. Speak with hesitation and you’re ignored. Handle your team with kid gloves and you’re a pushover, not a force to be reckoned with.
“I, personally, think you’re too nice a person to be in the job that you’re in.” That’s what Rep. Greg Murphy (R., N.C.) told Katherine Tai, the lead trade negotiator for the U.S., this spring during a hearing. His comments summed up feedback so many of us, especially women, have heard. We’re too bubbly or kind. We deploy too many apologies or exclamation marks. Yet when we do too little of all that, we’re overly aggressive.
“I want to be a nice person,” Sarah Kleinberg, the director of operations at a healthcare consulting firm, told me. She has realised, though, that being nice often makes others feel good, without actually moving a project forward or prompting a team member to improve.
“You have to have the level of confidence to be beyond people-pleasing,” she says.
‘Customer-service voice’
Many people, desperate not to offend, resort to what speaking coach Samara Bay calls “customer-service voice.” It’s that high-pitched, upspeak-y tone meant to inform the barista, I think you might be out of oat milk?
What are we saying when we use that tone? “I’m not powerful, don’t worry,” Bay says.
Making yourself non intimidating and as small as possible might work earlier in careers, she adds, making the people in charge feel secure. But as we ascend, or try to, the wavering voices can confuse others. Do it enough and people might question whether you’re leadership material, Bay says.
She recommends a vocal exercise for speaking more confidently. Pretend that you’re introducing yourself—“Hi, my name is Rachel”—while throwing a pretend ball against the wall. Match your vocal pitch to the ball’s trajectory. When you throw the ball down to the ground, you’ll hear your voice droop in energy along with the ball. Then throw the ball up, and notice the way your words sound as if you’re half taking them back. Last, throw the ball straight and allow your words to follow through, too.
“It’s the weirdest feeling to say something and mean it all the way to the end,” Bay says. “It feels brave.”
No hedging allowed
When pitching an idea, don’t undercut yourself with hedging language, says Bob Bordone, a negotiations coach. He cringes at questions like: “Would you be willing to consider letting me work remotely on Fridays?”
“It makes me just want to say no because it’s such a weak thing,” he says.
Instead, he says, start with a statement: “I wanted to talk to you about working out a new schedule.” Assure that any agreement you come to would be good for your manager and the company.
When someone tells you no, Bordone suggests trying: “How can we tackle this, even though we see it differently?” You sound strong and assertive, but not nasty, he says.
Good news for the nice guys among us: You don’t have to give up your personality to be taken seriously.
“I’m, 99.9% of the time, a jovial, happy-go-lucky guy,” says Colton Schweitzer, a user-experience designer and educator in Vancouver, Wash. When he doesn’t like the direction a project is going, he pushes back by asking questions and inserting the occasional joke.
“I’m smiling,” he says, “Even when I’m saying, ‘Are you sure about that?’”
Because he’s so pleasant, his serious moments carry weight. At one job, he cheerfully took on more work when colleagues asked—until his manager asked him to pick up the slack for an underperforming employee. He gave a resolute no. His manager dropped the issue, and seemed surprised and impressed by his response, he says.
“It’s like a currency,” he says of invoking a more stern style. “When I use it, it’s really valuable.”
Less yelling, more intensity
To be tough but not jerky, set clear expectations, says Harry Kraemer, a professor of leadership at Northwestern University’s Kellogg School of Management.
Before teaching, Kraemer rose to be chief executive of Baxter International, the healthcare company where he worked for 25 years. As a new manager, he would try to be everyone’s breezy friend, shrugging it off when his team turned in a project hours past deadline. The second time it happened, he devolved into yelling, only to realise he hadn’t made the stakes clear from the start.
“If I focus on being liked, the chance of being respected is very low,” he says.
He adopted a new leadership style of, “I’m not going to surprise you.” He says the yelling just made him look out of control, but following through with consequences worked. When his team missed sales targets, he gathered them for a two-hour debrief—no smiling, his voice intense.
“I don’t need a sorry,” he would tell them. “Hit the number. Do what you told me you were going to do.”
Dinah Davis, a Realtor in Highlands, N.C., still remembers advice an old friend gave her years ago on the golf course. The friend was a skilled neurosurgeon known for being direct, not touchy-feely.
“I have a great bedside manner,” she told Davis. “I just don’t have time for it.”
The advice was freeing for Davis, a former lawyer more comfortable with staunch negotiations than chirpy small talk.
“Do you want your pilot to be nice?” Davis asks. “Or do you want your pilot to get the plane on the ground?”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices
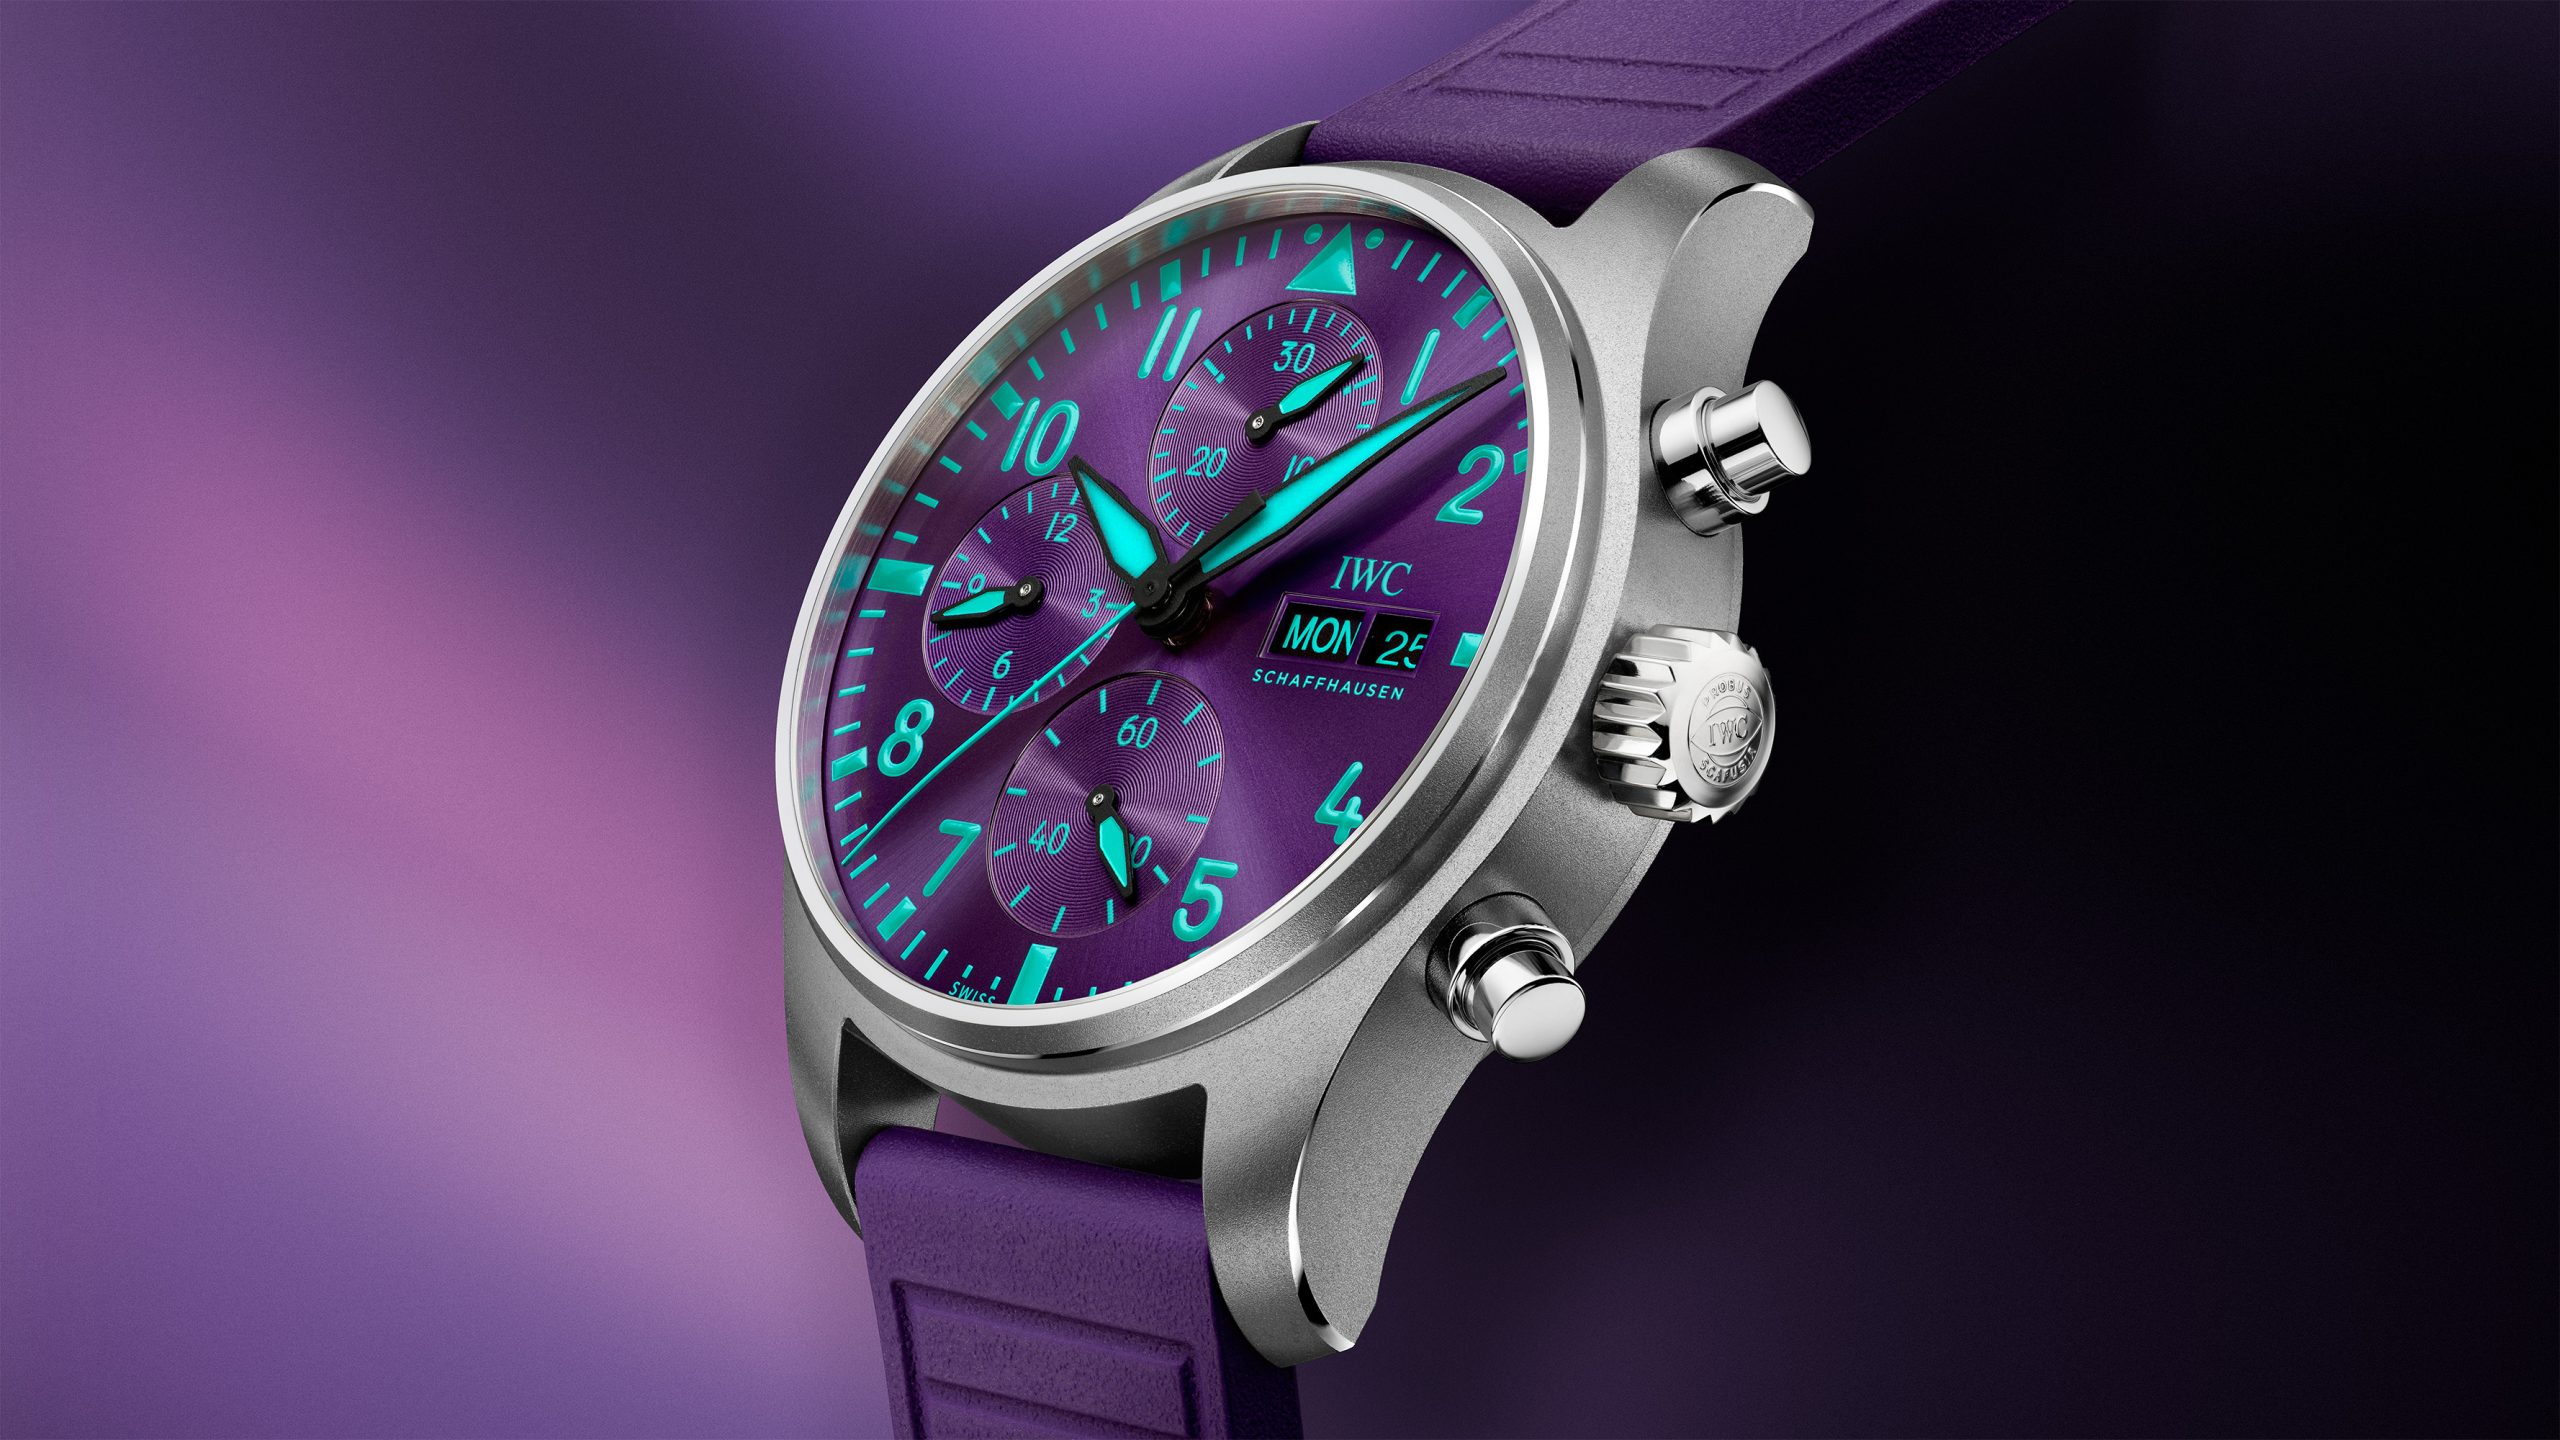
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”
Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.
3 min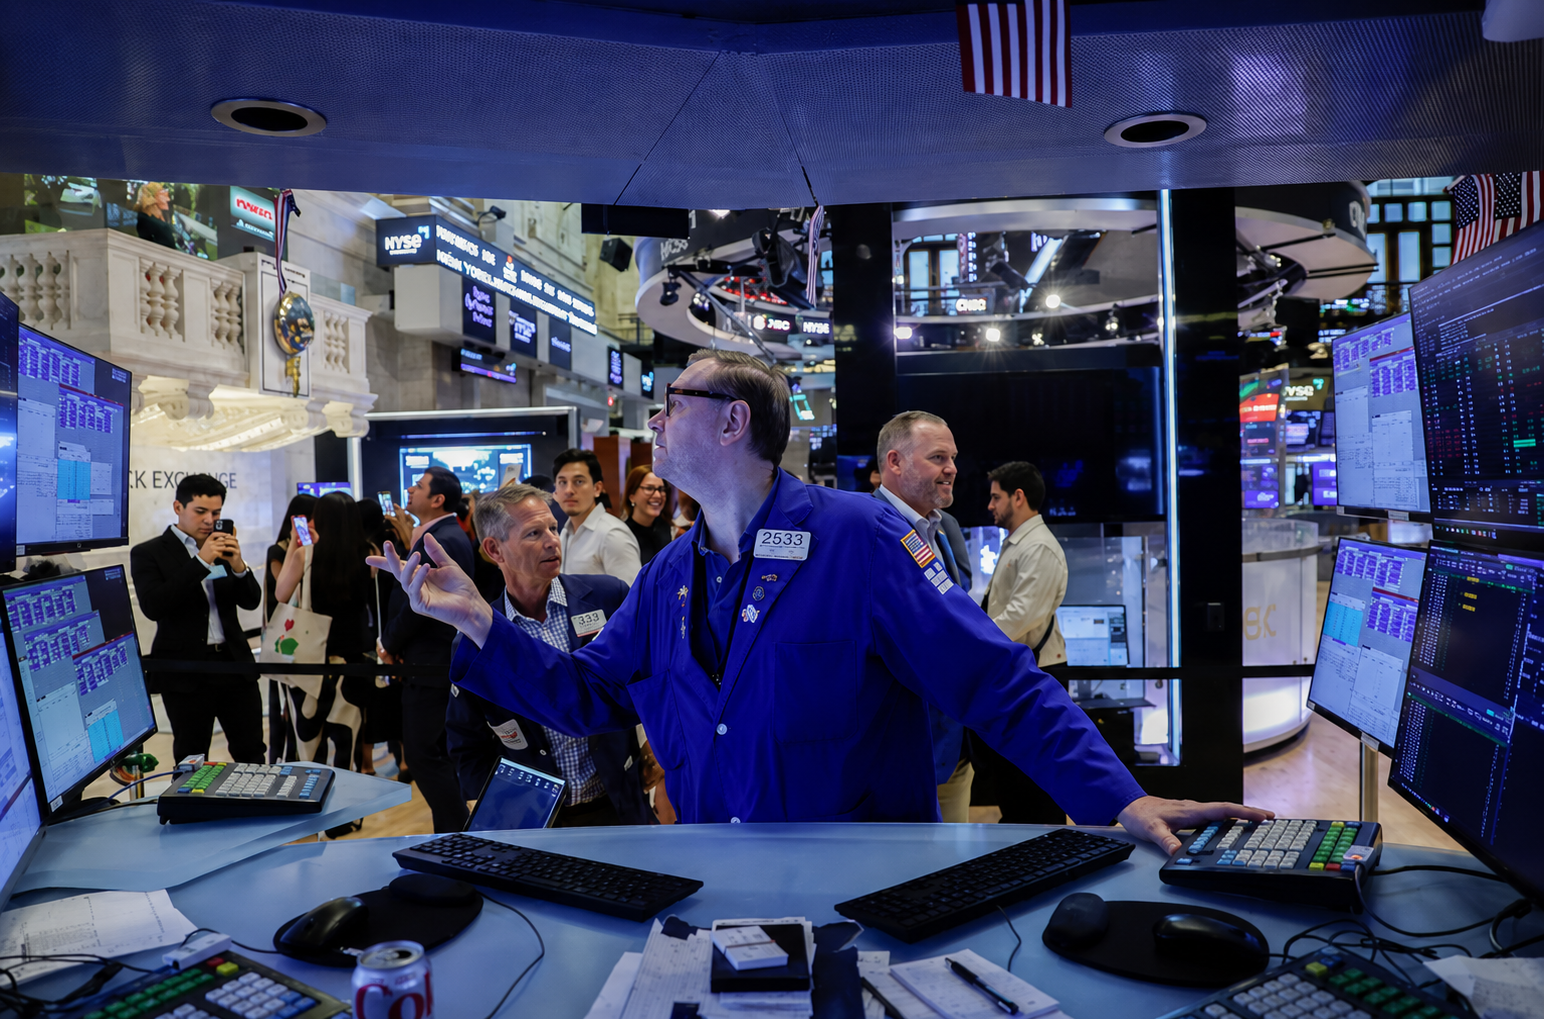
Wall Street’s hottest trade has gone ice cold.
For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron Technology, Nvidia, Advanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.
The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.
Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.
“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.
Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.
Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.
Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.
“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.
Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.
“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”
Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.
Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”
The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.
The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.
These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.
Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.
The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.
Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.
Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.
And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.
“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.
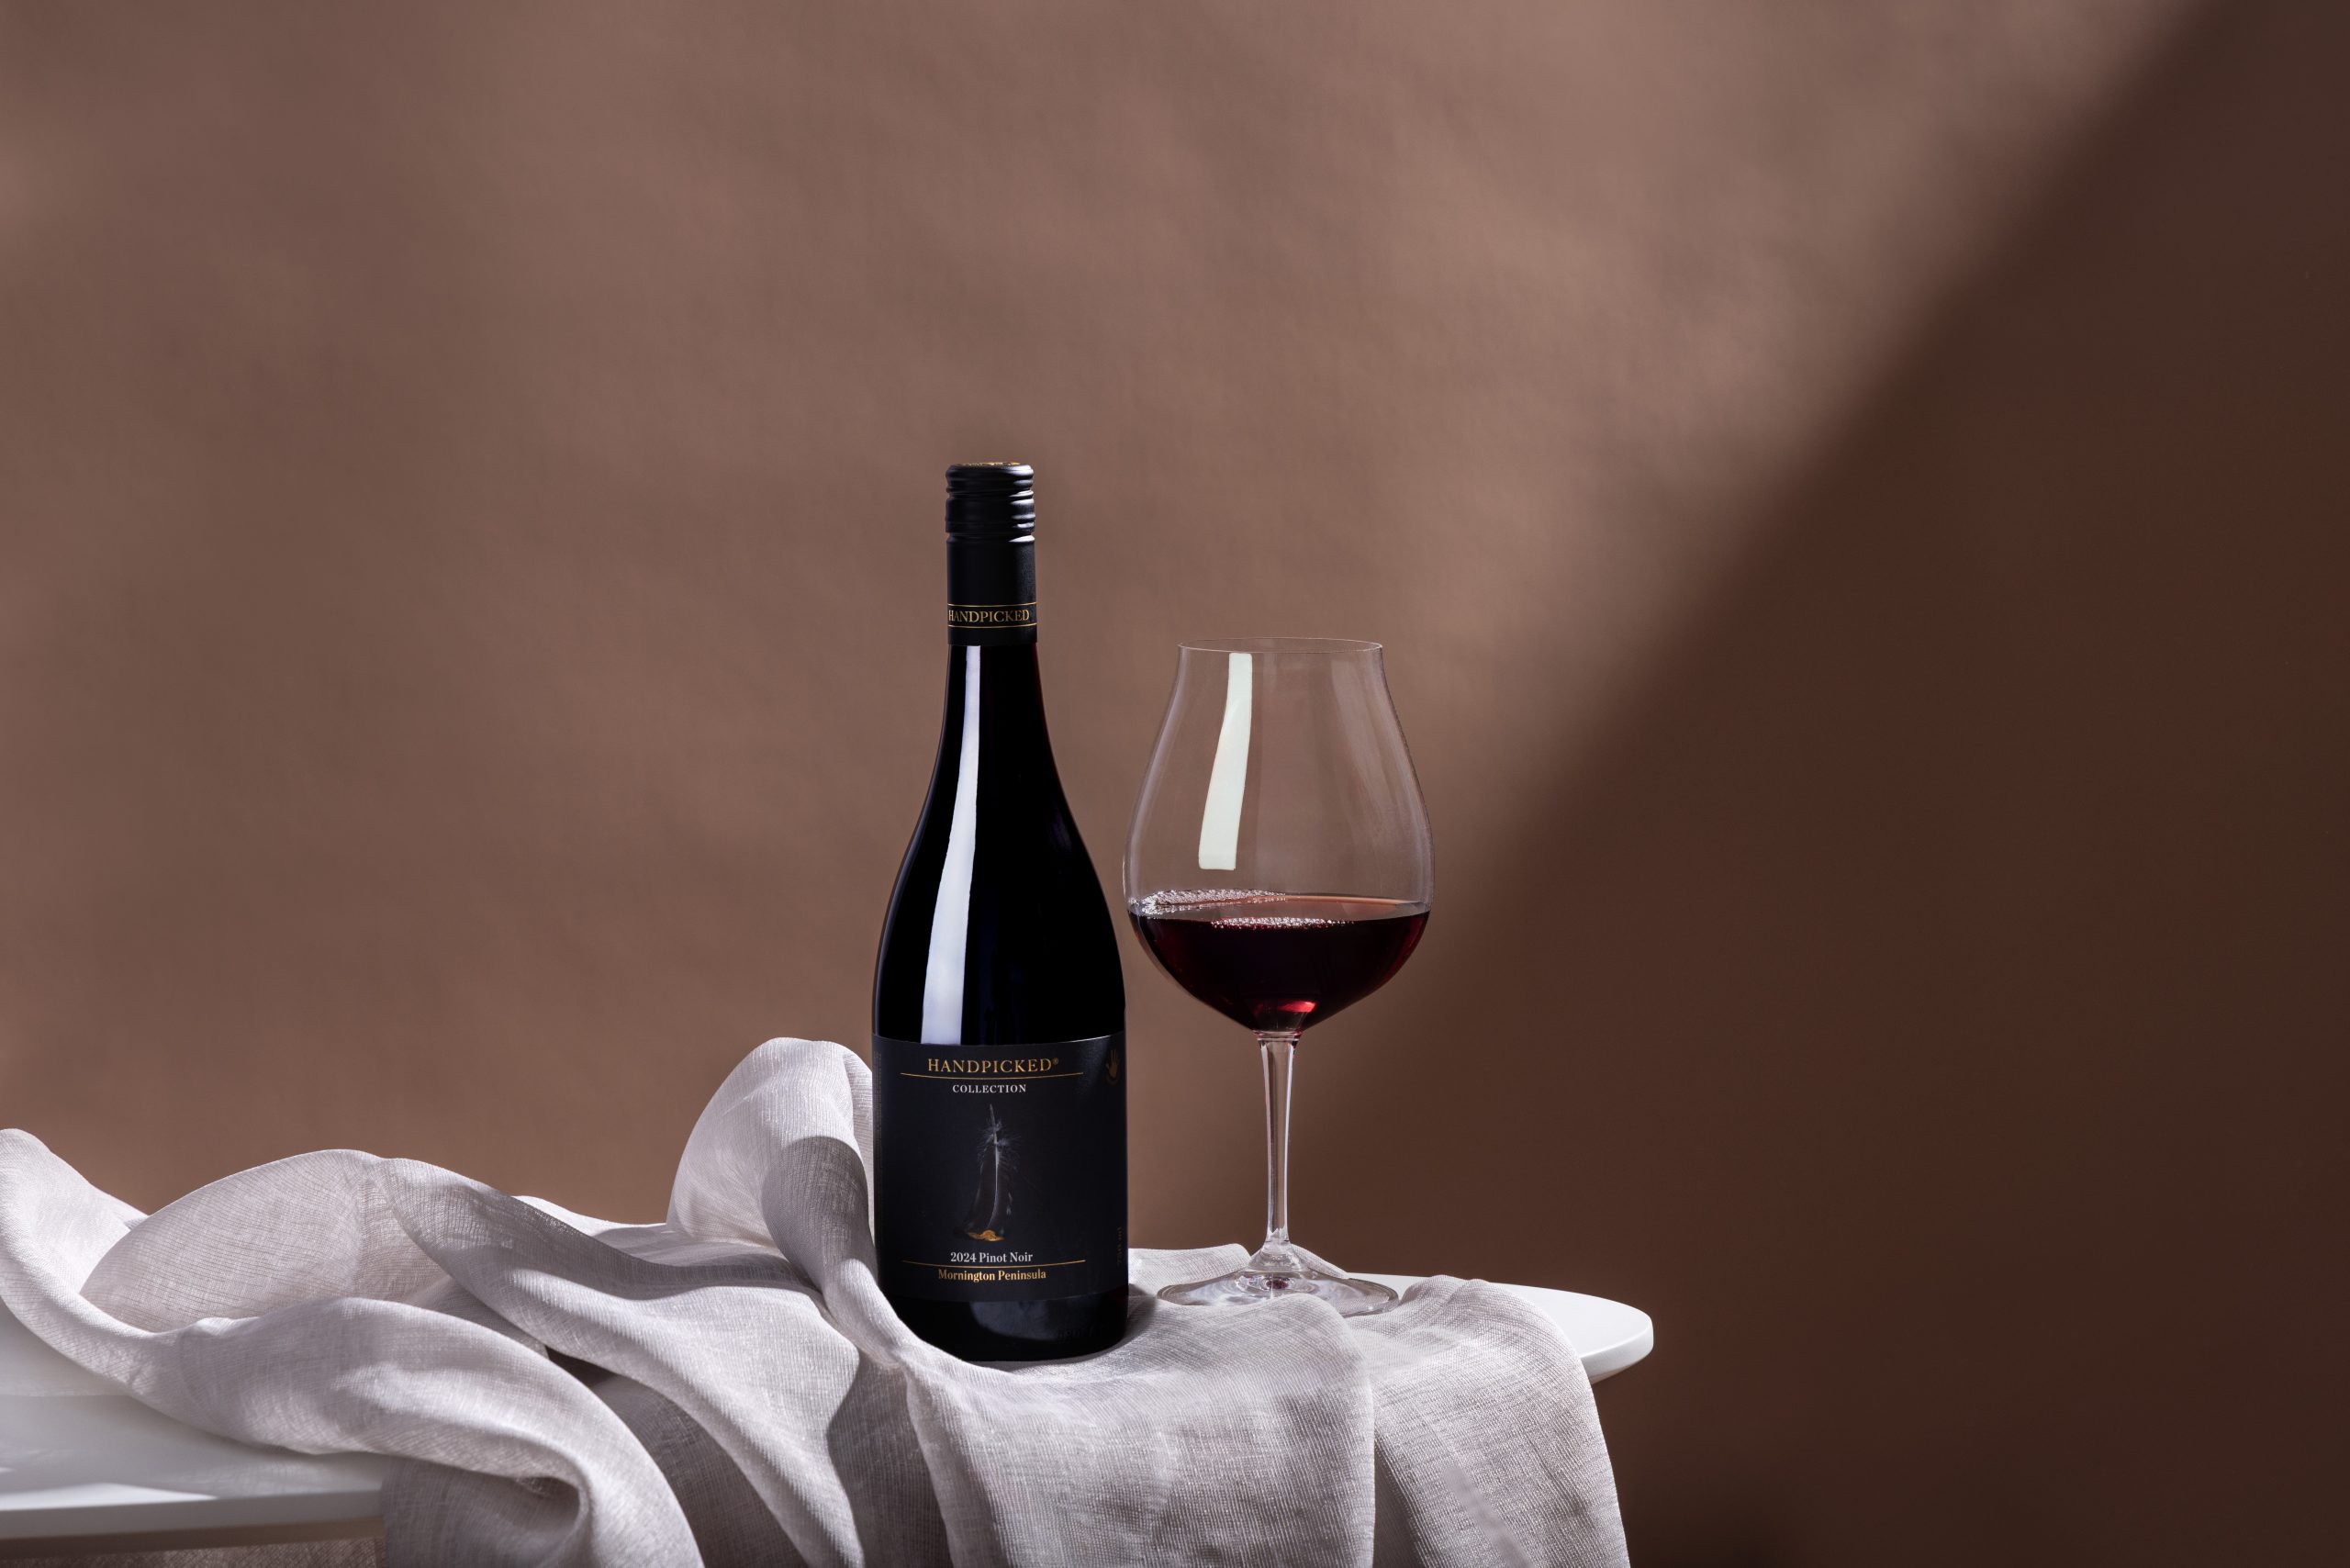
As the season turns, Handpicked Wines’ latest Pinot Noir and Chardonnay releases reveal how subtle shifts in place shape what ends up in the glass.