

Gold Is Beating Everything. How to Get a Piece of the Action
Gold is outshining stocks, bonds and crypto. Here’s what’s driving the surge—and how to get in.

 8 min

Give gold bugs their due. The yellow metal has been a light in the investing darkness. At a recent $3,406 per troy ounce, it’s up 30% this year, to the envy of stock, bond, and Bitcoin holders. Cash-flow purists will call this a flash in the pan, but they should look again. Over the past 20 years, SPDR Gold Shares , an exchange-traded fund, has surged 630%—85 points more than SPDR S&P 500 , which tracks shares of the biggest U.S. companies.
That isn’t supposed to happen. If businesses couldn’t be expected to outperform an unthinking metal over decades, shareholders would demand that they cease operations and hoard bullion instead. So, what’s going on? If this were gasoline or Nike shoes or Nvidia chips, we would look to supply versus demand. With immutable gold, nearly every ounce that has ever been found is still around somewhere, so price action is mostly about demand. That has been ravenous and broad since 2022.
That year, the U.S. and dozens of allies placed sweeping sanctions on Russia, including its largest banks, and China went on a bullion spree. Its buying has since cooled, but other central banks have stepped in. Perhaps this is unsurprising, in light of a decades-long diversification by finance ministers away from the U.S. dollar, which is down to 57% of foreign reserves from over 70% in 2000. But the recent uptick in gold stockpiling looks to JPMorgan Chase , the world’s largest bullion dealer, like a debasement trade. Investors are nervous about President Donald Trump’s tariffs, his browbeating of the Federal Reserve Chairman over interest rates, and blowout U.S. deficits.
Surging Demand
It isn’t just bankers. Demand among individuals for gold bars and coins has been surging, with some dealers experiencing sporadic shortages. Gold ETFs were bucking the trend, but flows there have turned solidly positive since last summer, including recently in China. All told, there is now an estimated $4 trillion worth of gold held by central banks, and $5 trillion by private investors. Calculated against $260 trillion for all financial assets, including stocks, bonds, cash, and alternatives, that works out to a global gold portfolio allocation of 3.5%, a record.
What’s next? BofA Securities says that central banks have room for much more gold buying, and that China’s insurance companies are likely to dabble, too. RBC Capital Markets analyst Chris Louney says ETFs could drive demand growth from here, especially if angst reigns. “Gold is that asset of last resort…the part of the investing universe that investors really look for when they have a lot of questions elsewhere,” he says.
Russ Koesterich, a portfolio manager for BlackRock , a major player in ETFs including the iShares Gold Trust , says that gold has proven itself as a store of value, and deserves a 2% to 4% weighting for most investors. “I think it’s a tough call to say, ‘Would you chase it here?’ ” he says. “There have been some pullbacks. Those might represent a good opportunity, particularly for people who don’t have any exposure.”
Daniel Major, who covers materials stocks for UBS , points out that gold miners mostly haven’t wrapped themselves in glory in recent years with their dealmaking and asset management. As a result, a major index for the group is trading 30% below pre-Covid levels relative to earnings. UBS increased its 2026 gold price target by 23%, to $3,500 per troy ounce, before gold’s latest lurch higher. Many miners are producing at a cost of $1,200 to $2,000. Major has bumped up earnings estimates across his coverage. “I think we’re gonna see further upward revisions to consensus earnings,” he says. “This is what’s attractive about the gold space right now.”
Major’s favorite gold stocks are Barrick Gold , Newmont , and Endeavour Mining . More on those in a moment. We also have thoughts on how not to buy gold—and what not to expect it to do: Don’t count on it to keep beating stocks long term, or to provide precise short-term protection from inflation spikes and stock swoons. But first, a little history, chemistry, and rules of the yellow brick road.
Flesh of the Gods
The first gold coins of reliable weight and purity featured a lion and bull stamped on the face, and were minted at the order of King Croesus of Lydia, in modern-day Turkey, around 550 B.C. But by then, gold had been used as a show of riches for thousands of years. Ancient Egyptians called gold the flesh of the gods, and laid the boy King Tutankhamen to rest in a gold coffin weighing 243 pounds. The Old Testament says that under King Solomon, gold in Jerusalem was as common as stone. Allow for literary license; silicon, an element in most stones, is 28.2% of the Earth’s crust, whereas gold is 0.0000004%.
Marco Polo described palace walls in China covered with gold. Mansa Musa I of Mali in West Africa, on a pilgrimage to Mecca in 1324, is said to have splashed so much gold around Cairo on the way that he crashed the local price by 20%, and it took 12 years to recover. To Montezuma, the Aztec king whose gold lured Cortés from Spain, the metal was called, as it still is by some in Central Mexico, teocuitlatl —literally, god excrement. Golden eras, gold medals, the Golden Rule, and golden calf—so deep is the historical association between gold and wealth, excellence, and vice that it seems to have a mystical hold on humanity. In fact, it’s more a matter of chemical inevitability.
Trade and savings are easier with money. Pick one for the job from the 118 known elements. Years ago on National Public Radio, Columbia University chemist Sanat Kumar used a process of elimination. Best to avoid elements that are cumbersome gases or liquids at room temperature. Stay away from the highly reactive columns I and II on the periodic table—we can’t have lithium ducats bursting into flame. Money should be rare, unlike zinc, which pennies are made from, but not too rare, unlike iridium, used for aircraft spark plugs. It shouldn’t be poisonous like arsenic or radioactive like radium—that rules out more elements than you might think. Of the handful that are left, eliminate any that weren’t discovered until recent centuries, or whose melting points were too high for early furnaces.
That leaves silver and gold. Silver tarnishes, but rarer, noble gold holds its luster. It is malleable enough to pound into sheets so thin that light will shine through. And, despite the best efforts of Isaac Newton and other would-be alchemists, it cannot be artificially created—profitably, anyhow. Technically, there is something called nuclear transmutation. If you can free a proton from mercury’s nucleus or insert one into platinum’s, you’ll end up with a nucleus with 79 protons, and that’s gold. Scientists did just that more than 80 years ago using mercury and a particle accelerator. But what little gold they produced was radioactive. If you think you can do better, you’ll likely need a nuclear reactor to prove it, but a large gold mine is one-fifth the cost, and we have to believe the permitting is easier.
We passed over copper due to commonness, but it has become too valuable to use for pennies. The 95% copper content of a pre-1982 penny is worth about three cents today. The equivalent amount of silver goes for $3.10, and gold, more than $320. But the three trade in different units. A pound of copper is up 17% this year, at $4.72. Silver and gold are typically quoted per troy ounce, a measure of hazy origin and clear tediousness, which is 9.7% heavier than a regular ounce. A troy ounce of silver is $32.70, up 13% this year.
Some Finer Points
Confused? This won’t help: The purity of investment gold, called its fineness, is measured in either parts per thousand or on a 24-point karat scale. A karat is different from a carat, the gemstone weight, but our friends in the U.K.—who adopted troy ounces in the 15th century—often spell both words with a “c.” Gold bricks like the ones central banks swap are called Good Delivery bars, and weigh 400 troy ounces, give or take, worth more than $1.3 million. If you buy a few, lift with your legs; each weighs a little over 27 regular pounds (as opposed to troy pounds, which, it pains us to note, are 12 troy ounces, not 16).
There are many options for smaller players, like Canadian Maple Leaf coins, which are 24-karat gold; South African Krugerrands, at 22 karats, and alloyed with copper for durability; and Gold American Eagles, 22 karats, with some silver and copper. Proof coins cost extra for their high polish, artistry, and limited runs, and may or may not become collectibles. Humbler-looking bullion coins are bought for their metal value. Prefer the latter if you aren’t a coin hobbyist. Avoid infomercials and stick with high-volume dealers. Even so, markups of 2% to 4% are common. Costco Wholesale , which sells gold in single troy ounce Swiss bars, charges 2%, but often runs out, and limits purchases to two bars per member a day. Factor in the cost of storage and insurance, too.
ETFs are more economical. For example, iShares Gold Trust costs 0.25%, not counting commissions. For long-term holders, as opposed to traders, there is a smaller fund called iShares Gold Trust Micro , which costs 0.09%.
Resist fleeing stocks for gold. The surprisingly long outperformance of gold is mostly a function of its recent run-up. From 1975 through last year, gold turned $1 invested into about $16, versus $348 for U.S. stocks. That starting point has a legal basis. President Franklin Roosevelt largely outlawed private gold ownership in 1933; President Richard Nixon delinked the dollar from gold in 1971; and President Gerald Ford made private ownership legal again at the end of 1974.
Gold has been a so-so inflation hedge over the past half-century, and at times a disappointing one. In 2022, when U.S. inflation peaked at a 40-year high of over 9%, the gold price went nowhere. The problem is that high inflation can prompt a sharp increase in interest rates. “If people can clip a 5% coupon on a T-bill, often they’d prefer to do that than have either a lump of metal or an ETF that doesn’t produce cash flow,” says BlackRock’s Koesterich.
Likewise, while gold has generally offset stock declines this year, it hasn’t always done so in the heat of the moment. Recall tariff “liberation day” early this month, which sent U.S. stocks down close to 11% in three days and pulled gold down nearly 5%. “This isn’t an uncommon scenario,” says RBC’s Louney. “When investors were losing elsewhere in their portfolio, gold was sold as well to cover those losses.”
Our top tip on how gold behaves is this: It doesn’t. People do the behaving, and they are appallingly unreliable. Use bonds as a stock market hedge. If they don’t work, fall back to patience. For inflation protection, think of assets that are a better match than gold for the goods and services that you buy every week. A diversified commodities fund has precious metals but also industrial ones, along with energy and grains. Treasury inflation-protected securities are explicitly linked to the consumer price index, which measures inflation for a theoretical individual whose buying patterns differ from your own, but are close enough.
Own a house. Stick with a workaday, reliable car. Yes, cars deteriorate. But so does nearly everything on a long enough timeline. Rely mostly on stocks, which represent businesses, which wouldn’t endure if they couldn’t turn raw inputs like commodities into something more profitable. There’s even a miner, Newmont, in the S&P 500.
The Case for Mining Stocks
Speaking of which, UBS’ Major recently upgraded both Canada’s Barrick and Denver-based Newmont from Neutral to Buy. “Both very much fall into that category of having a challenging recent track record,” he says. Newmont has lost 20% over the past three years while gold has gained 76%, which Major blames on difficult acquisitions and earnings shortfalls. Barrick, down 8%, has been in a dispute with Mali since 2023, when its government instituted a new mining code that gives it a greater share of profits. In recent days, authorities have shut the company’s offices in the capital city of Bamako over alleged nonpayment of taxes.
These are the sort of headaches that Krugerrands in a safe don’t produce. But Major calls expectations “adequately reset,” free cash flow attractive, and guidance achievable. Newmont, at 13 times next year’s earnings consensus, is selling assets, and Barrick, at 10 times, has healthy production growth.
Major also likes London-based, Toronto-listed Endeavour Mining , up 40% over the past three years and trading at nine times earnings, although he says it has “higher jurisdictional risk.” It is focused on West Africa, especially Burkina Faso, which had a coup d’état in 2022. You’d think the stock would be doing worse amid such political upheaval. Then again, Burkina Faso since 1966 has had eight coups, five coup attempts, and one street ousting of a president who tried to change the constitution to remain in power. That works out to an uprising every four years, on average.
Montezuma’s scatological name for gold might have been prescient, considering the sometimes-odious consequences for small countries that find it.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


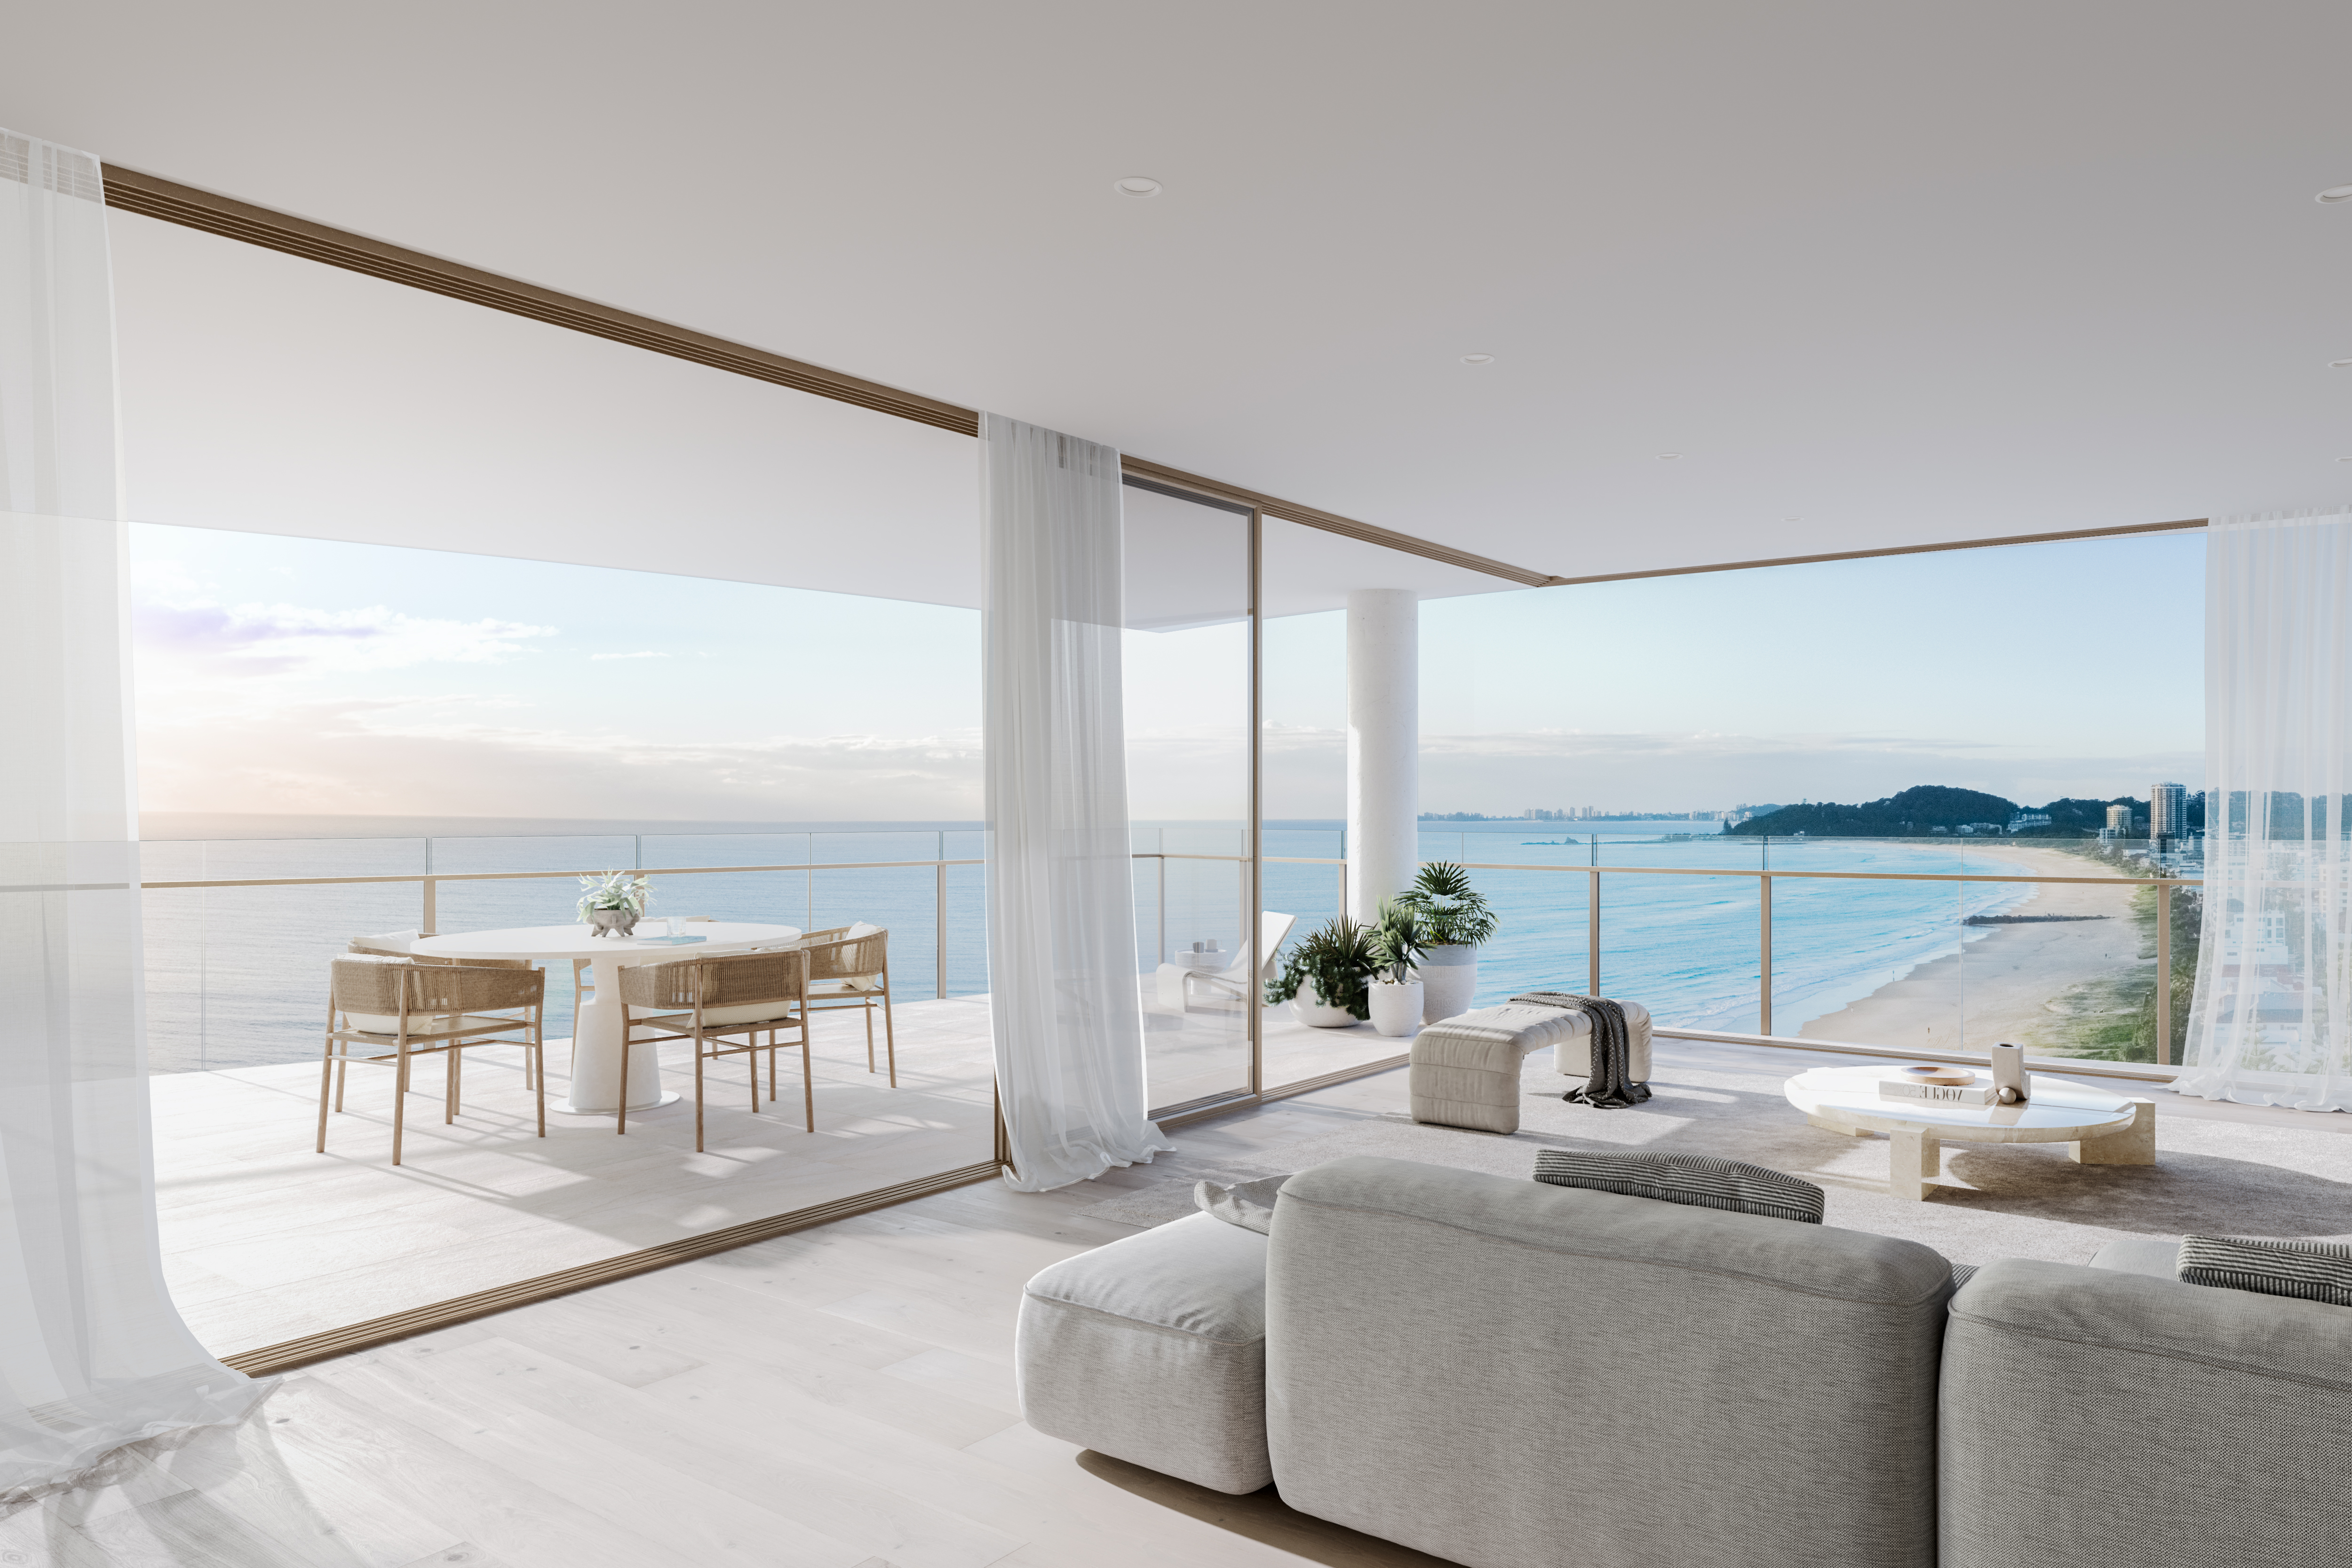
A Sydney couple has paid $15.5 million for the Grand Penthouse at Marquee’s $285 million La Belle Residences beachfront development which is nearing completion at Palm Beach, eclipsing the record for an off-the-plan apartment sale on the southern Gold Coast. The sprawling single level 640 sqm beachfront residence, with sweeping views of the Gold Coast …
Continue reading “$15.5m La Belle Penthouse eclipses southern Gold Coast record”
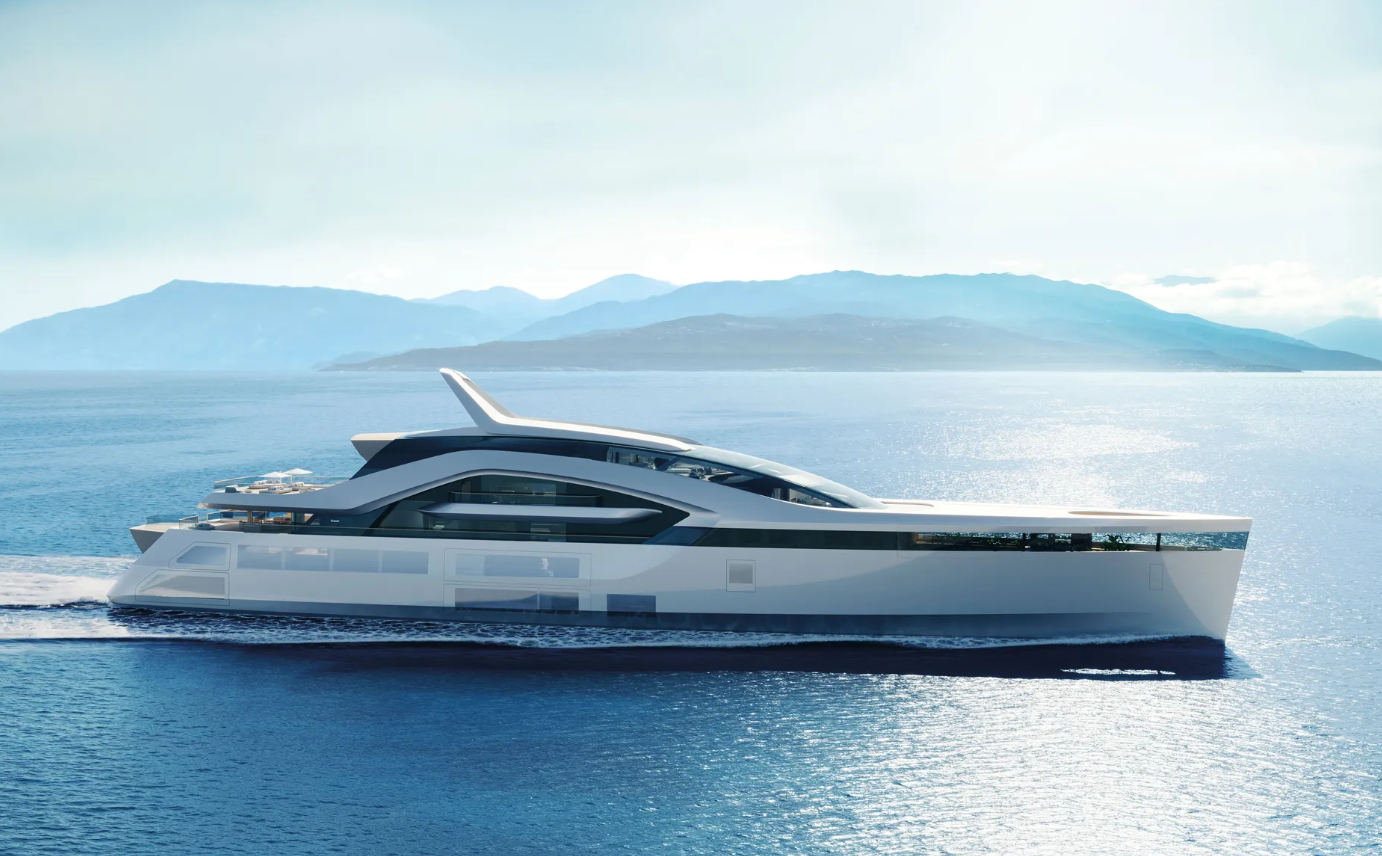
On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
The ASX 200 rose 1.28 per cent in the week ending 30 October as miners rallied, consumer stocks fell and rate-rise expectations climbed
6 min
The Australian sharemarket rose during four of five sessions in the week ending 30 October, but the headline gain concealed a sharp divide between recovering miners, rate-sensitive property stocks and retailers hit by inflation and weaker trading updates.
The Australian sharemarket finished October with a positive week, although the route higher was anything but uniform.
The S&P/ASX 200 closed Friday 30 October at 8,908.1, gaining 112.9 points, or 1.28 per cent, from the previous Friday’s close of 8,795.2.
The All Ordinaries advanced 1.34 per cent to 9,025, while the more concentrated S&P/ASX 20 gained 1.11 per cent.
The benchmark rose during four of the week’s five sessions. It added 0.17 per cent on Monday and 0.46 per cent on Tuesday, before slipping 0.03 per cent on Wednesday. It recovered 0.50 per cent on Thursday and gained another 0.18 per cent on Friday.
The index briefly reached 8,933.3 but again failed to establish itself above the psychologically important 9,000-point mark.
The week’s central tension was between a resources recovery and a less forgiving domestic interest-rate outlook.
Materials gained 4.06 per cent, reclaiming part of the previous week’s heavy fall. Australian real estate investment trusts rose 3.77 per cent, financials gained 1.05 per cent and energy advanced 1.39 per cent.
At the other end of the market, consumer staples fell 5.13 per cent and consumer discretionary shares lost 2.35 per cent. Utilities declined 0.73 per cent and communication services eased 0.68 per cent.
Inflation changes the conversation
Australia’s September inflation data was the week’s pivotal domestic release.
Annual inflation of 4.3 per cent pushed market pricing towards another possible Reserve Bank increase and disrupted Wednesday’s early sharemarket rally.
By Thursday’s close, one widely followed market measure placed the probability of an increase in the cash rate to 4.85 per cent at approximately 80 per cent.
That pricing does not make an increase certain. It does, however, change the framework through which investors assess Australian businesses.
Companies dependent on discretionary household spending face renewed pressure on sales and margins. Property trusts, banks, developers and highly leveraged companies must be considered against the prospect of higher funding costs.
Banks present a more complicated equation. Higher rates can support margins, but they may also slow credit growth and increase arrears.
Miners recover
BHP gained 4.56 per cent across the week to close at $57.56, making a substantial contribution to the benchmark’s rise.
The recovery followed an 8.3 per cent fall during the previous week and helped lift the broader materials sector.
Northern Star Resources added 4.59 per cent, while Goodman Group advanced 6.85 per cent to become the strongest performer in the ASX 20.
The commodities picture was mixed. Gold fell approximately 3.12 per cent on the cited weekly measure, while Brent crude added around 0.68 per cent.
The Australian dollar was little changed at approximately US70.35 cents at the reference point.
Supermarkets and consumer shares retreat
The consumer-staples story was markedly weaker.
Coles fell 11.77 per cent after its first-quarter update, making it one of the largest significant-company declines of the week.
Woolworths lost 3.66 per cent and Wesfarmers fell 4.48 per cent to $76.69 as investors processed company trading commentary against the prospect of another squeeze on household demand.
The moves illustrate how quickly expectations can change when an apparently defensive company disappoints.
Supermarkets still benefit from the recurring need for groceries, but customers can trade down, shift between chains and reduce spending on higher-margin discretionary lines.
Wesfarmers carries exposure to several consumer categories through businesses including Bunnings, Kmart and Officeworks. A renewed rate increase would place more pressure on households already confronting higher prices.
The wider market’s biggest movements
Among companies outside the ASX 20, Mesoblast surged 27.32 per cent, SiteMinder gained 22.74 per cent and Zip rose 22.60 per cent.
The sharpest weekly falls included 4DMedical, down 33.51 per cent; Tuas, down 29.95 per cent; Catalyst Metals, down 17.47 per cent; and Champion Iron, down 13.35 per cent.
Those percentages require context.
The movements in BHP, Commonwealth Bank and other very large companies had substantially more influence on the index than similarly dramatic changes among smaller companies.
A 20 per cent move in a relatively small stock may attract more attention than a two per cent rise in a major bank, but the bank can have the greater effect on the market.
How the ASX 20 moved
The following list uses the S&P/ASX 20 constituents and five-session movements reported at the 30 October close.
Where the component feed did not publish a valid five-day comparison, no figure has been estimated.
BHP Group: Up 4.56 per cent
Commonwealth Bank: Up 1.66 per cent
Rio Tinto: Down 2.20 per cent
National Australia Bank: Up 0.48 per cent
Westpac: Up 0.08 per cent
ANZ Group: Up 1.92 per cent
CSL: Up 2.05 per cent
Macquarie Group: Up 2.19 per cent
Wesfarmers: Down 4.48 per cent
Woodside Energy: Up 1.43 per cent
Goodman Group: Up 6.85 per cent
Telstra: Five-day comparison unavailable from the cited component feed
Woolworths: Down 3.66 per cent
Fortescue: Five-day comparison unavailable from the cited component feed
Transurban: Down 2.40 per cent
QBE Insurance: Down 1.21 per cent
Aristocrat Leisure: Up 0.63 per cent
Northern Star Resources: Up 4.59 per cent
Sigma Healthcare: Down 0.36 per cent
Brambles: Down 1.20 per cent
The companies dominating the conversation
Coles was the week’s standout media-facing company for the wrong reason.
Its trading update produced an outsized repricing and drew attention across the grocery and retail sectors. Woolworths and Wesfarmers were also scrutinised as investors considered how stubborn inflation and another possible rate rise could affect sales volumes.
Bank of Queensland offered a more positive corporate signal.
The bank reported that its FY26 net interest margin had risen six basis points to 1.70 per cent, ahead of the 1.68 per cent expected by the market according to contemporaneous reporting.
Bank of Queensland shares rose 5.8 per cent on Thursday, while the major banks also rallied.
Endeavour Group finished Friday at $3.39, up 4.31 per cent on the day, and released the results of its annual general meeting.
The movement was notable during a week in which investors were highly sensitive to consumer-facing companies. The AGM result should not, however, be presented as the sole cause of the share-price increase without further supporting company guidance.
Mesoblast’s 23.4 per cent Thursday rise and 27.32 per cent weekly gain returned the biotechnology company to the centre of market attention.
For editors, it is important to separate the size of that percentage movement from its influence on the index. Mesoblast was an eye-catching performer, but it did not drive the ASX 200 in the way BHP or Commonwealth Bank did.
Qantas remained part of the broader market conversation as investors watched travel demand and company updates.
However, the primary-source review did not locate a fresh Qantas announcement that justified attributing a major weekly market movement to new company information. The airline should therefore remain on the monitoring list rather than being forced into the week’s causal narrative.
Is Australia’s IPO market reopening?
The official ASX new-listings pipeline remains active but selective.
ASX’s upcoming-floats page included formal applications with offer timetables extending through October and at least one anticipated listing on 30 November.
The exchange notes that its page covers companies for which a formal listing application has been received. It does not represent every company privately exploring a float.
The wider debate concerns whether Australia’s public market is sufficiently competitive when high-growth businesses can pursue capital in the United States or remain privately funded for longer.
ASX has previously raised possible reforms designed to improve the attractiveness of the local market. These include debate about reducing minimum free-float requirements and streamlining aspects of the admissions process.
An enhanced fast-track pathway for qualifying applicants can shorten the review process, reducing the execution risk created when market conditions change during a long IPO timetable.
That does not remove the more fundamental challenge.
New floats still require credible earnings or a convincing growth pathway, sensible pricing and enough genuine free float to support trading after listing.
Investors can already obtain diversified exposure through low-cost exchange-traded funds or buy established, liquid businesses. A float must therefore offer more than novelty.
The current pipeline suggests that the IPO window is open, but it is not indiscriminate.
What investors will watch next
The Reserve Bank’s next decision now sits at the centre of the domestic outlook.
Any change in cash-rate expectations will flow rapidly through banks, retailers, property trusts, listed developers and companies carrying substantial debt.
Investors will also watch whether the materials recovery can continue, whether BHP can hold its rebound and whether consumer companies provide further evidence of slowing demand.
Overseas, technology-sector volatility, commodity prices and the United States interest-rate outlook will continue to shape Australian trading.
The week’s 1.28 per cent headline gain was encouraging, but it was not a broad declaration of confidence.
It was a rotation towards miners, selected financials and property securities—and away from consumer businesses facing a more difficult inflation and interest-rate equation.
Market dashboard
S&P/ASX 200: 8,908.1, up 1.28 per cent for the week
All Ordinaries: 9,025, up 1.34 per cent
S&P/ASX 20: 5,214.7, up 1.11 per cent over five sessions
Best sector: Materials, up 4.06 per cent
Next-best sector: A-REITs, up 3.77 per cent
Weakest sector: Consumer staples, down 5.13 per cent
Major large-cap winner: Goodman Group, up 6.85 per cent
Major large-cap loser: Coles, down 11.77 per cent
AUD/USD: Approximately US70.35 cents at the weekly reference point
Gold: Approximately US$3,885 an ounce, down 3.12 per cent on the cited weekly measure
Brent crude: Approximately US$117.70 a barrel, up 0.68 per cent on the cited weekly measure

A luxury lifestyle might cost more than it used to, but how does it compare with cities around the world?

From elevated skincare to handcrafted home pieces, this year’s most thoughtful gifts go beyond the expected.