Higher Interest Rates Not Just for Longer, but Maybe Forever
Rate projections suggest many Fed officials see a rising ‘neutral rate’

 3 min
On Wednesday, Federal Reserve officials surprised markets by signalling interest rates won’t fall as much as previously planned.
The tweak might be more important than it looks. In their projections and commentary, some officials hint that rates might be higher not just for longer, but forever. In more technical terms, the so-called neutral rate, which keeps inflation and unemployment stable over time, has risen.
This matters to any investor, business or household whose plans depend on interest rates over a decade or longer. It could explain why long-term Treasury yields have risen sharply in the past few months, and why stocks are struggling.
The neutral rate isn’t literally forever, but that captures the general idea. In the long run neutral is a function of very slow moving forces: demographics, the global demand for capital, the level of government debt and investors’ assessments of inflation and growth risks.
The neutral rate can’t be observed, only inferred by how the economy responds to particular levels of interest rates. If current rates aren’t slowing demand or inflation, then neutral must be higher and monetary policy isn’t tight.
Indeed, on Wednesday, Fed Chair Jerome Powell allowed that one reason the economy and labor market remain resilient despite rates between 5.25% and 5.5% is that neutral has risen, though he added: “We don’t know that.”
Before the 2007-09 recession and financial crisis, economists thought the neutral rate was around 4% to 4.5%. After subtracting 2% inflation, the real neutral rate was 2% to 2.5%. In the subsequent decade, the Fed kept interest rates near zero, yet growth remained sluggish and inflation below 2%. Estimates of neutral began to drop. Fed officials’ median estimate of the longer-run fed-funds rate—their proxy for neutral—fell from 4% in 2013 to 2.5% in 2019, or 0.5% in real terms.
As of Wednesday, the median estimate was still 2.5%. But five of 18 Fed officials put it at 3% or higher, compared with just three officials in June and two last December.
In 2026, officials project the economy growing at its long-term rate of 1.8%, unemployment at its long-run natural level of 4%, and inflation at its 2% target. Those conditions would normally be consistent with interest rates at neutral. As it happens, officials think the fed-funds rate will end the year at 2.9%—another hint they think neutral has risen.
There are plenty of reasons for a higher neutral. After the global financial crisis, businesses, households and banks were paying down debt instead of borrowing, reducing demand for savings while holding down growth and inflation. As the crisis faded, so did the downward pressure on interest rates.
Another is government red ink: Federal debt held by the public now stands at 95% of gross domestic product, up from 80% at the start of 2020, and federal deficits are now 6% of GDP and projected to keep rising, from under 5% before the pandemic. To get investors to hold so much more debt probably requires paying them more. The Fed bought bonds after the financial crisis and again during the pandemic to push down long-term interest rates. It is now shedding those bondholdings.
Inflation should not, by itself, affect the real neutral rate. However, before the pandemic the Fed’s principal concern was that inflation would persist below 2%, a situation that makes it difficult to stimulate spending and can lead to deflation, and that is why it kept rates near zero from 2008 to 2015. In the future it will worry more that inflation persists above 2%, and err on the side of higher rates with little appetite for returning to zero.
Other factors are still pressing down on neutral, such as an aging world population, which reduces demand for homes and capital goods to equip workers.
So neutral has probably risen since 2019, but not to its pre-2008 level. Indeed, futures markets peg rates a decade from now at around 3.75%.
Of course, this is all just a forecast. If inflation comes down painlessly in the next year, if growth slows abruptly, or if Treasury yields drop, then estimates of neutral will also come down. For now, the evidence suggests the public should get used to higher rates as far as the eye can see.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”
 2 min
Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates.
The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index rose 1.71 per cent.
Information technology was the strongest major sector, up 2.67 per cent. Megaport gained 4.3 per cent, NextDC rose 3.8 per cent and Life360 added 2.9 per cent, according to the ABC’s closing market report. The move followed a record Nasdaq close and reflected renewed demand for growth assets as oil prices eased.
Consumer discretionary gained 1.29 per cent, while real estate and healthcare each rose 0.76 per cent. The simultaneous strength of technology, discretionary shares and listed property was consistent with a modest easing in market inflation anxiety, although it did not erase expectations of a possible RBA increase at the 29 September meeting.
Energy was the clear laggard, down 1.16 per cent, after Brent crude briefly fell below US$100 a barrel overnight. Origin Energy dropped about 4 per cent, Woodside lost 2.4 per cent and AGL declined 2.3 per cent. Utilities were the weakest sector overall, down 2.03 per cent.
Among larger and liquid movers, Telix Pharmaceuticals rebounded 6.85 per cent after the previous session’s sharp acquisition-related decline. IDP Education jumped 20.67 per cent and was the largest percentage gainer in the ASX 300 screen, while Catalyst Metals fell 14.37 per cent. Those moves should be checked against company announcements before publication; percentage rankings alone do not establish cause or index impact.
Mining performance was mixed. Sunrise Energy Metals rose 12.71 per cent, FireFly Metals added 5.7 per cent and Bellevue Gold gained 4.8 per cent, while Resolute Mining lost 4.44 per cent.
The Australian dollar traded near US71.18 cents late in the session. Oil remained volatile as markets assessed potential US–Iran talks, making energy prices a continuing input into inflation expectations, bond yields and the RBA outlook.
For Wednesday, investors will watch oil, offshore technology leads, Australian bond yields and any new evidence that changes the probability of a September rate rise.
Market dashboard
S&P/ASX 200: 8,757.8, up 25.9 points or 0.30 per cent.
All Ordinaries: 8,951.0, up 0.36 per cent.
Best sector: Information Technology, up 2.67 per cent.
Weakest sector: Utilities, down 2.03 per cent. Energy fell 1.16 per cent.
Material winner: Telix Pharmaceuticals, up 6.85 per cent. Megaport rose 4.3 per cent and NextDC rose 3.8 per cent.
Material loser: Origin Energy, down about 4 per cent. Woodside fell 2.4 per cent.
ASX 300 percentage leader: IDP Education, up 20.67 per cent. Confirm announcement context before publication.
ASX 300 percentage laggard: Catalyst Metals, down 14.37 per cent. Confirm announcement context before publication.
AUD/USD: Approximately US$0.7118 late in the session.
Next catalyst: RBA policy decision on 29 September, oil-price volatility and offshore technology trading.
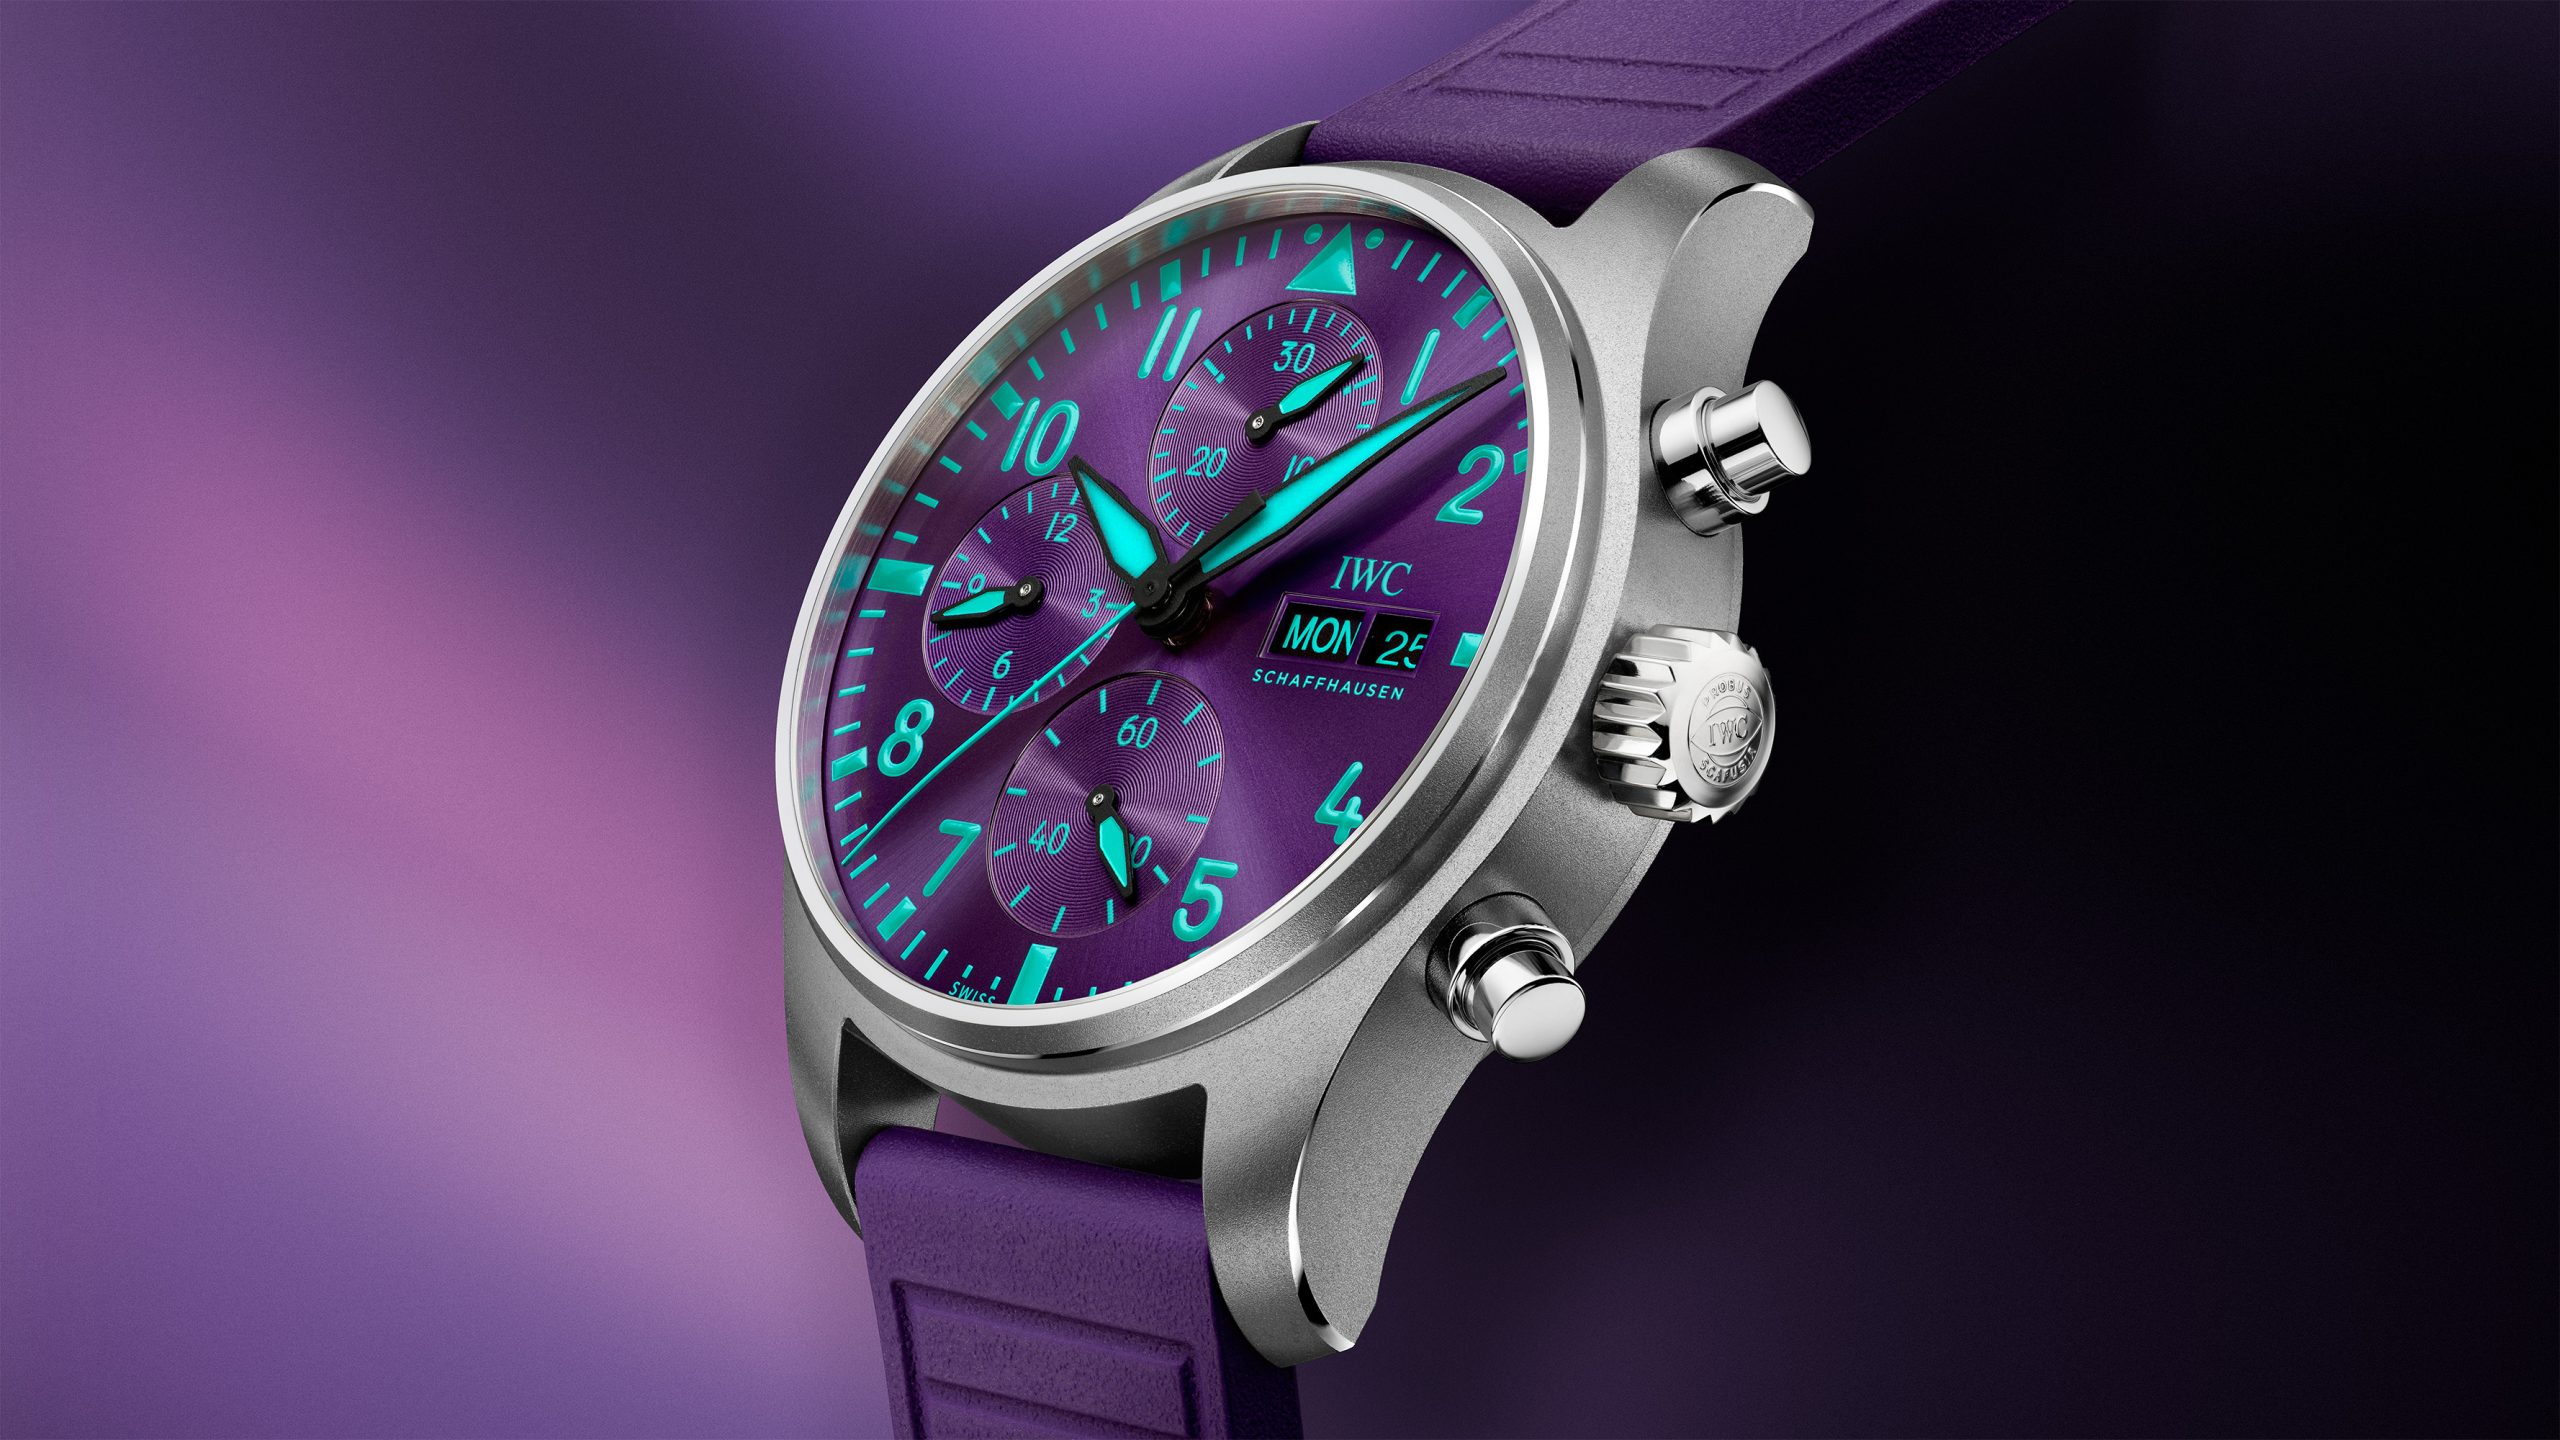
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”

From farm-to-table Thai to fairy-lit mango trees and Coral Sea vistas, Port Douglas has award-winning dining and plenty of tropical charm on the side.