How Divorce Lawyers and Marriage Counsellors Manage Money With Their Partners
They spend all day thinking about money and relationships—so what do they do with theirs?

 4 min
Divorce lawyers and couples counsellors see how often money leads to the end of a relationship. When these professionals return home, they put into action several steps to make sure they have a healthy relationship with their finances and their partners.
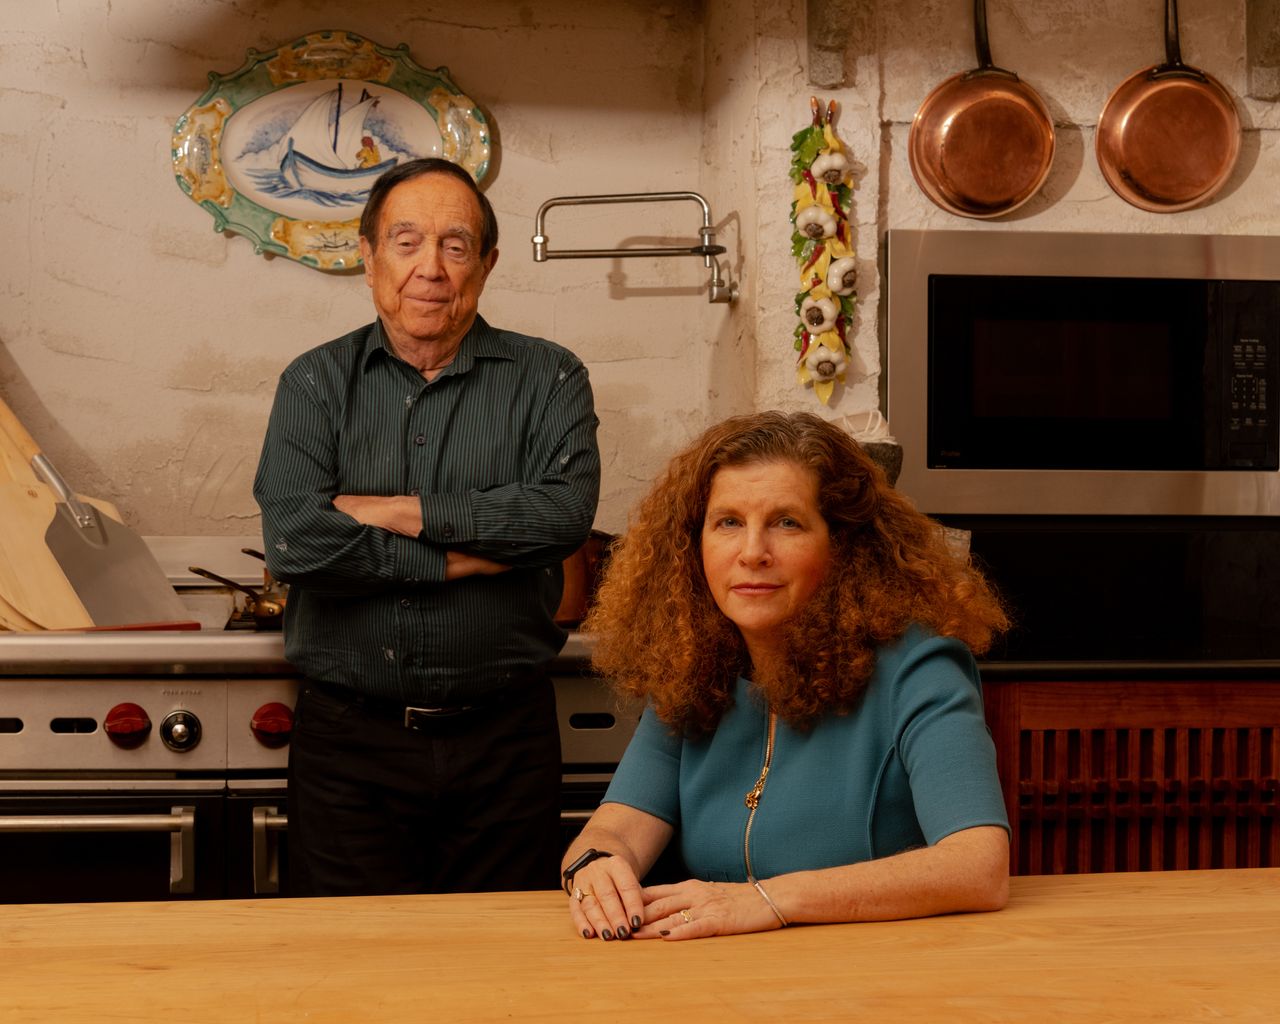
Lisa Zeiderman, 61 years old, a divorce lawyer in New York, and her husband, Lloyd Zeiderman, an 86-year-old wealth and business manager, spent the better part of their respective careers thinking about money and relationships. They have front-row seats to how financial issues can tear couples apart.
At home and at work, Mrs. Zeiderman preaches “the mailbox rule.”
Every weekend, when she and her husband drive out for breakfast, she stops the car at the end of the driveway and checks the mail. While they share money, he takes the lead on managing their investments and communicating any new developments to his wife. But she said checking the literal receipts—both in the mail and digitally—can offer peace of mind.
“If the credit-card statements are no longer available or passwords are changed or you used to have discussions about money and now you don’t, that may be the sign of something brewing around you,” she said.
Sharing money with a romantic partner leads to greater overall relationship satisfaction, and combining financial power in turn leads to greater wealth for the household, studies have found. Despite these demonstrated benefits, many couples see talking about money as a gateway to more fights and less peace.
But many seasoned legal, financial and counselling professionals say they have seen firsthand the repercussions of letting money problems fester. We asked some of them to share even more lessons they have learned and put to the test in their own relationships.
Talk. All the time. Especially when it is uncomfortable.
“Just talk about it” is some of the most common—and occasionally infuriating—advice quarrelling couples receive. But in practice, maintaining a low-stakes, ongoing daily discussion about expenses, savings and your respective financial habits can lessen the tension many people feel around these money conversations, said Matt Lundquist, the 46-year-old founder and clinical director of Tribeca Therapy in New York who also counsels couples.
For the Zeidermans, who have been married for almost 25 years, the conversation never stops—and that is intentional, they both say.
“There’s no scheduled sit-down, and it isn’t an organised event,” Mr. Zeiderman said. “But the bill comes in, we talk about it. If we’re buying something for her daughter or my son, we make a joint decision.”
They both admit they aren’t always in perfect agreement. Over the years, Mr. Zeiderman has lent money to an old friend. When she first saw the wire transfer, Mrs. Zeiderman had some questions. But in talking about the issue, she said, they agreed to call a truce: when a particular expense is especially personal to the other partner, they can allow some leeway.
When Mr. Lundquist and his wife of 13 years talk about coming expenses, savings plans or the impact of inflation on their budget, they don’t only talk about the numbers, he said.
“Don’t just sit down and go through the budget, but parallel to that, say ‘how do you feel about that?’” he said. “It’s astonishing how many couples don’t talk about that and the consequences of that.”
Lay it all on the table.
Valentina Shaknes, a 43-year-old New York City lawyer and one of the founding partners at Krauss, Shaknes, Tallentire & Messeri, has become familiar with a certain story: A successful, confident woman in the throes of divorce proceedings realizes how little she knew of the overall household finances.
“They would really rely and defer to their husbands to manage their family finances, which is so different from their professional lives, where they’re running the show,” Ms. Shaknes said.
In divorce proceedings, Ms. Shaknes describes a document she says she has since come to love: the statement of net worth. Each party fills out expenses, income, assets, liabilities and more in granular detail, so that each has the complete picture of the other’s financial situation. Ms. Shaknes recommends couples try doing this exercise while they are still together, rather than waiting until a breakup.
At home, Ms. Shaknes recreates the process with her husband of 23 years. Each time, they discuss mortgage payments, real-estate taxes and credit-card spending, and adjust for new factors like education costs for their children. The exercise may be tedious, but she’s adamant they both have eyes on the numbers.
“Our lives are so full with all of the responsibilities and obligations, and you have to divide and conquer,” she said. “But you also need to know.”
Be willing to change.
Adam Kol, a mediator, tax lawyer and former financial adviser based in Fort Lauderdale, Fla., calls himself “The Couples Financial Coach.” When he and his wife got married at the start of 2023, he said they had been sharing money for almost a year, in part to more easily manage the expenses related to their wedding.
At the start of their relationship, Mr. Kol identified as “the saver” and his wife as “the spender.”
They have since learned to spend money on things that enrich their lives, and vice versa. When they were first decorating their apartment, Mr. Kol said his wife took the lead on thrifting many of their artworks. Whenever he looks at the variety of pictures and art, Mr. Kol said he sees a visual representation of the middle road they found together.
“Like all couples, we moderate each other,” he said. “She helps me loosen up a little bit and enjoy the day-to-day.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
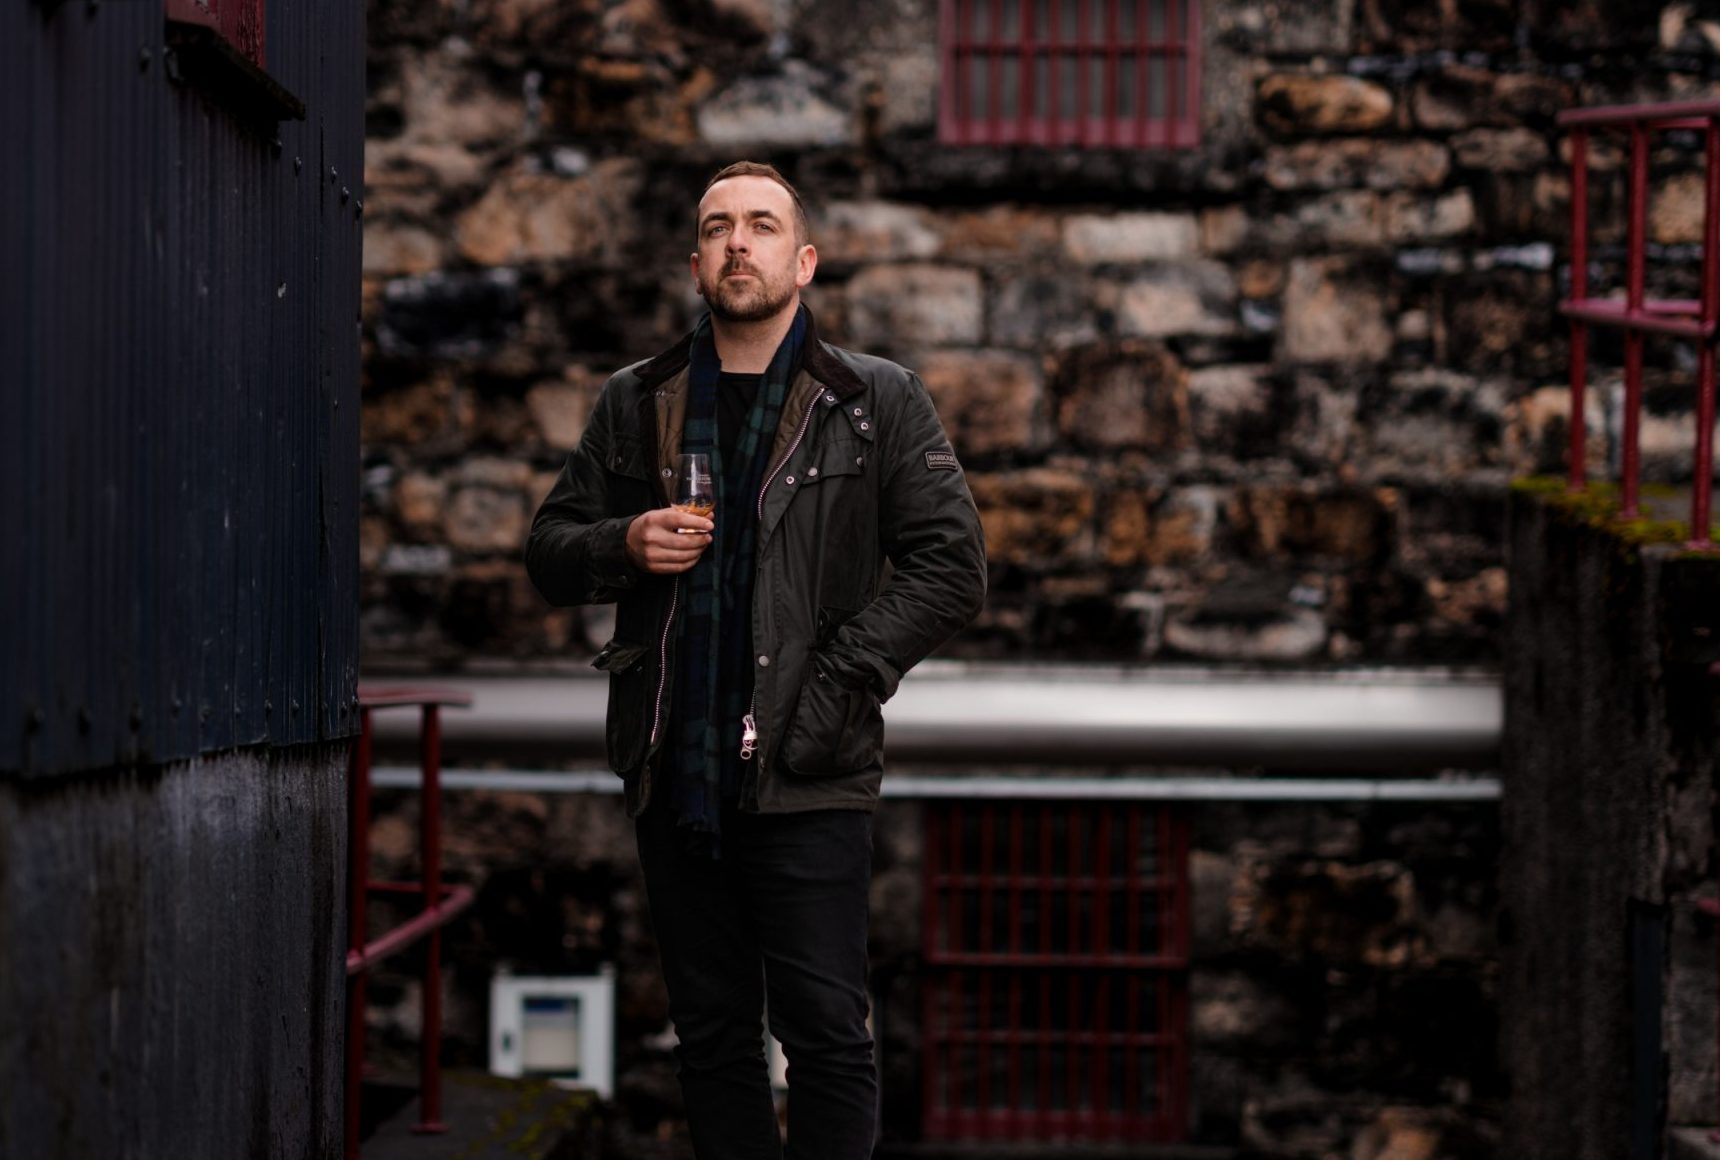
Scotch whisky expert, luxury hospitality strategist and Keeper of the Quaich inductee Ross Blainey is bringing a new philosophy of luxury experiences to Citizen Kanebridge.
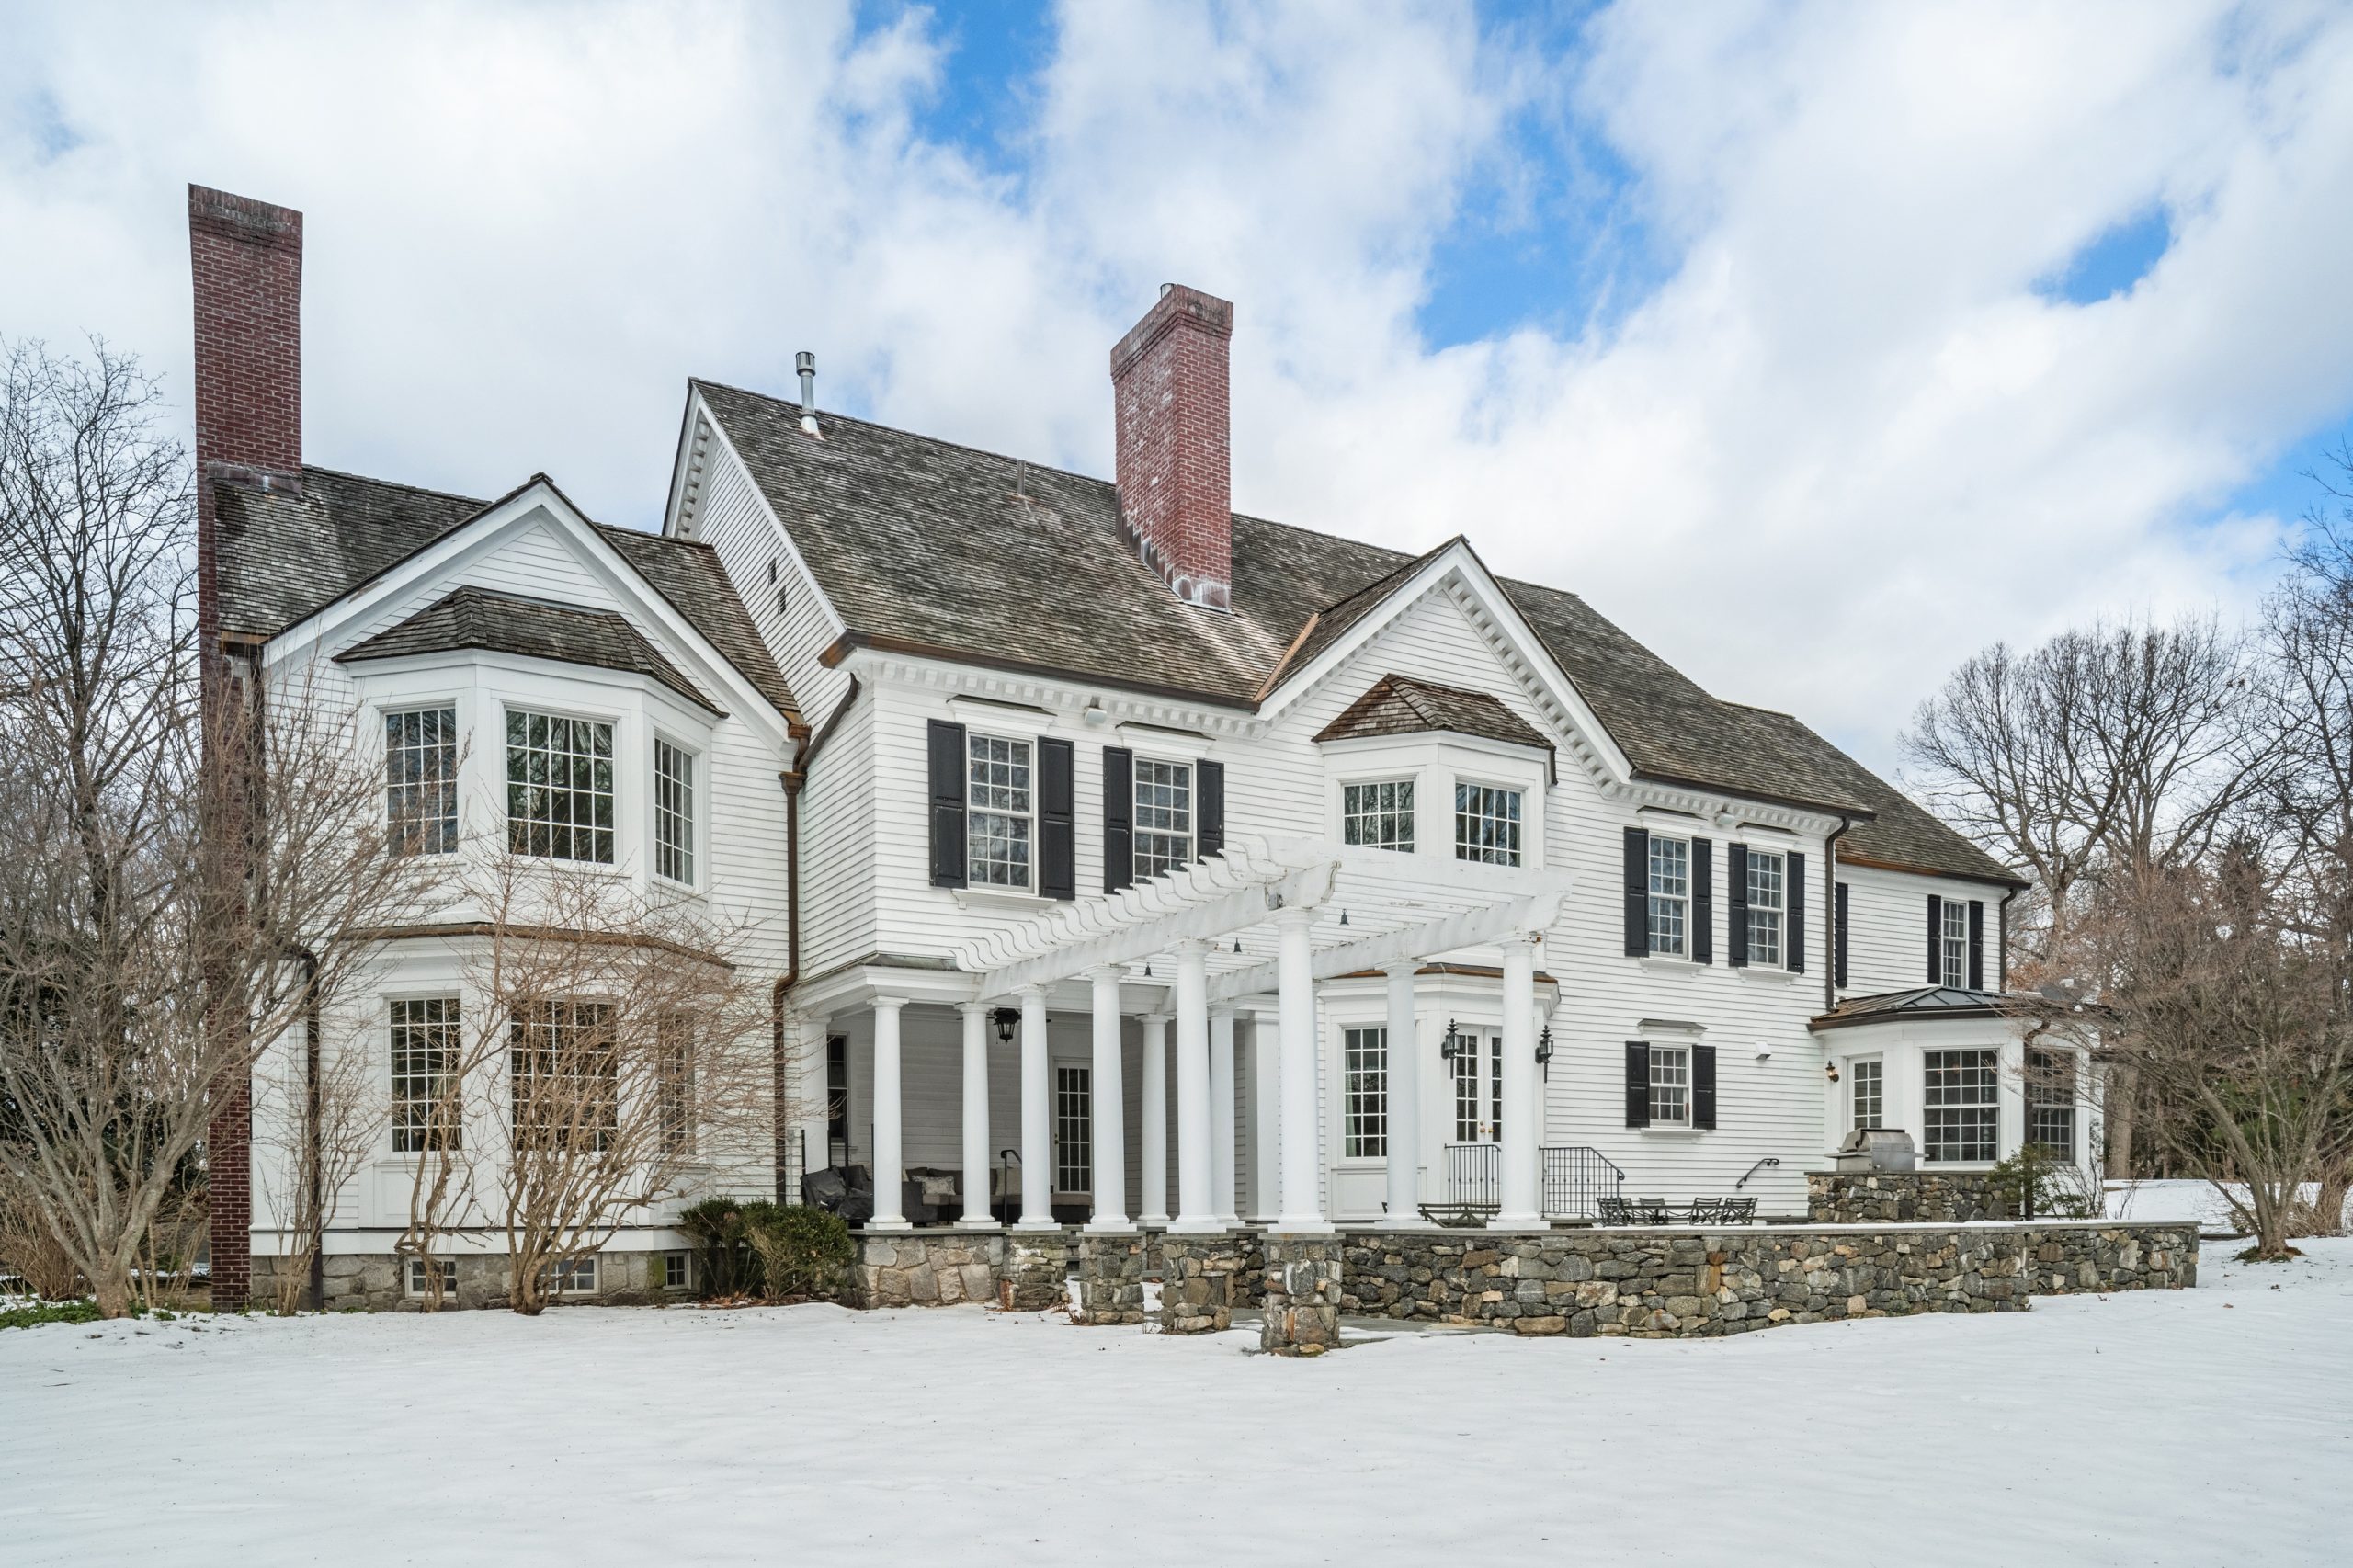
A haven for hedge-fund titans and Hollywood grandees, Greenwich is one of the world’s most expensive residential enclaves, where eye-watering prices meet unapologetic grandeur.