

Rookie Traders Are Calling It Quits, and Their Families Are Thrilled
Many who picked up investing during the pandemic are cooling on the hobby

 4 min
Some novices who took up trading during the pandemic are abandoning the hobby. Their loved ones are breathing a sigh of relief.
Spouses, parents and other family members who were subjected to one too many play-by-plays of market movements say they are happy to have their loved ones back—and equally glad they no longer have to hear about buzzy stocks or cryptocurrencies.
The market swooned in 2022, taking the fun out of day trading for many newbies. The S&P 500, after surging during the pandemic, just wrapped up its worst year since 2008. Bitcoin lost about 65% of its value throughout the year.
Some amateur traders’ families now face the disappearance of the life-changing sums of money they held in their portfolios at the height of the run-up. The stakes are lower for those who put a modest amount into meme stocks or crypto for fun.
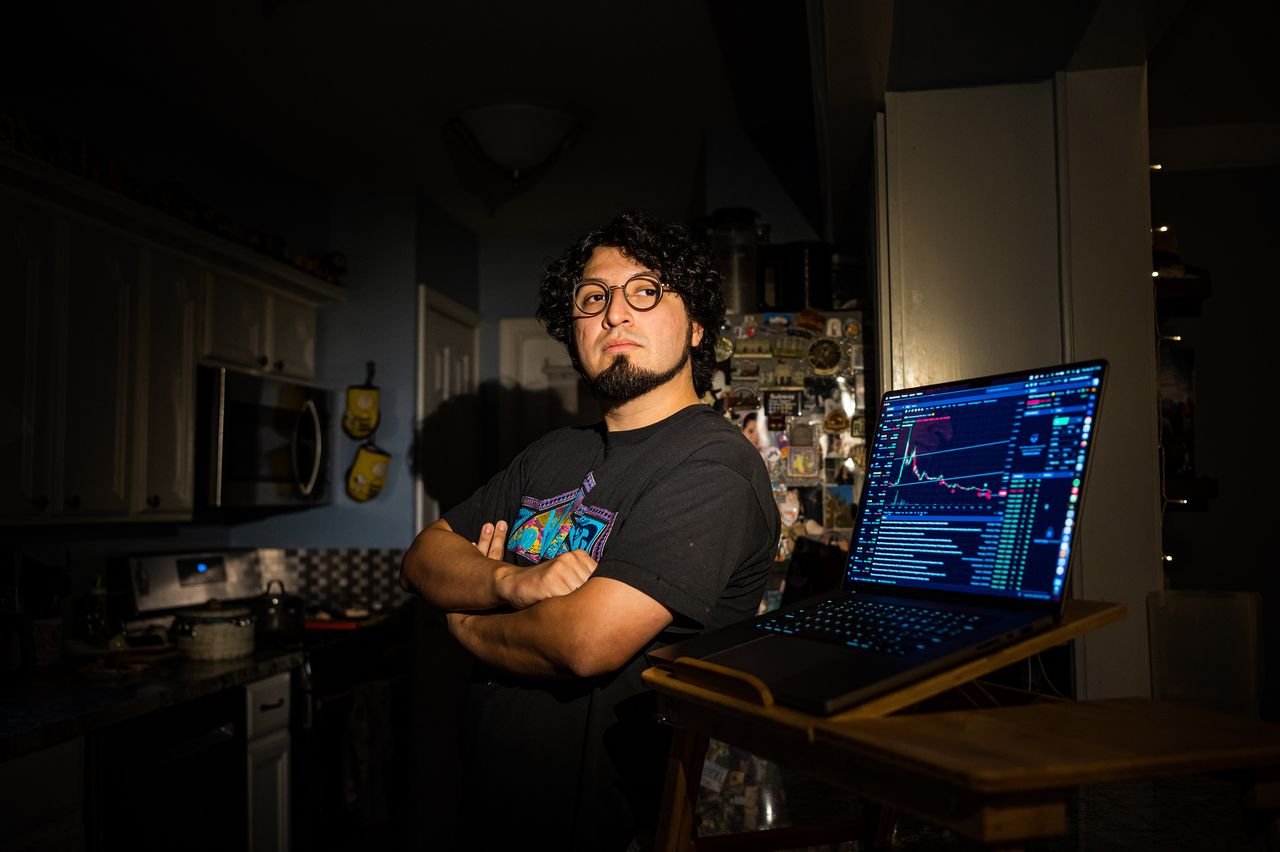
Alan Garcia started trading on Webull Financial LLC early in the pandemic, when his work as a musician dried up. Soon, Mr. Garcia was parked at his desk each day from 8:30 a.m. to 3 p.m. to manage his portfolio of about $2,000. He bet heavily on companies like ElectraMeccanica Vehicles Corp., which makes an electric car seating a single person; ticker symbol, SOLO.
The obsession didn’t end when he sat down in the living room with his wife, Adriana Rodriguez, each evening. For about two years, he talked about investing. Mr. Garcia, a 34-year-old Houston resident, even started watching investing videos in bed at night.
“He was here,” Ms. Rodriguez said, “but he wasn’t here.”
In early 2022, Mr. Garcia lost everything in his portfolio on a bad options bet, leaving him in a foul mood. But the next morning, he felt relieved. After Ms. Rodriguez, a lawyer, left for the office, he worked on his music all day instead of checking the market. He hasn’t traded on the app since.
Ms. Rodriguez is thrilled. Mr. Garcia agrees it is for the best—mostly, anyway. “We’ve never been this good in our lives,” he said. “One day I’ll get that $2,000 back though.”
Trading exploded into the mainstream during the pandemic, when many Americans were stuck at home, flush with stimulus checks and eager to pass the time. New apps made it cheap and easy for newbies to trade from the comfort of their cellphone, and many found a sense of community on investing forums online. In 2021, rookie traders fuelled a run-up in meme stocks that put hedge funds on their heels.
Individual investors are broadly staying invested in stocks, unlike previous downturns when many dumped their holdings. But lots of one-time day traders are finding they are now content to buy and hold rather than try to time their investments. Average daily trading volume is down markedly at major brokerage firms that cater to retail customers.
Vince Major took a job in 2021 as head of marketing at a cryptocurrency wallet company, and soon he was subjecting his mother, Vikki Major, to his thoughts on various cryptocurrency projects and how the sector could revolutionise the financial system.
His mother found it unbearable. Mrs. Major, who is 66 and a juvenile probation officer in Phoenix, told her son to knock it off. That inspired him to give a presentation at an October industry conference titled “My Mother Hates Your Project (and Mine!).”
A duly chastened Mr. Major has cut back the crypto talk on morning FaceTime calls with his mother. After trying to speak about crypto in a more understandable way, he even convinced his mom to buy ether and leave it in a virtual wallet using his company’s app.
Mrs. Major’s ether is down about 40% since she bought it in summer 2021, and it is now worth about $14,000 total. Mr. Major, who is 36 and lives in Los Angeles, said the value of his crypto holdings is up overall because he started buying in 2015 when prices were much lower.
Mrs. Major figures her son knows what he is talking about—even if it was in an annoying way at first. “He’s very intelligent,” she said.
Marvin Lahoud went all in on investing when the pandemic hit, spending up to 10 hours a day trading. Mr. Lahoud, who works at a Boston construction-management company and moved to the U.S. from Lebanon in 2017, started wearing an earpiece to listen to CNBC while doing chores.
His wife, Suzie Lahoud, tried to embrace the investing subculture, too, though she thought his interest might peter out as it had for previous obsessions like photography and videogames. The couple sang their daughter a song about investing as a lullaby.
“It’s always nice to see him get excited about something,” said Ms. Lahoud, a doctoral student. “But there were times I would get a little frustrated just because it was taking up so much of his time and mental space.”
In February 2021, Ms. Lahoud told her husband she was pregnant with their second child. His Robinhood Markets Inc. portfolio had just reached nearly $1 million. He posted to Reddit a screenshot of his account and his family’s news. “I’m on track to retire early and spend time with my kids,” he said, earning 2,000 comments. He was rich—on paper at least.
By early 2022, Mr. Lahoud’s investments started dropping and he faced a massive tax bill from gains he had taken in 2021. Mr. Lahoud gave up trading.
Without investing to keep him occupied, Mr. Lahoud said he felt depressed for the first time in his life. He threw himself into a new endeavour: researching the year 536 AD, which a Harvard professor dubbed the worst in history. That year, a volcanic eruption plunged swaths of the world into darkness, causing widespread famine. Reading about it made him feel better.
“My troubles are so small,” Mr. Lahoud said, “and life is too short.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


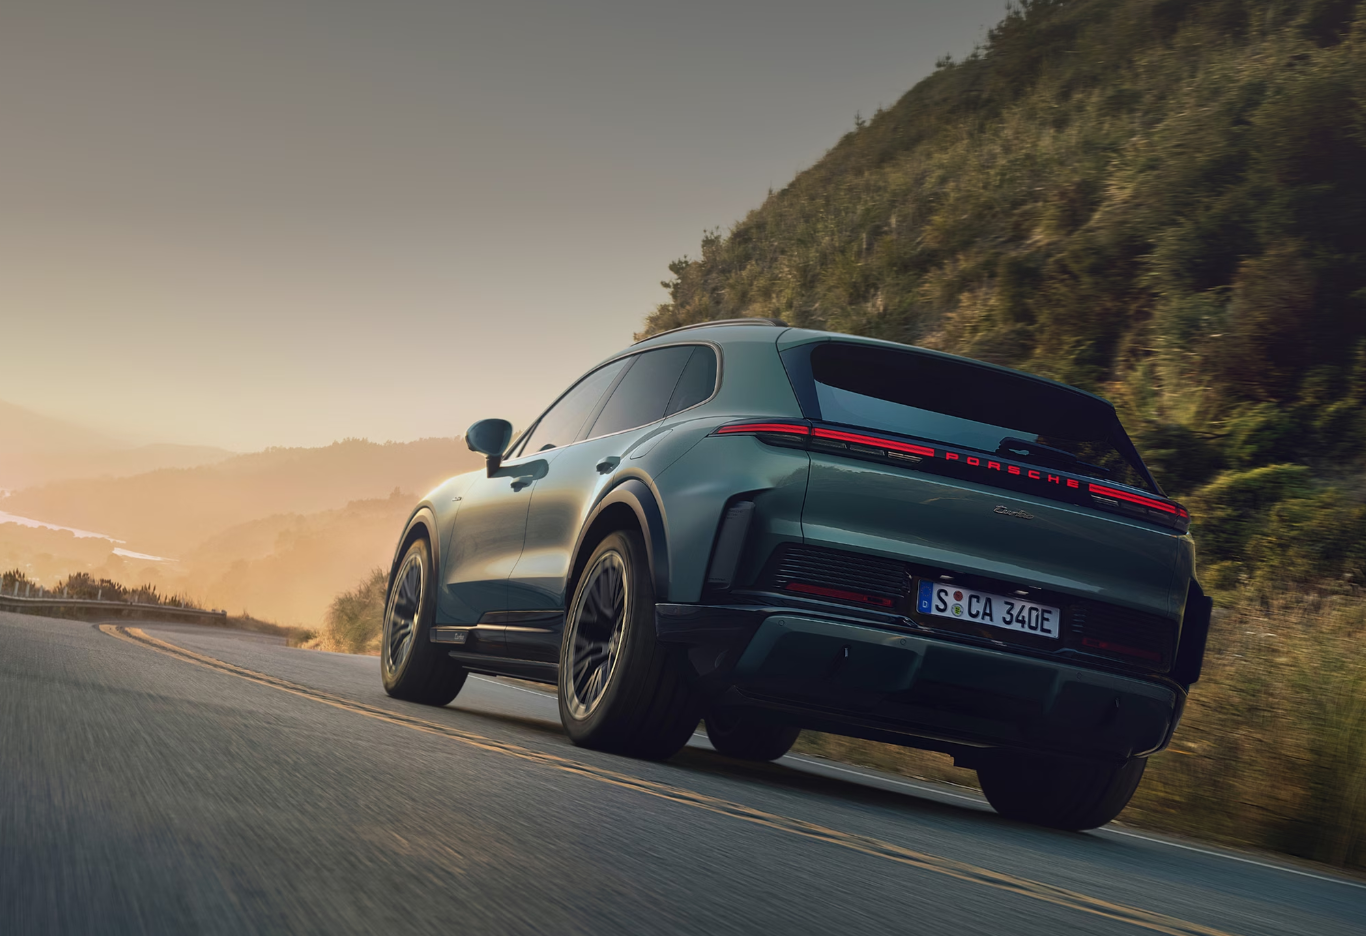
Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.
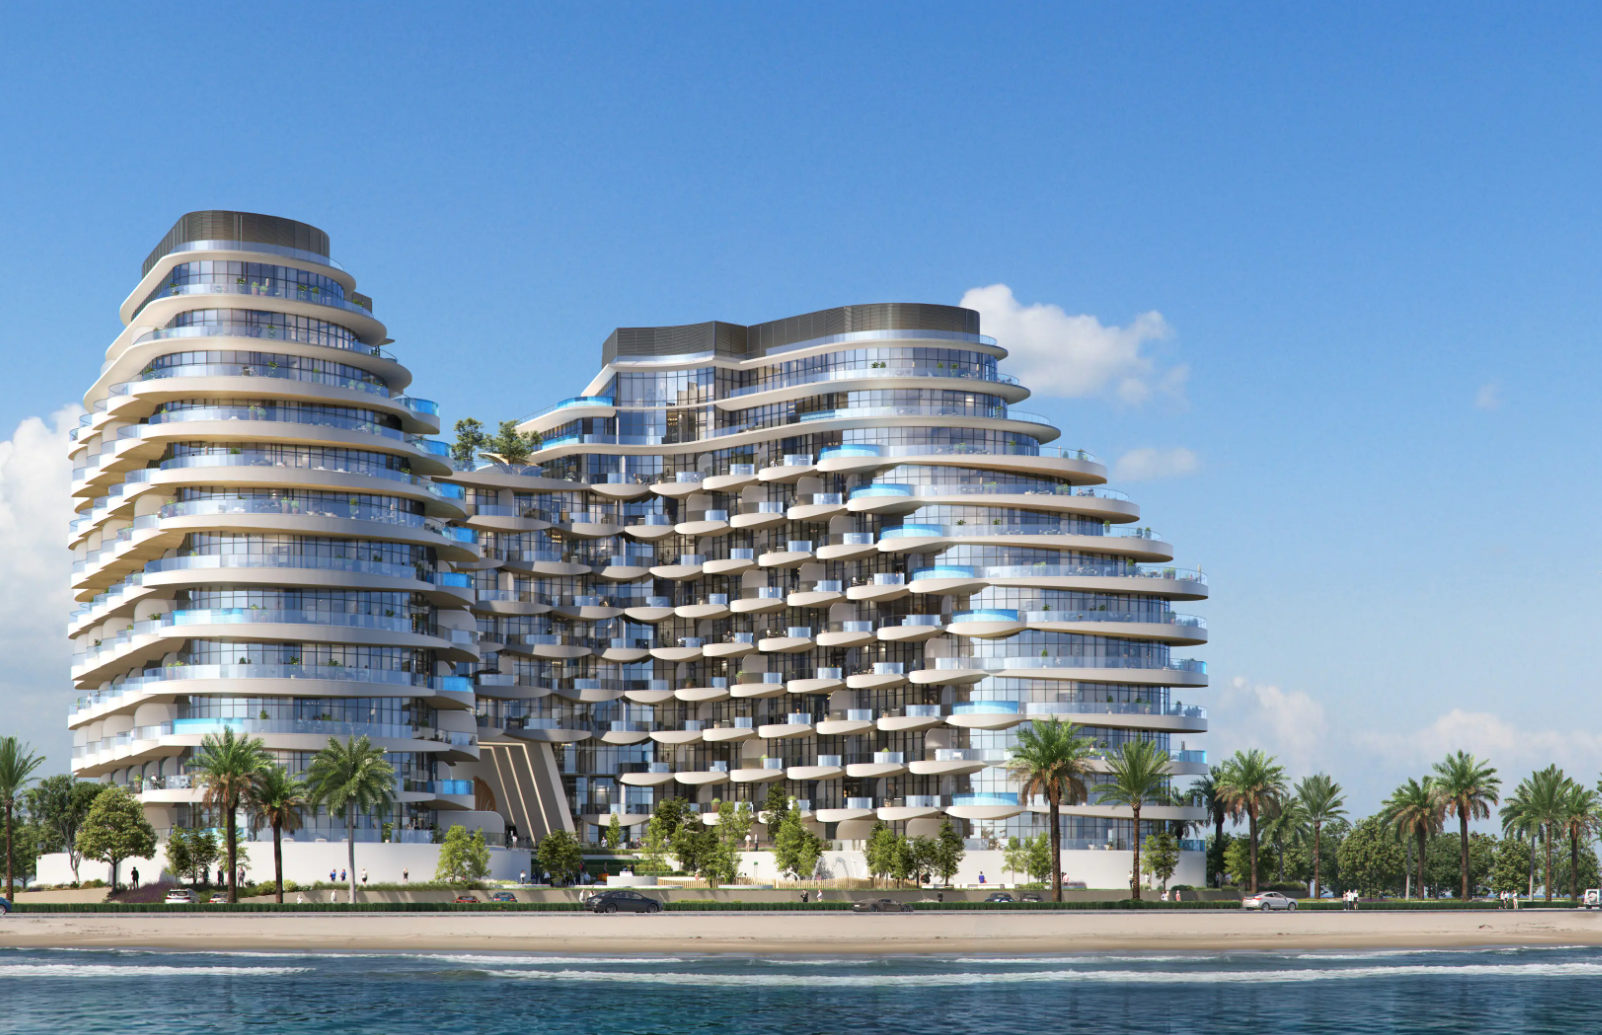
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.

From Italian vegetable-tanned leather to real-world training insight, Australian brand PK9 Gear is redefining what luxury means for discerning dog owners.
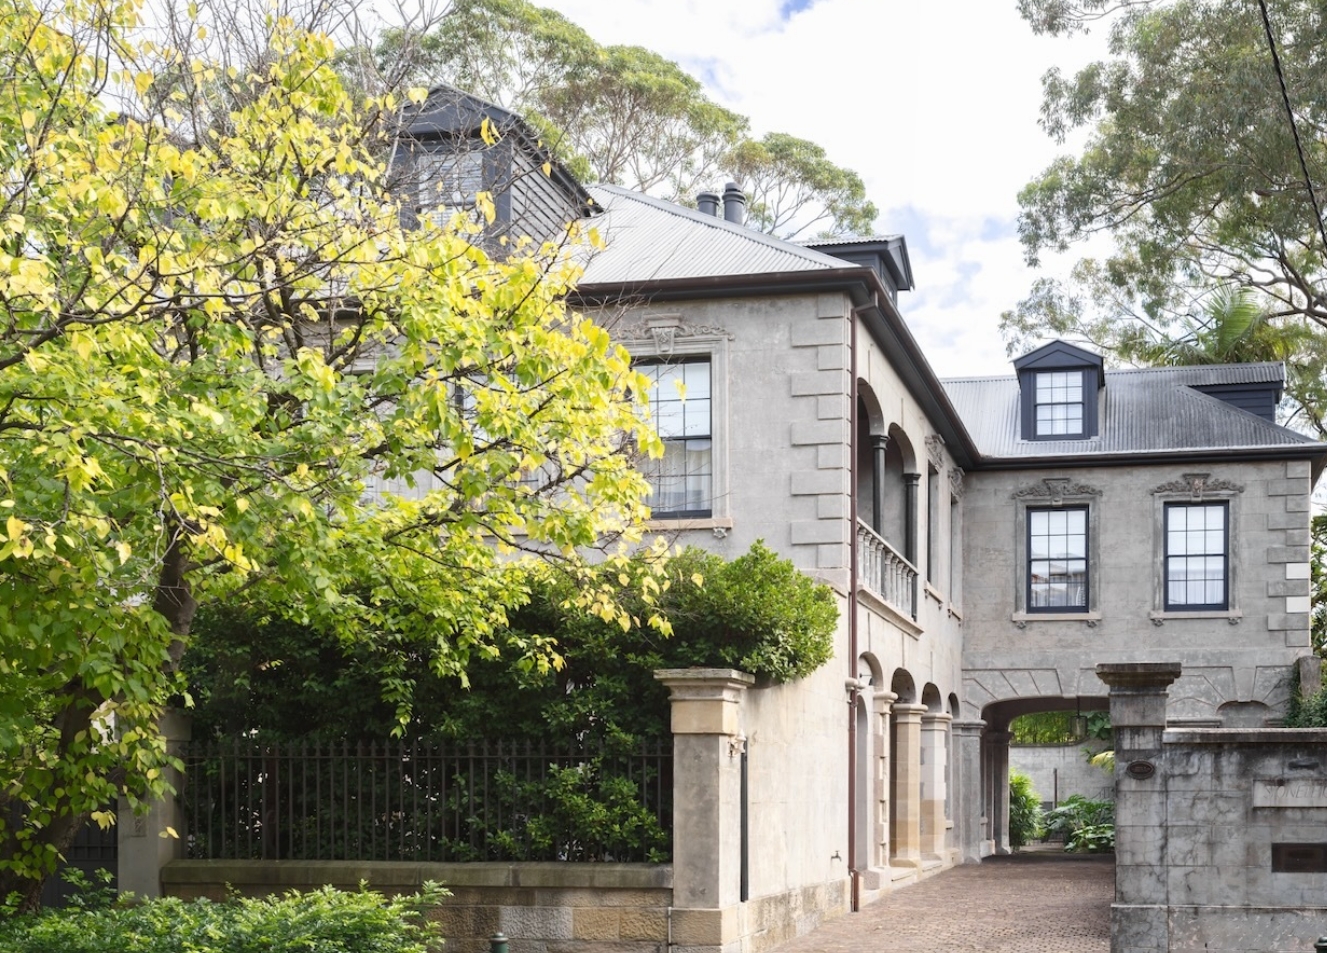
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …