Suddenly There Aren’t Enough Babies. The Whole World Is Alarmed.
Birthrates are falling fast across countries, with economic, social and geopolitical consequences

 10 min
The world is at a startling demographic milestone. Sometime soon, the global fertility rate will drop below the point needed to keep population constant. It may have already happened.
Fertility is falling almost everywhere, for women across all levels of income, education and labor-force participation. The falling birthrates come with huge implications for the way people live, how economies grow and the standings of the world’s superpowers.
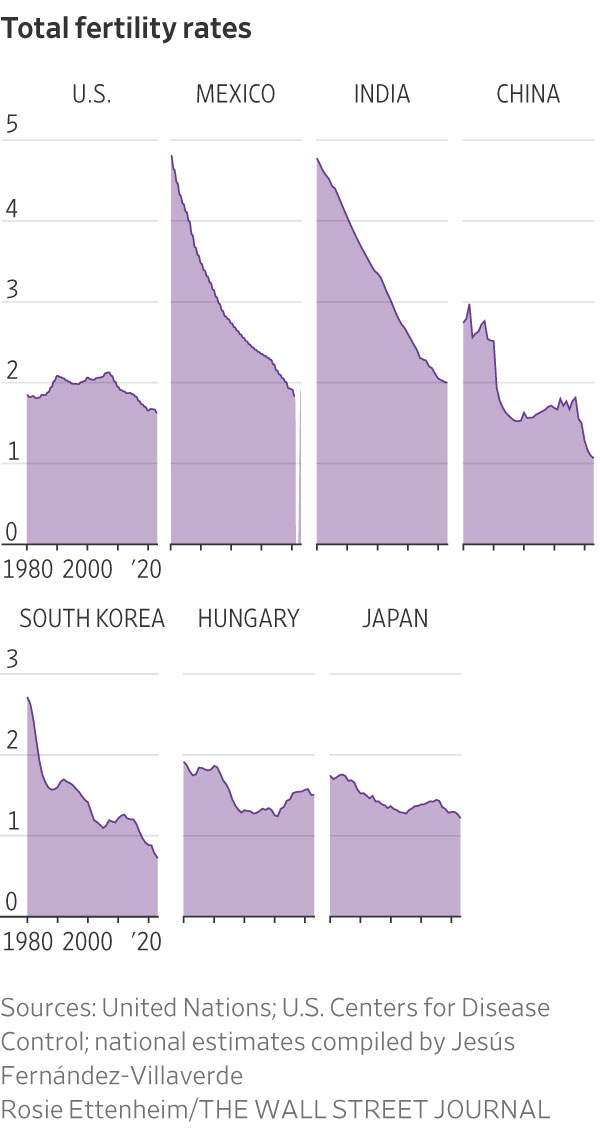
In high-income nations, fertility fell below replacement in the 1970s, and took a leg down during the pandemic. It’s dropping in developing countries, too. India surpassed China as the most populous country last year, yet its fertility is now below replacement.
“The demographic winter is coming,” said Jesús Fernández-Villaverde, an economist specialising in demographics at the University of Pennsylvania.
Many government leaders see this as a matter of national urgency. They worry about shrinking workforces , slowing economic growth and underfunded pensions; and the vitality of a society with ever-fewer children. Smaller populations come with diminished global clout, raising questions in the U.S., China and Russia about their long-term standings as superpowers.
Some demographers think the world’s population could start shrinking within four decades—one of the few times it’s happened in history.
Donald Trump , this year’s presumptive Republican presidential nominee, has called collapsing fertility a bigger threat to Western civilization than Russia. A year ago Japanese Prime Minister Fumio Kishida declared that the collapse of the country’s birthrate left it “standing on the verge of whether we can continue to function as a society.” Italian Prime Minister Giorgia Meloni has prioritized raising the country’s “demographic GDP.”
Governments have rolled out programs to stop the decline—but so far they’ve barely made a dent.
Demographic surprise
In 2017, when the global fertility rate—a snapshot of how many babies a woman is expected to have over her lifetime—was 2.5, the United Nations thought it would slip to 2.4 in the late 2020s. Yet by 2021, the U.N. concluded, it was already down to 2.3—close to what demographers consider the global replacement rate of about 2.2. The replacement rate, which keeps population stable over time, is 2.1 in rich countries, and slightly higher in developing countries, where fewer girls than boys are born and more mothers die during their childbearing years.
While the U.N. has yet to publish estimated fertility rates for 2022 and 2023, Fernández-Villaverde has produced his own estimate by supplementing U.N. projections with actual data for those years covering roughly half the world’s population. He has found that national birth registries are typically reporting births 10% to 20% below what the U.N. projected.
China reported 9 million births last year , 16% less than projected in the U.N.’s central scenario. In the U.S., 3.59 million babies were born last year, 4% less than the U.N. projected. In other countries, the undershoot is even larger: Egypt reported 17% fewer births last year. In 2022, Kenya reported 18% fewer.
Fernández-Villaverde estimates global fertility fell to between 2.1 and 2.2 last year, which he said would be below global replacement for the first time in human history. Dean Spears, a population economist at the University of Texas at Austin, said while the data isn’t good enough to know precisely when or if fertility has fallen below replacement, “we have enough evidence to be quite confident about…the crossing point not being far off.”
In 2017 the U.N. projected world population, then 7.6 billion, would keep climbing to 11.2 billion in 2100. By 2022 it had lowered and brought forward the peak to 10.4 billion in the 2080s. That, too, is likely out of date. The Institute for Health Metrics and Evaluation at the University of Washington now thinks it will peak around 9.5 billion in 2061 then start declining.

In the U.S., a short-lived pandemic baby boomlet has reversed. The total fertility rate fell to 1.62 last year, according to provisional government figures, the lowest on record .
Had fertility stayed near 2.1, where it stood in 2007, the U.S. would have welcomed an estimated 10.6 million more babies since, according to Kenneth Johnson, senior demographer at the University of New Hampshire.
In 2017, when the fertility rate was 1.8, the Census Bureau projected it would converge over the long run to 2.0. It has since revised that down to 1.5. “It has snuck up on us,” said Melissa Kearney, an economist at the University of Maryland specialising in demographics.
A second demographic transition?
Historians refer to the decline in fertility that began in the 18th century in industrialising countries as the demographic transition. As lifespans lengthened and more children survived to adulthood, the impetus for bearing more children declined. As women became better educated and joined the workforce, they delayed marriage and childbirth, resulting in fewer children.
Now, said Spears, “the big-picture fact is that birthrates are low or are falling in many diverse societies and economies.”
Some demographers see this as part of a “second demographic transition,” a society-wide reorientation toward individualism that puts less emphasis on marriage and parenthood, and makes fewer or no children more acceptable.

In the U.S., some thought at first that women were simply delaying childbirth because of lingering economic uncertainty from the 2008 financial crisis.
In research published in 2021 , the University of Maryland’s Kearney and two co-authors looked for possible explanations for the continued drop. They found that state-level differences in parental abortion notification laws, unemployment, Medicaid availability, housing costs, contraceptive usage, religiosity, child-care costs and student debt could explain almost none of the decline. “We suspect that this shift reflects broad societal changes that are hard to measure or quantify,” they conclude.
Kearney said while raising children is no more expensive than before, parents’ preferences and perceived constraints have changed: “If people have a preference for spending time building a career, on leisure, relationships outside the home, that’s more likely to come in conflict with childbearing.”
Meanwhile, time-use data show that mothers and fathers, especially those that are highly educated, spend more time with their children than in the past. “The intensity of parenting is a constraint,” Kearney said.
Erica Pittman, a 45-year-old business banker in Raleigh, N.C., said she and her husband opted to have only one child because of demands on their time, including caring for her mother, who died last year after a long battle with multiple sclerosis. Their 8-year-old son is able to participate in theatre workshops, soccer and summer camps because the couple, with a combined income of about $225,000 a year, has more time and money.
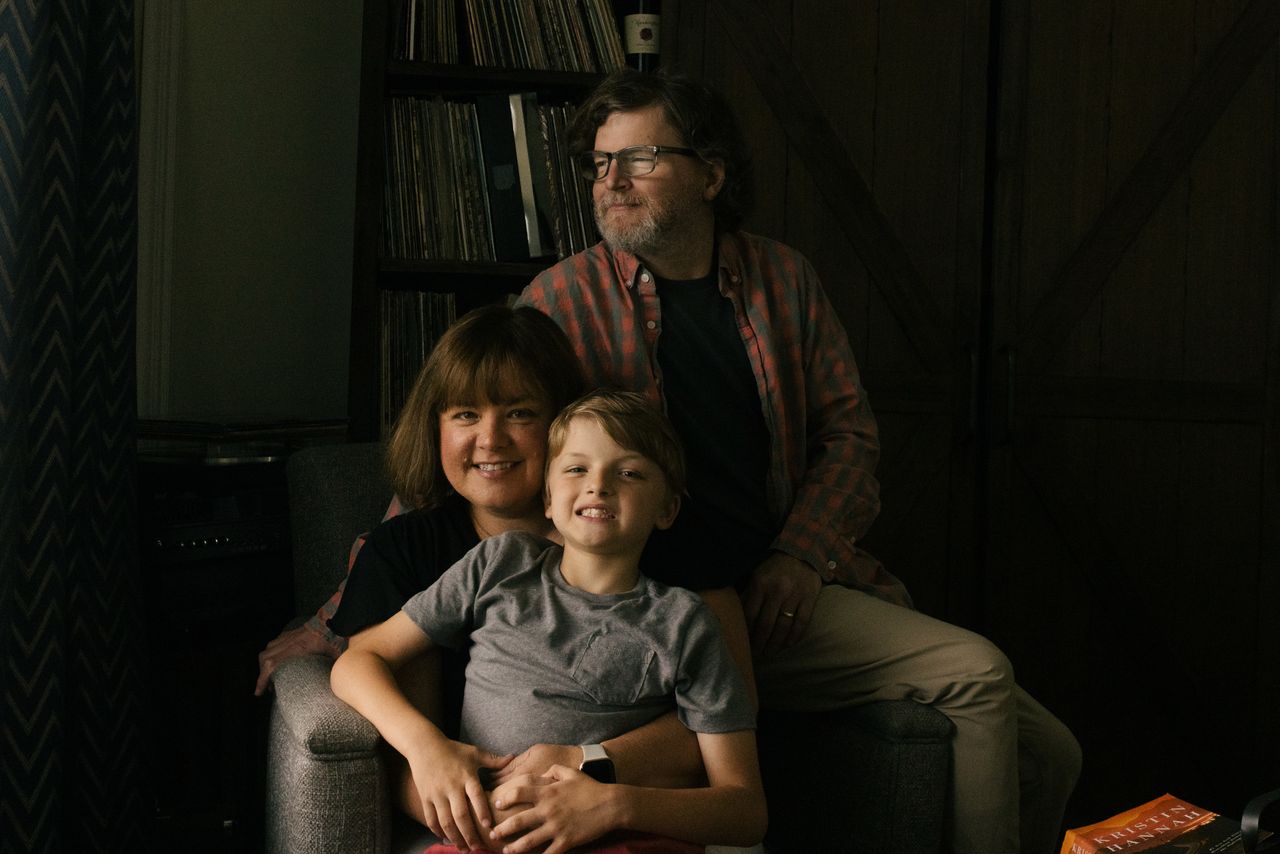
“I feel like a better mom,” Pittman said. “I feel like I can go to work—because I have a fairly demanding job—but I can also make time to volunteer at his school, be the chaperone for the field trip and do those kinds of things, because I only have one to coordinate with my schedule.”
Pittman said she only questions their decision when her son says he wishes he had a sibling to play with. In response, she and her husband, a middle-school history teacher, pick vacation destinations with a kids’ club, such as a Disney cruise, so her son can play with others his age.
‘Plugged into the global culture’
Fertility is below replacement in India even though the country is still poor and many women don’t work —factors that usually sustain fertility.
Urbanisation and the internet have given even women in traditional male-dominated villages a glimpse of societies where fewer children and a higher quality of life are the norm. “People are plugged into the global culture,” said Richard Jackson, president of the Global Aging Institute, a nonprofit research and education group.
Mae Mariyam Thomas, 38, who lives in Mumbai and runs an audio production company, said she’s opted against having children because she never felt the tug of motherhood. She sees peers struggling to meet the right person, getting married later and, in some instances, divorcing before they have kids. At least three of her friends have frozen their eggs, she said.
“I think now we live in a really different world, so I think for anyone in the world it’s tough to find a partner,” she said.
Sub-Saharan Africa once appeared resistant to the global slide in fertility, but that too is changing. The share of all women of reproductive age using modern contraception grew from 17% in 2012 to 23% in 2022, according to Family Planning 2030, an international organisation.
Jose Rimon, a professor of public health at Johns Hopkins University, credits that to a push by national leaders in Africa which, he predicted, would drive fertility down faster than the U.N. projects.
Once a low fertility cycle kicks in, it effectively resets a society’s norms and is thus hard to break, said Jackson. “The fewer children you see your colleagues and peers and neighbours having, it changes the whole social climate,” he said.
Danielle Vermeer grew up third in a family of four children on Chicago’s North Side, where her neighbourhood was filled with Catholics of Italian, Irish and Polish descent and half her close friends had as many siblings as her or more. Her Italian-American father was one of four children who produced 14 grandchildren. Now her parents have five grandchildren, including Vermeer’s two children, ages 4 and 7.
The 35-year-old, who is the co-founder of a fashion thrifting app, said that before setting out to have children, she consulted dozens of other couples and her Catholic church and read at least eight books on the subject, including one by Pope Paul VI. She and her husband settled on two as the right number.
“The act of bringing a child into this world is an incredible responsibility,” she said.
New policies
Governments have tried to reverse the fall in fertility with pro natalist policies.
Perhaps no country has been trying longer than Japan. After fertility fell to 1.5 in the early 1990s, the government rolled out a succession of plans that included parental leave and subsidised child care. Fertility kept falling.
In 2005, Kuniko Inoguchi was appointed the country’s first minister responsible for gender equality and birthrate. The main obstacle, she declared, was money: People couldn’t afford to get married or have children. Japan made hospital maternity care free and introduced a stipend paid upon birth of the child.
Japan’s fertility rate climbed from 1.26 in 2005 to 1.45 in 2015. But then it started declining again, and in 2022 was back to 1.26.
This year, Prime Minister Fumio Kishida rolled out yet another program to increase births that extends monthly allowances to all children under 18 regardless of income, free college for families with three children, and fully paid parental leave.
Inoguchi, now a member of parliament’s upper house, said the constraint on would-be parents is no longer money, but time. She has pressed the government and businesses to adopt a four-day workweek. She said, “If you’re a government official or manager of a big corporation, you should not worry over questions of salary now, but that in 20 years time you will have no customers, no clients, no applicants to the Self-Defense Forces.”
Hungarian Prime Minister Viktor Orban has pushed one of Europe’s most ambitious natality agendas. Last year he expanded tax benefits for mothers so that women under the age of 30 who have a child are exempt from paying personal income tax for life. That’s on top of housing and child-care subsidies as well as generous maternity leaves.
Hungary’s fertility rate, though still well below replacement, has risen since 2010. But the Vienna Institute of Demography attributed this primarily to women delaying childbirth because of a debt crisis that hit around 2010. Adjusted for that, fertility has risen only slightly, it concluded.
In the U.S., while state and federal legislators have pushed to expand child-care subsidies and parental leave, they have generally not set a higher birthrate as an explicit goal. Some Republicans, though, are leaning in that direction. Last year, Trump said he backed paying out “baby bonuses” to prop up U.S. births, and GOP Arizona Senate candidate Kari Lake recently endorsed the idea.
Republican Sen. J.D. Vance of Ohio said falling fertility matters beyond the economic pressures of a smaller labor force and unfunded Social Security. “Do you live in communities where there are smiling happy children, or where people are just ageing?” he said in an interview. Lack of siblings and cousins, he said, contributes to children’s social isolation.
He’s studied potential solutions, in particular Hungary’s approach, but hasn’t seen proof of anything that works over the long term.
The Institute for Health Metrics and Evaluation found little evidence that pronatalist policies lead to sustained rebounds in fertility. A woman may get pregnant sooner to capture a baby bonus, researchers say, but likely won’t have more kids over the course of her lifetime.
Economic pressure
With no reversal in birthrates in sight, the attendant economic pressures are intensifying. Since the pandemic, labor shortages have become endemic throughout developed countries. That will only worsen in coming years as the postcrisis fall in birthrates yields an ever-shrinking inflow of young workers, placing more strain on healthcare and retirement systems.
Neil Howe , a demographer at Hedgeye Risk Management, has pointed to a recent World Bank report suggesting that worsening demographics could make this a second consecutive “lost decade” for global economic growth.
The usual prescription in advanced countries is more immigration, but that has two problems. As more countries confront stagnant population, immigration between them is a zero-sum game. Historically, host countries have sought skilled migrants who enter through formal, legal channels, but recent inflows have been predominantly unskilled migrants often entering illegally and claiming asylum.
High levels of immigration have also historically aroused political resistance, often over concerns about cultural and demographic change. A shrinking native-born population is likely to intensify such concerns. Many of the leaders keenest to raise birthrates are most resistant to immigration.
As birthrates fall, more regions and communities experience depopulation, with consequences ranging from closed schools to stagnant property values. Less selective colleges will soon struggle to fill classrooms because of the plunge in birthrates that began in 2007, said Fernández-Villaverde. Vance said rural hospitals can’t stay open because of the falling local population.
An economy with fewer children will struggle to finance pensions and healthcare for growing ranks of elderly. South Korea’s national pension fund, one of the world’s largest, is on track to be depleted by 2055. A special legislative committee recently presented several possible pension reforms, but there’s only a short window to act before the next presidential election campaign heats up.
There’s been little public pressure to act, said Sok Chul Hong, an economist at Seoul National University. “The elderly are not very interested in pension reform, and the youth are apathetic towards politics,” he said. “It is truly an ironic situation.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Formula 1 may be the world’s most glamorous sport, but for Oscar Piastri, it’s also one of the most lucrative. At just 24, Australia’s highest-paid athlete is earning more than US$40 million a year.
A record-breaking $11 million sale at The Centennial Collection has set a new benchmark for luxury apartment living in Bondi Junction.