The Loneliness of the American Worker
More meetings and faceless chats. Fewer work friends. How the modern workday is fueling an epidemic of isolation.

 6 min
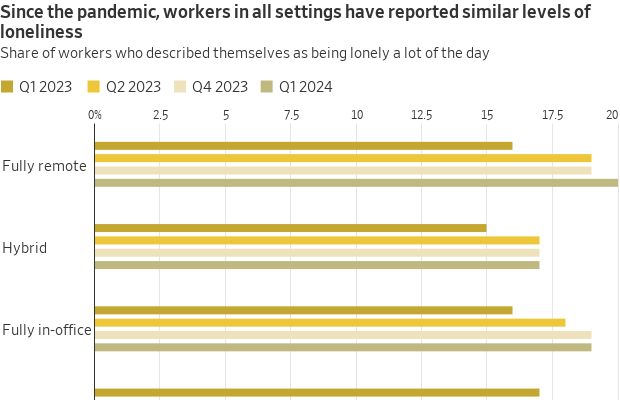
More Americans are profoundly lonely, and the way they work—more digitally linked but less personally connected—is deepening that sense of isolation.
Nick Skarda , 29 years old, works two jobs in logistics and office administration in San Diego to keep up with his bills. After a couple of years at the logistics job, he has one friend there. He says hi to co-workers at his office job but doesn’t really know any.
“I feel sort of an emptiness or lack of belonging,” he says. Juggling two jobs leaves Skarda exhausted, with little energy or time to grab drinks with co-workers . “It makes it harder to go in and give it your all if you don’t feel like anyone is there rooting for you,” he adds.
Employers and researchers are just beginning to understand how workplace shifts over the past four years are contributing to what the U.S. surgeon general declared a loneliness health epidemic last year. The alienation affects remote and in-person workers alike. Among 1-800-Flowers.com ’s 5,000 hybrid and fully on-site employees, for instance, the most popular community chat group offered by a company mental-health provider is simply called “Loneliness.”
Consider these phenomena of modern work:
It is a marked shift from even a decade ago, when bonds fostered at work helped compensate for declining participation in church , community groups and other social institutions. As the American workday becomes more faceless and scheduled , the number of U.S. adults who call themselves lonely has climbed to 58% from 46% in 2018, according to a recent Cigna poll of 10,000 Americans.
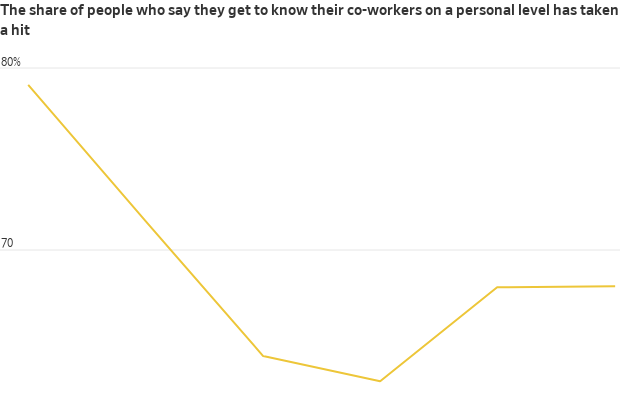
The faceless workday
The disconnection is driving up staff turnover and worker absences, making it a business issue for more employers, executives and researchers say. Cigna, the health-insurance company, estimates that loneliness is costing companies $154 billion a year in absenteeism alone.
“Work is social, it’s a lot more than a paycheck,” says James McCann , founder and chairman of 1-800-Flowers.com.
Earlier this year, 1-800-Flowers.com moved from three days in the office to four to boost a sense of connectivity among workers. It has also begun tapping workers across teams to serve as designated hosts during lunchtime, encouraging people to sit with colleagues they don’t know in common areas and chat, and suggesting conversation topics.
While today’s workers have more ways to connect than ever, “there are only so many memes and jokes you can send over Slack,” says Maëlle Gavet , chief executive of Techstars, a pre-seed fund that has invested in 4,100 startups. “We tend to have more and more people with back-to-back calendars, more meetings and less connections.”
Gavet says that is especially the case for hybrid workers on in-office days, which they tend to use to dash from one meeting to the next.
Paradoxically, meetings can make people feel lonelier—and even more so if the meetings are virtual, behavioural researchers say. A 2023 survey by employee experience and analytics company Perceptyx found people who described themselves as “very lonely” tended to have heavier meeting loads than less-lonely staffers. More than 40% of those people spent more than half their work hours in meetings.
In Cincinnati, Kelly Roehm says she came to chafe at the meetings—sometimes as many as 12—consuming her day after joining a consulting company in 2021. She would often feel her eyes glazing over as she multitasked on other screens.
“It’s like you’re a zombie, there but not there,” says Roehm, who lived 10 minutes from the office but worked mostly remotely because she says few colleagues typically came in. It is a more common setup as companies distribute teams across more locations: At Microsoft , 27% of the company’s teams all worked in the same location last year, compared with 61% in 2019.
She compares that experience with her time more than a decade ago at a company now owned by AstraZeneca . There, she enjoyed lots of social outlets at work: a Weight Watchers group and a lunchtime crochet club.
“Now if I were to think about asking, ‘Hey, do you want to participate in something like this,’ it would just sound weird,” says Roehm, who left this year to focus on her own career-consulting business. “There wasn’t that emotional attachment that made it difficult to say, it’s time to move on.”
The power of small talk
Office chitchat, sometimes an unwanted distraction, seems to provide more benefits than many people realise, says Jessica Methot , an associate professor at Rutgers University who studies social ties at work.
In a study of 100 employees at different workplaces, Methot and fellow researchers surveyed participants at points throughout the day. They found those who had engaged in small talk reported less stress and more positivity toward co-workers.
Even exchanging pleasantries with a co-worker you barely know can help, says Sarah Wright , an associate professor at New Zealand’s University of Canterbury who studies worker loneliness.
“We used to think loneliness has to be overcome by developing meaningful relationships and having that degree of intimacy,” Wright says. “More and more, though, we’re seeing it’s these day-to-day weak ties and frequency of [interactions] with people that matters.”
Such interactions are substantially harder to replicate in a virtual environment. “The default now is, I have to schedule time with you, even if it’s five minutes, instead of just picking up the phone,” says Katie Tyson , president of Hive Brands, an online food retailer founded in 2020 as a fully remote company.
The frictions add up, she says. Last fall, the company added an office in New York where employees voluntarily gather a couple of times a week to foster more cohesion.
Coming to the office, even on a hybrid basis, tends to yield a roughly 20% to 30% boost in serendipitous connections, according to Syndezo, which analysed survey data and email and messaging traffic from more than two dozen large companies.
Yet there are diminishing returns to time in person, says Philip Arkcoll , founder of Worklytics, which analyses workforce data for Fortune 500 companies. Coming in once a month provides a significant boost in ties; two or three times a month adds a little more, Worklytics data show. Once or twice a week results in a smaller increase, though, and working in-person four or five days a week makes almost no difference.
A business priority
Ernst & Young has asked managers to use the first five minutes of team calls to engage in conversation “as real human beings,” says Frank Giampietro , whose title, chief well-being officer for the Americas, was created in 2021 to help support employees during the pandemic.
The professional-services firm is also training employees to spot and reach out to co-workers struggling with issues such as isolation. To date, more than 1,600 employees have taken the training.
One challenge is that American workers have sacrificed connection for productivity, says Julie Rice , co-founder of fitness chain SoulCycle. These days, with more business contacts preferring video calls, she finds breakfast meetings and coffee dates on her calendar have been replaced with Zoom. Though efficient, such video calls are less likely to yield conversations that can turn into useful professional connections or lasting friendships, she says.
“Even people I’m meeting with here in New York, we’ll just Zoom,” she says.
Last year, Rice co-founded Peoplehood, a company that runs “gathers” to improve connectivity and relationship skills, and employers are signing up. One, a beauty-services business with hundreds of field employees who never see each other, asked Peoplehood to host a series of gatherings for workers to meet and share job advice. Another, a marketing company with far-flung employees, requested help after surveys showed staff wanted to feel more connected.
“Whatever relationships we had pre-Covid have sort of run out of gas,” Rice says.
Good luck prodding employees to socialise, though. Nearly all the 150-odd staff at the Pleasanton, Calif., headquarters of Shaklee, the nutrition-supplements company, used to attend annual Earth Day gatherings, which involved community service, lunch and breaking early for the day, says Jonathan Ramot , the company’s North American human-resources director. Office happy hours, bowling outings and “mix and mingles” were also robustly attended.
Now that the workforce has gone remote, last year’s Earth Day event attracted 20 staffers, even though most workers live nearby.
“We have a lot of people asking for in-person events, but when we plan them, they don’t show up,” Ramot says. “Then they complain they’re lonely.”
This past April, Shaklee instead held a mandatory get-together with the chief executive, who had relocated to Florida during the pandemic and was in town. About 100 employees gathered at a brewery for food, drinks and conversation—and no speeches from the bosses.
There was a buzz in the air, Ramot says, as staff hugged and delighted in seeing each other, some for the first time. “People were saying, I miss this,” he says.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Australian shares finished higher on Tuesday, September 22, as a technology rally and lower oil prices outweighed weakness in energy companies and continued anxiety about domestic interest rates. The S&P/ASX 200 closed 25.9 points, or 0.30 per cent, higher at 8,757.8. The All Ordinaries gained 0.36 per cent to 8,951.0, while the All Technology index …
Continue reading “ASX Wrap: Technology lifts the ASX as falling oil relieves inflation pressure”

From elevated skincare to handcrafted home pieces, this year’s most thoughtful gifts go beyond the expected.