The Middle East Becomes the World’s ATM
Flush with cash from an energy boom, Saudi Arabia and other Gulf monarchies have a moment on the world’s financial stage

 5 min
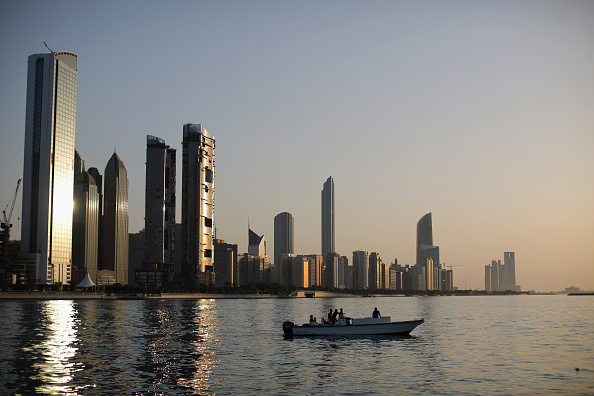
Five years ago, Saudi officials watched a wave of American finance executives pull out of a free investment confab in Riyadh after the murder of a dissident journalist made the kingdom a toxic place to do business.
This year, the conference, nicknamed “Davos in the Desert,” is expecting so much demand it is charging executives $15,000 a person.
Middle East monarchies eager for global influence are having a moment on the world’s financial stage. They are flush with cash from an energy boom at the very time traditional Western financiers—hampered by rising interest rates—have retreated from deal making and private investing.
The region’s sovereign-wealth funds have become the en vogue ATM for private equity, venture capital and real-estate funds struggling to raise money elsewhere.
The market for marquee mergers and acquisitions has seen a surge of interest from the region. Recently announced deals include an Abu Dhabi fund’s purchase of investment manager Fortress for more than $2 billion and a Saudi fund’s $700 million purchase of global lender Standard Chartered’s aviation unit.
Companies and funds overseen by Abu Dhabi’s national security adviser, Sheikh Tahnoun bin Zayed Al Nahyan, have made runs at buying Standard Chartered and investment bank Lazard. They have also struck recent deals to buy a $1.2 billion U.K. healthcare company and to take partial control of a nearly $6 billion Colombian food giant.
“Now, everybody wants to go to the Middle East—it’s like the gold rush in the U.S. once upon a time,” said Peter Jädersten, founder of fundraising advisory firm Jade Advisors. “It’s difficult to raise money everywhere.”
Fund managers visiting the region say they often wait across from rivals in waiting rooms of sovereign-wealth funds. Silicon Valley and New York managers are a near-constant presence in the white-marble floored lobby of the Four Seasons Abu Dhabi, as with other top hotels, they say.
The Riyadh conference next month—a pet project of Saudi Crown Prince Mohammed bin Salman known as the Future Investment Initiative—is expected to be a magnet for money hunters. In 2018, Wall Street executives backed out after Saudi operatives murdered journalist Jamal Khashoggi, and for years many startups and funds said they avoided investment from the country over moral concerns.
Some companies continue to steer clear of the kingdom, while human-rights groups say its record on treatment of government dissidents remains a serious problem.
But Saudi funding became more in demand last year when other money began to get tight. At last year’s conference the Public Investment Fund’s chief, Yasir Al Rumayyan, sat on a panel discussion with two of the world’s biggest investment-firm executives, Blackstone’s Stephen Schwarzman and Ray Dalio, founder of Bridgewater Associates. Top names in venture capital mixed on the floor, and FTX chief Sam Bankman Fried looked for funding.
Ben Horowitz, partner at Andreessen Horowitz, said at a PIF-sponsored conference this spring that Saudi Arabia was a “startup country,” and referred to Prince Mohammed as its “founder” who was creating a new culture and new vision for the country.
The region’s new dominance is most apparent among private funds, the type that lock up investors’ money for years. While detailed statistics are scarce, figures at two of the biggest sovereign funds suggest a surge. At Saudi’s PIF, commitments for “investment securities”—a category that includes private funds—rose to $56 billion in 2022, up from $33 billion a year earlier. Abu Dhabi’s Mubadala reported that equity commitments doubled to $18 billion in 2022.
Executives at private-equity giants TPG, KKR and Carlyle Group have told investors that interest from the Middle East remains strong while other parts of the world recede.
“If you’re in the U.S., there’s a certain degree of concern,” Carlyle CEO Harvey Schwartz said at a June conference. Middle East investors, he said, are “very front-footed, very dynamic.”
While the Middle East steps on the gas, the traditional backers of investment funds—pension plans and college endowments—are in retreat. The global shift to higher interest rates caused losses in the biggest parts of their portfolios—especially stocks and bonds.
Investors put $33 billion toward U.S.-based venture capital funds in the first half of 2023, less than half the $74 billion in the same period in 2021, according to PitchBook. Global fundraising for all private funds fell 10% last year to $1.5 trillion, according to Preqin—a decline many expect to continue.
“Fundraising has become much, much harder over the past 12 months,” said Brenda Rainey, an executive vice president at Bain & Co. who advises private-equity funds.
The reason for the region’s burst of funding and deal making is twofold.
Higher energy prices—a byproduct of Russia’s invasion of Ukraine—have given the region’s oil- and gas-dependent wealth funds tens of billions of dollars of extra money to spend. That means a drop in oil prices could quickly cause a pullback from the Gulf countries, as has happened in energy booms-turned-bust of the past.
At the same time, Saudi Prince Mohammed and top officials in the U.A.E. have jostled for greater sway on the world stage—in geopolitics, finance and sports—pumping additional money into their wealth funds to do deals and expand industry at home.
The intersection of politics and finance in the region has led Gulf wealth funds from Saudi Arabia, the U.A.E. and Qatar to be the main financial backers of two key Trump administration figures: Jared Kushner and former Treasury Secretary Steven Mnuchin, who together raised billions of dollars from the region.
Gulf funds have pushed their U.S. peers to open offices in the region to more easily win investments, fund managers say.
BlackRock has said it would create a team on the ground in Riyadh dedicated to boosting investment into infrastructure projects in the Gulf.
Millennium Management LLC, based in New York, set up an office in Dubai in 2020 and others followed, including private-equity firm CVC Capital Partners and ExodusPoint Capital Management, the largest-ever hedge-fund startup with $8 billion in initial capital. Europe’s Tikehau Capital and Ardian both established teams in Abu Dhabi, and U.S. alternative investment manager, Pretium, hired a local industry veteran from Dubai.
Dalio also set up an office in Abu Dhabi for the Dalio Family Office, his personal venture. Rajeev Misra, a longtime financier for SoftBank Group who secured over $6 billion in commitments for a new venture from multiple Abu Dhabi-aligned investment funds, is moving to the U.A.E. from the U.K., according to people familiar with his plans.
There is now an “awareness that relationships have to be built and that doesn’t happen overnight,” said Joseph Morris, a Dubai-based managing director at U.S.-based advisory firm Newmark Group.
The venture capital arm of Tiger Global has struggled to raise its latest fund, repeatedly cutting its target by billions of dollars. Stung by losses and the cooler fundraising environment, many U.S. investors have given it the cold shoulder, investors say.
One place it found success: Saudi Arabia. A division of PIF, Sanabil, this spring added Tiger’s name to the public list of fund managers it backs. Others on the list include Peter Thiel’s Founders Fund and Andreessen Horowitz.
Ibrahim Ajami, who oversees startup investments at Abu Dhabi state fund Mubadala, which invests in companies as well as funds, said the environment gives Mubadala the ability to be “very thoughtful and selective” about who it backs.
He can negotiate terms that let Mubadala buy a stake in the fund manager itself, he said, or allow it to invest alongside others.
“What we are doing is going deeper—and more concentrated and more engaged—with a select group of managers,” he said.
—Summer Said and Berber Jin contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
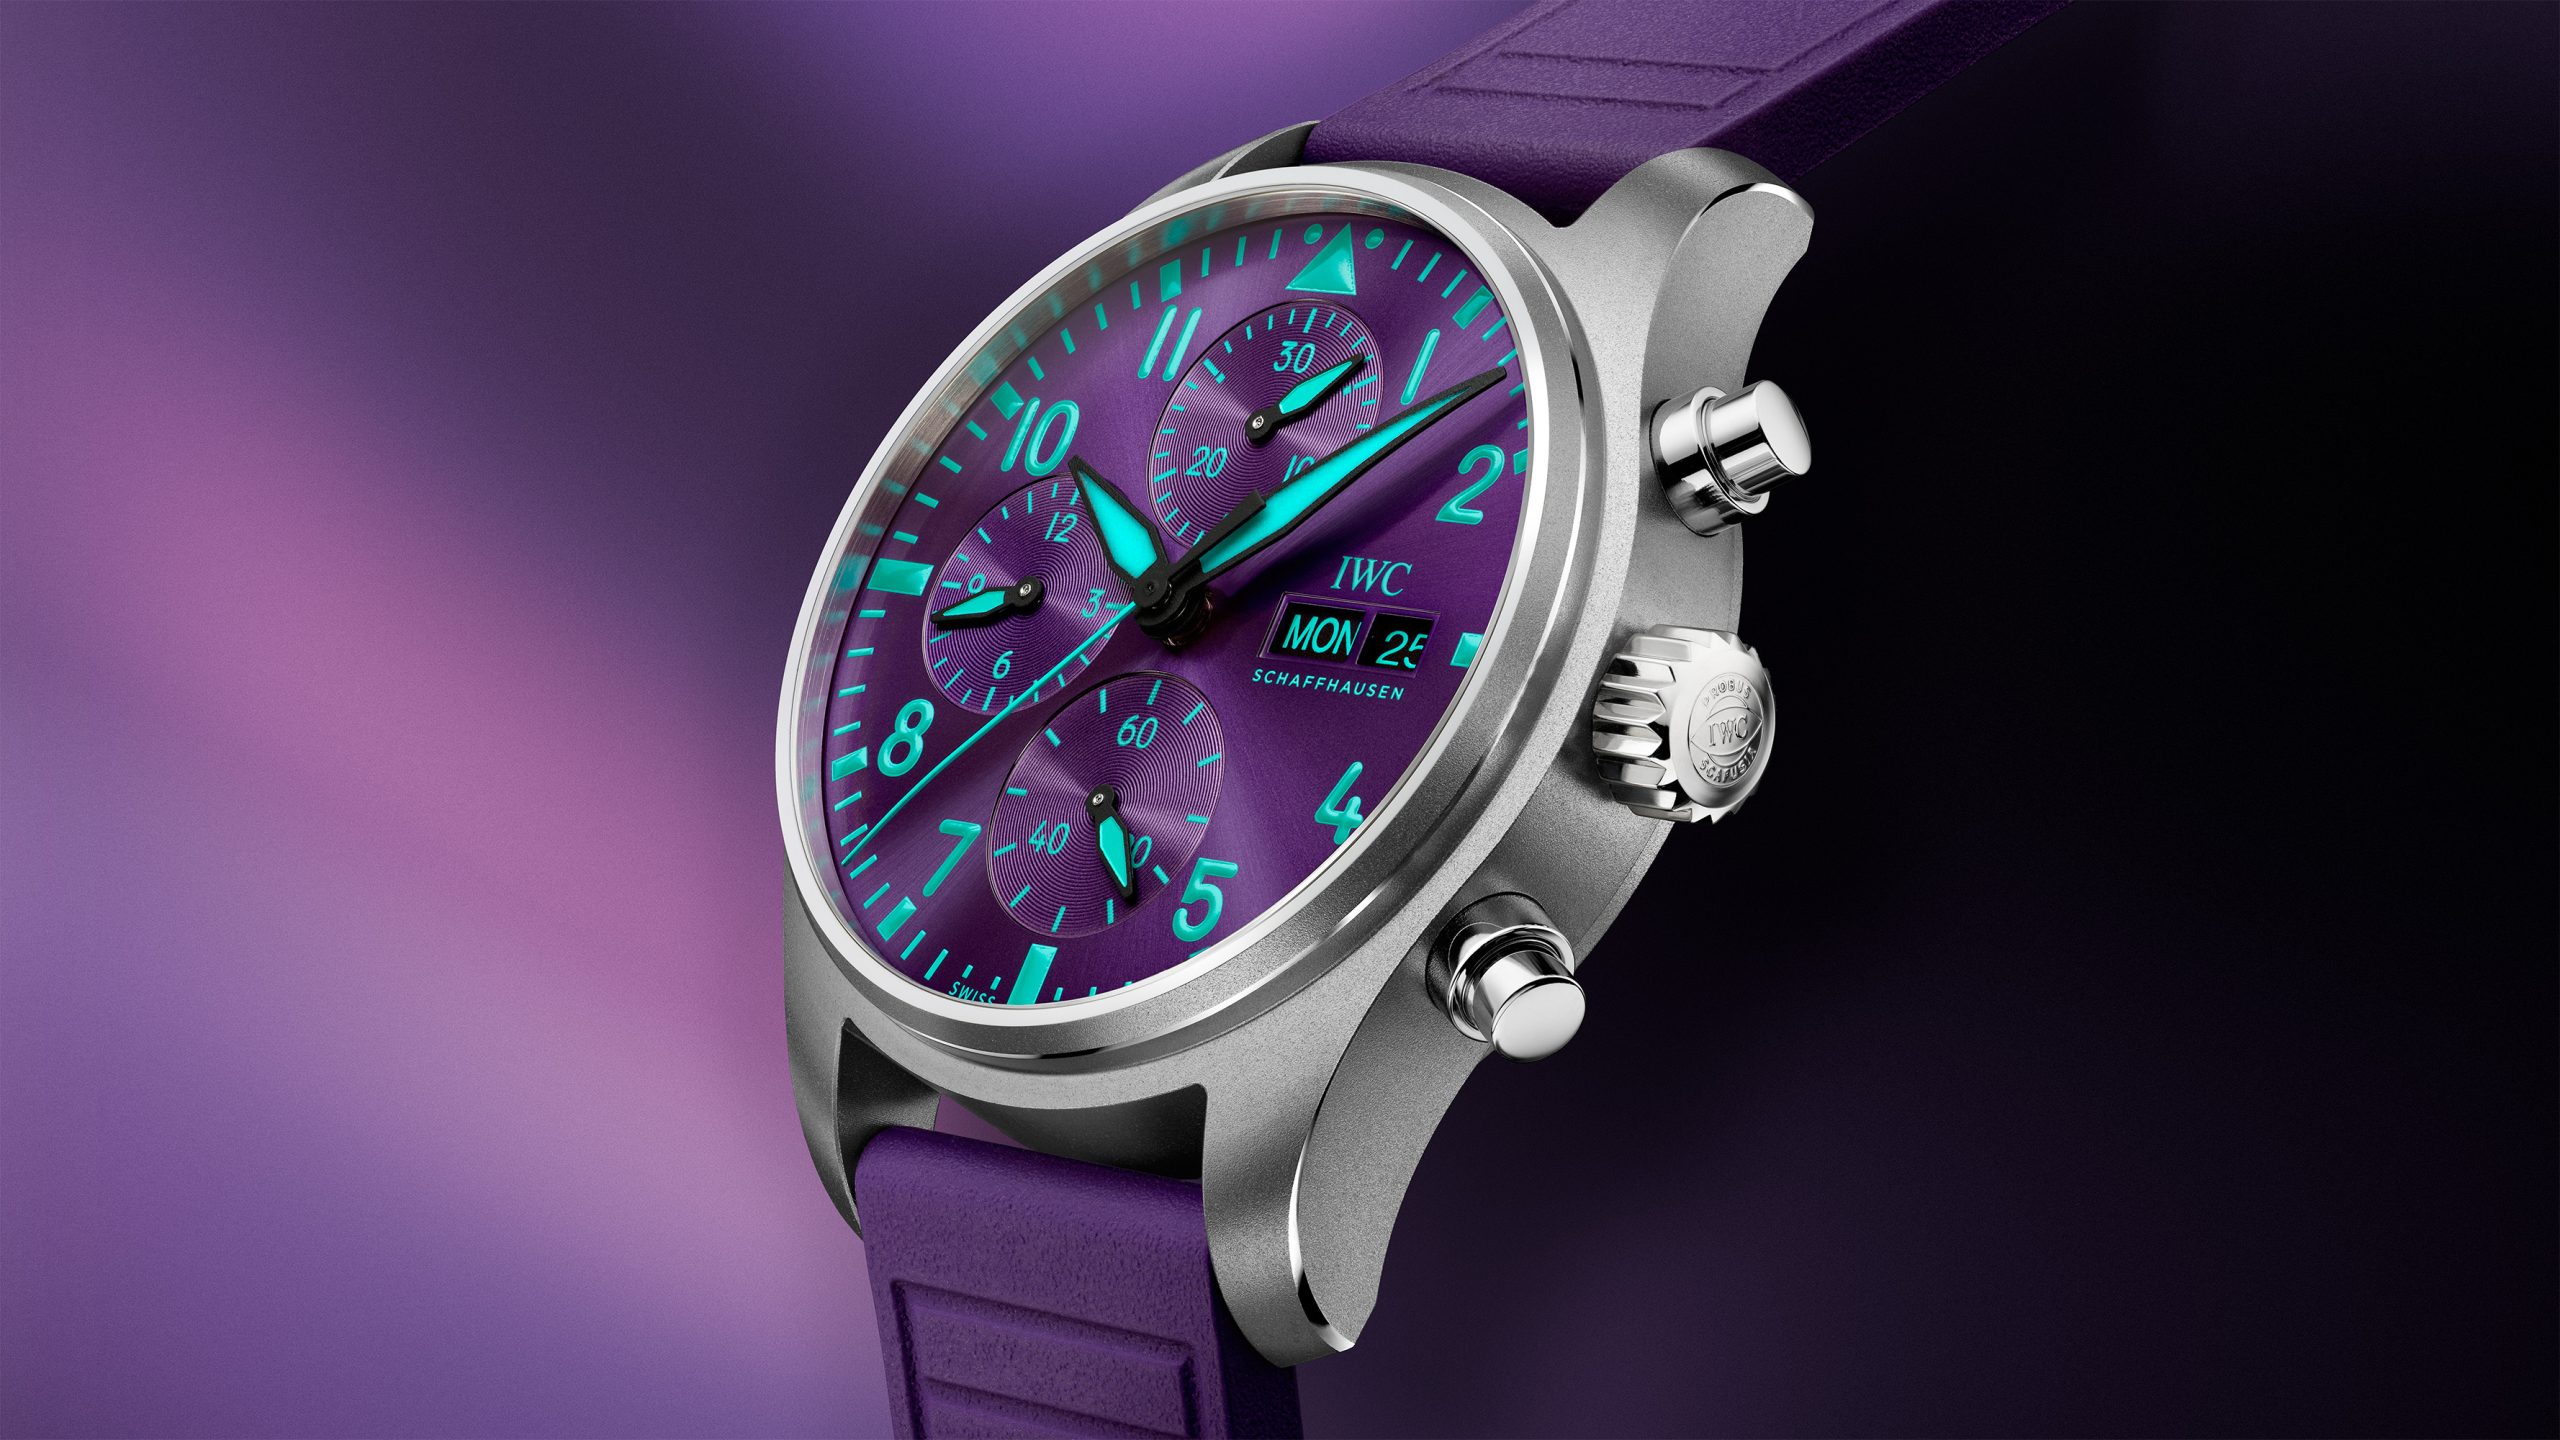
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”
BMW has unveiled the Neue Klasse in Munich, marking its biggest investment to date and a new era of electrification, digitalisation and sustainable design.