Try Hard, but Not That Hard. 85% Is the Magic Number for Productivity.
To do the best work of your life, take it down a notch

 4 min
Are you giving it your all? Maybe that’s too much.
So many of us were raised in the gospel of hard work and max effort, taught that what we put in was what we got out. Now, some coaches and corporate leaders have a new message. To be at your best, dial it back a bit.
Trying to run at top speed will actually lead to slower running times, they say, citing fitness research. Lifting heavy weights until you absolutely can’t anymore won’t spark more muscle gain than stopping a little sooner, one exercise physiologist assured me.
The trick—be it in exercise, or anything—is to try for 85%. Aiming for perfection often makes us feel awful, burns us out and backfires. Instead, count the fact that you hit eight out of 10 of your targets this quarter as a win. We don’t need to see our work, health or hobbies as binary objectives, perfected or a total failure.
“I already messed it up,” Sherri Phillips would lament after missing one of her daily personal goals.
Last year, the chief operating officer of a Manhattan photography business began tracking metrics like her sleep quality and cardio time on an elaborate spreadsheet. It was only after she switched to aiming for 85% success over the course of a week that she stuck with her efforts, instead of giving up when she missed a mark.
“It’s a spectrum of success,” she says.
The benefits of doing less
Once upon a time, bosses who preached total optimization might actually achieve it, says Greg McKeown, a business author and podcaster who’s written about why 85% is a sweet spot.
More recently, the available comparison points and choices in our lives have exploded. We read about someone else’s dream job on LinkedIn, watch a mom prepare a perfect lunch for her kid on TikTok, then click over to scroll through thousands of products on Amazon. Constant comparison often means no end result ever feels good enough. Even searching for, say, the best umbrella to buy can become a time-sucking quest.
“We will drain ourselves,” McKeown says. “It’s a bad strategy. It costs too much.”
Test out doing a little less. If you turn in that project without the extra slide deck, “Does anybody care?” McKeown asks. If you make a decision with only 85% of the information in hand, what’s the result? Notice the time you get back for other things.
“There’s a lot of inconsequential stuff that goes into going 100%,” says Steve Magness, an exercise physiologist who coaches executives and athletes on performance. When we care too much, even minutiae starts to seem “like an existential crisis,” he adds.
Sometimes, the harder we try, the worse we get, injuring ourselves or choking under pressure, Magness says. Quit while you’re ahead, and the sense that your whole self-worth isn’t wrapped up in this one moment can actually make you more likely to nail it.
Relaxed confidence
The effortless success so many of us crave often comes from a relaxed confidence and a tolerance for ambiguity.
When economist Krishnamurthy V. Subramanian gave one of his first major addresses to the media as chief economic adviser for the Indian government, he prepared but tried not to overthink it.
“It’s that Goldilocks balance,” says Subramanian, now an executive director at the International Monetary Fund based in Washington, D.C. “85% is not slacking.”
When two of his slides wouldn’t cue up at the last minute, he pushed away his nerves and reminded himself the speech would be OK even if it wasn’t perfect.
“I’ll wing it,” he told himself calmly. The presentation went just fine.
Just tough enough
Dialling in on the sweet spot of 85% can help us grow. In a 2019 paper, researchers used machine learning to try to find the ideal difficulty level to learn new things. The neural network they created, meant to mimic the human brain, learned best when it was faced with queries set to 85% difficulty, meaning it got questions right 85% of the time.
If a task is too hard, humans get demotivated, says Bob Wilson, an author of the study and associate professor of psychology and cognitive science at the University of Arizona. “If you never make any errors, you’re 100% accurate, well, you can’t learn from the mistakes.”
Ron Shaich, a founder and former chief executive of restaurant chain Panera, is skeptical of people who hit 100% on bonus targets or sales projections. He wonders if the goals are too low. They should be ambitious enough that you won’t always get there, he says.
Presiding over Panera’s quarterly earnings reports, he’d aim to exceed guidance eight out of 10 times. The same went for big goals at the company.
Now an investor, board member and author of a coming business book that stresses 80% equals success, Shaich is convinced most companies don’t even hit that number.
“They all talk about what they’re going to get done. Then they don’t do it,” he says. Reach 80% and, “you’re doing great.”
Know when to stop
Years ago, as a consultant at Bain, Grace Ueng learned the “80-20 rule.” The idea was to stop once you were 80% complete on a project, she says. That first burst of work often contained the real meat of the project.
Now a leadership coach and strategy consultant, Ueng recently took up piano. She practiced for hours and grimaced when she performed for her music group. Then she started doing more targeted exercises, like tackling small chunks of a piece instead of running through the whole thing again and again.
Before a recent performance, she read a book and went to church instead of putting in extra hours at the piano.
When it was time to perform, she played well—and actually enjoyed it.
“You have to have the wisdom,” she says, “to know when to stop.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
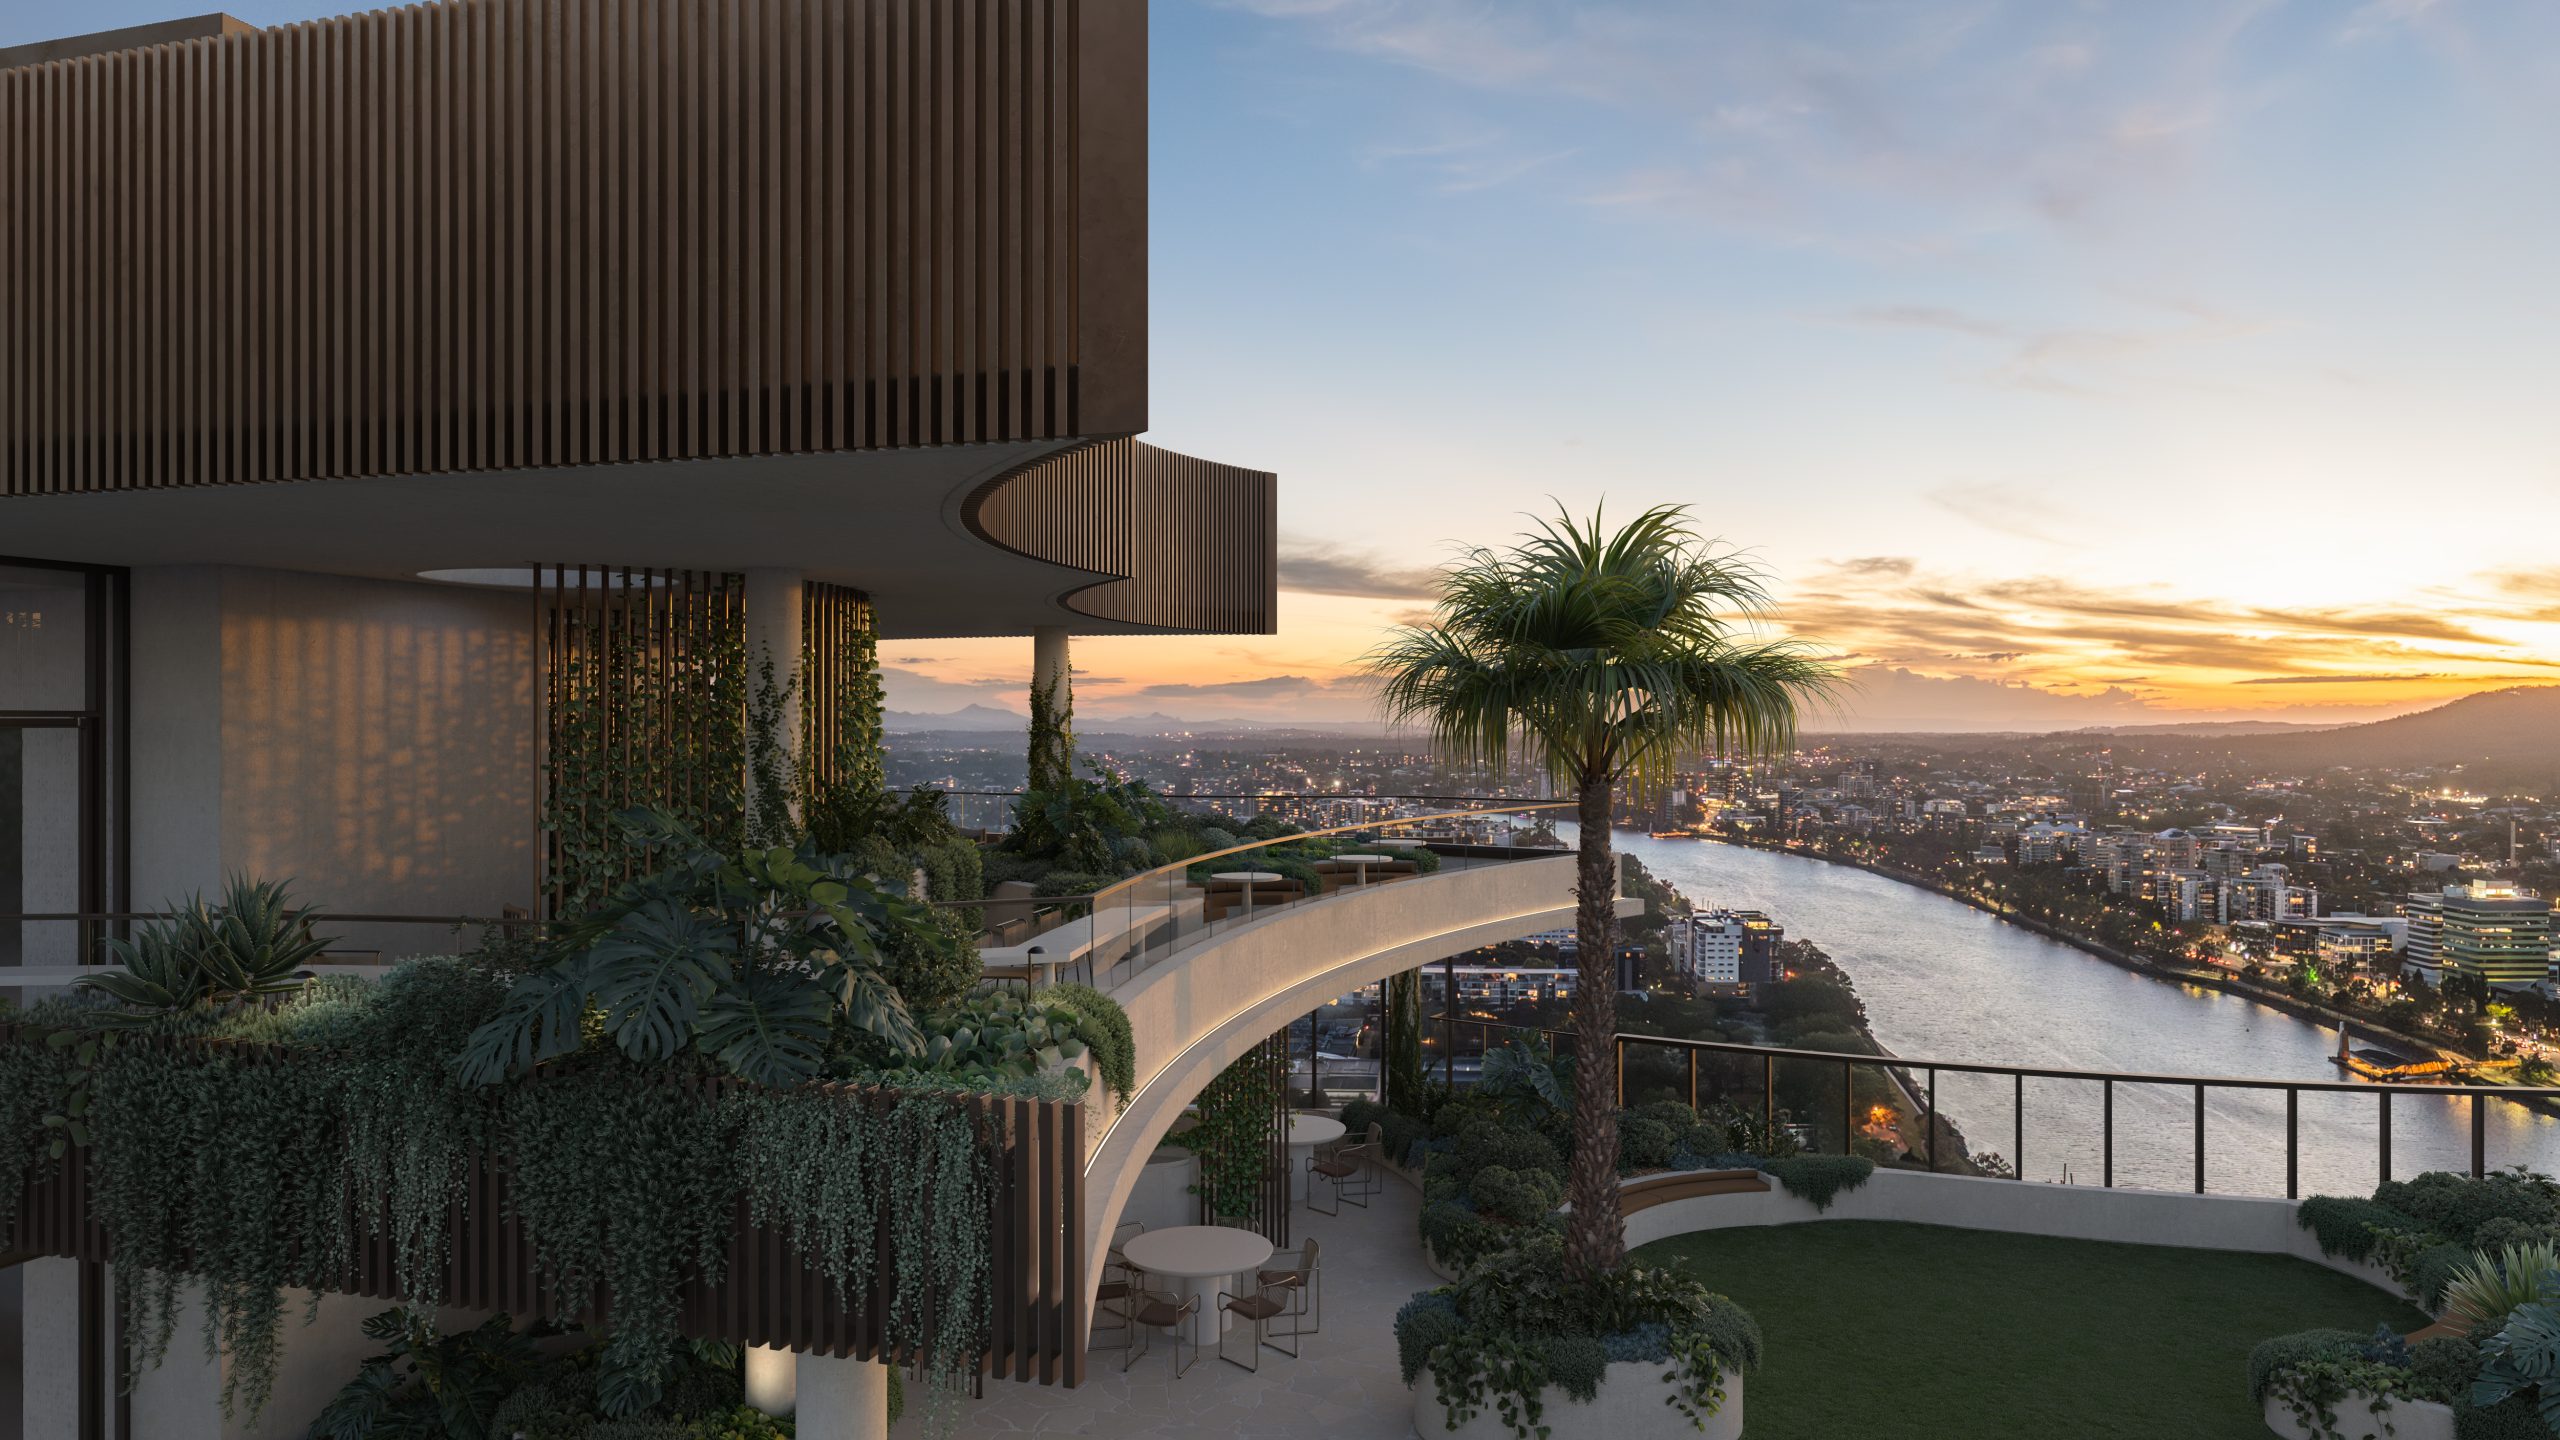
Set on one of the city’s last absolute riverfront sites, The Riversdale by Mosaic combines irreplaceable waterfront ownership with one of Brisbane’s most significant residential opportunities.
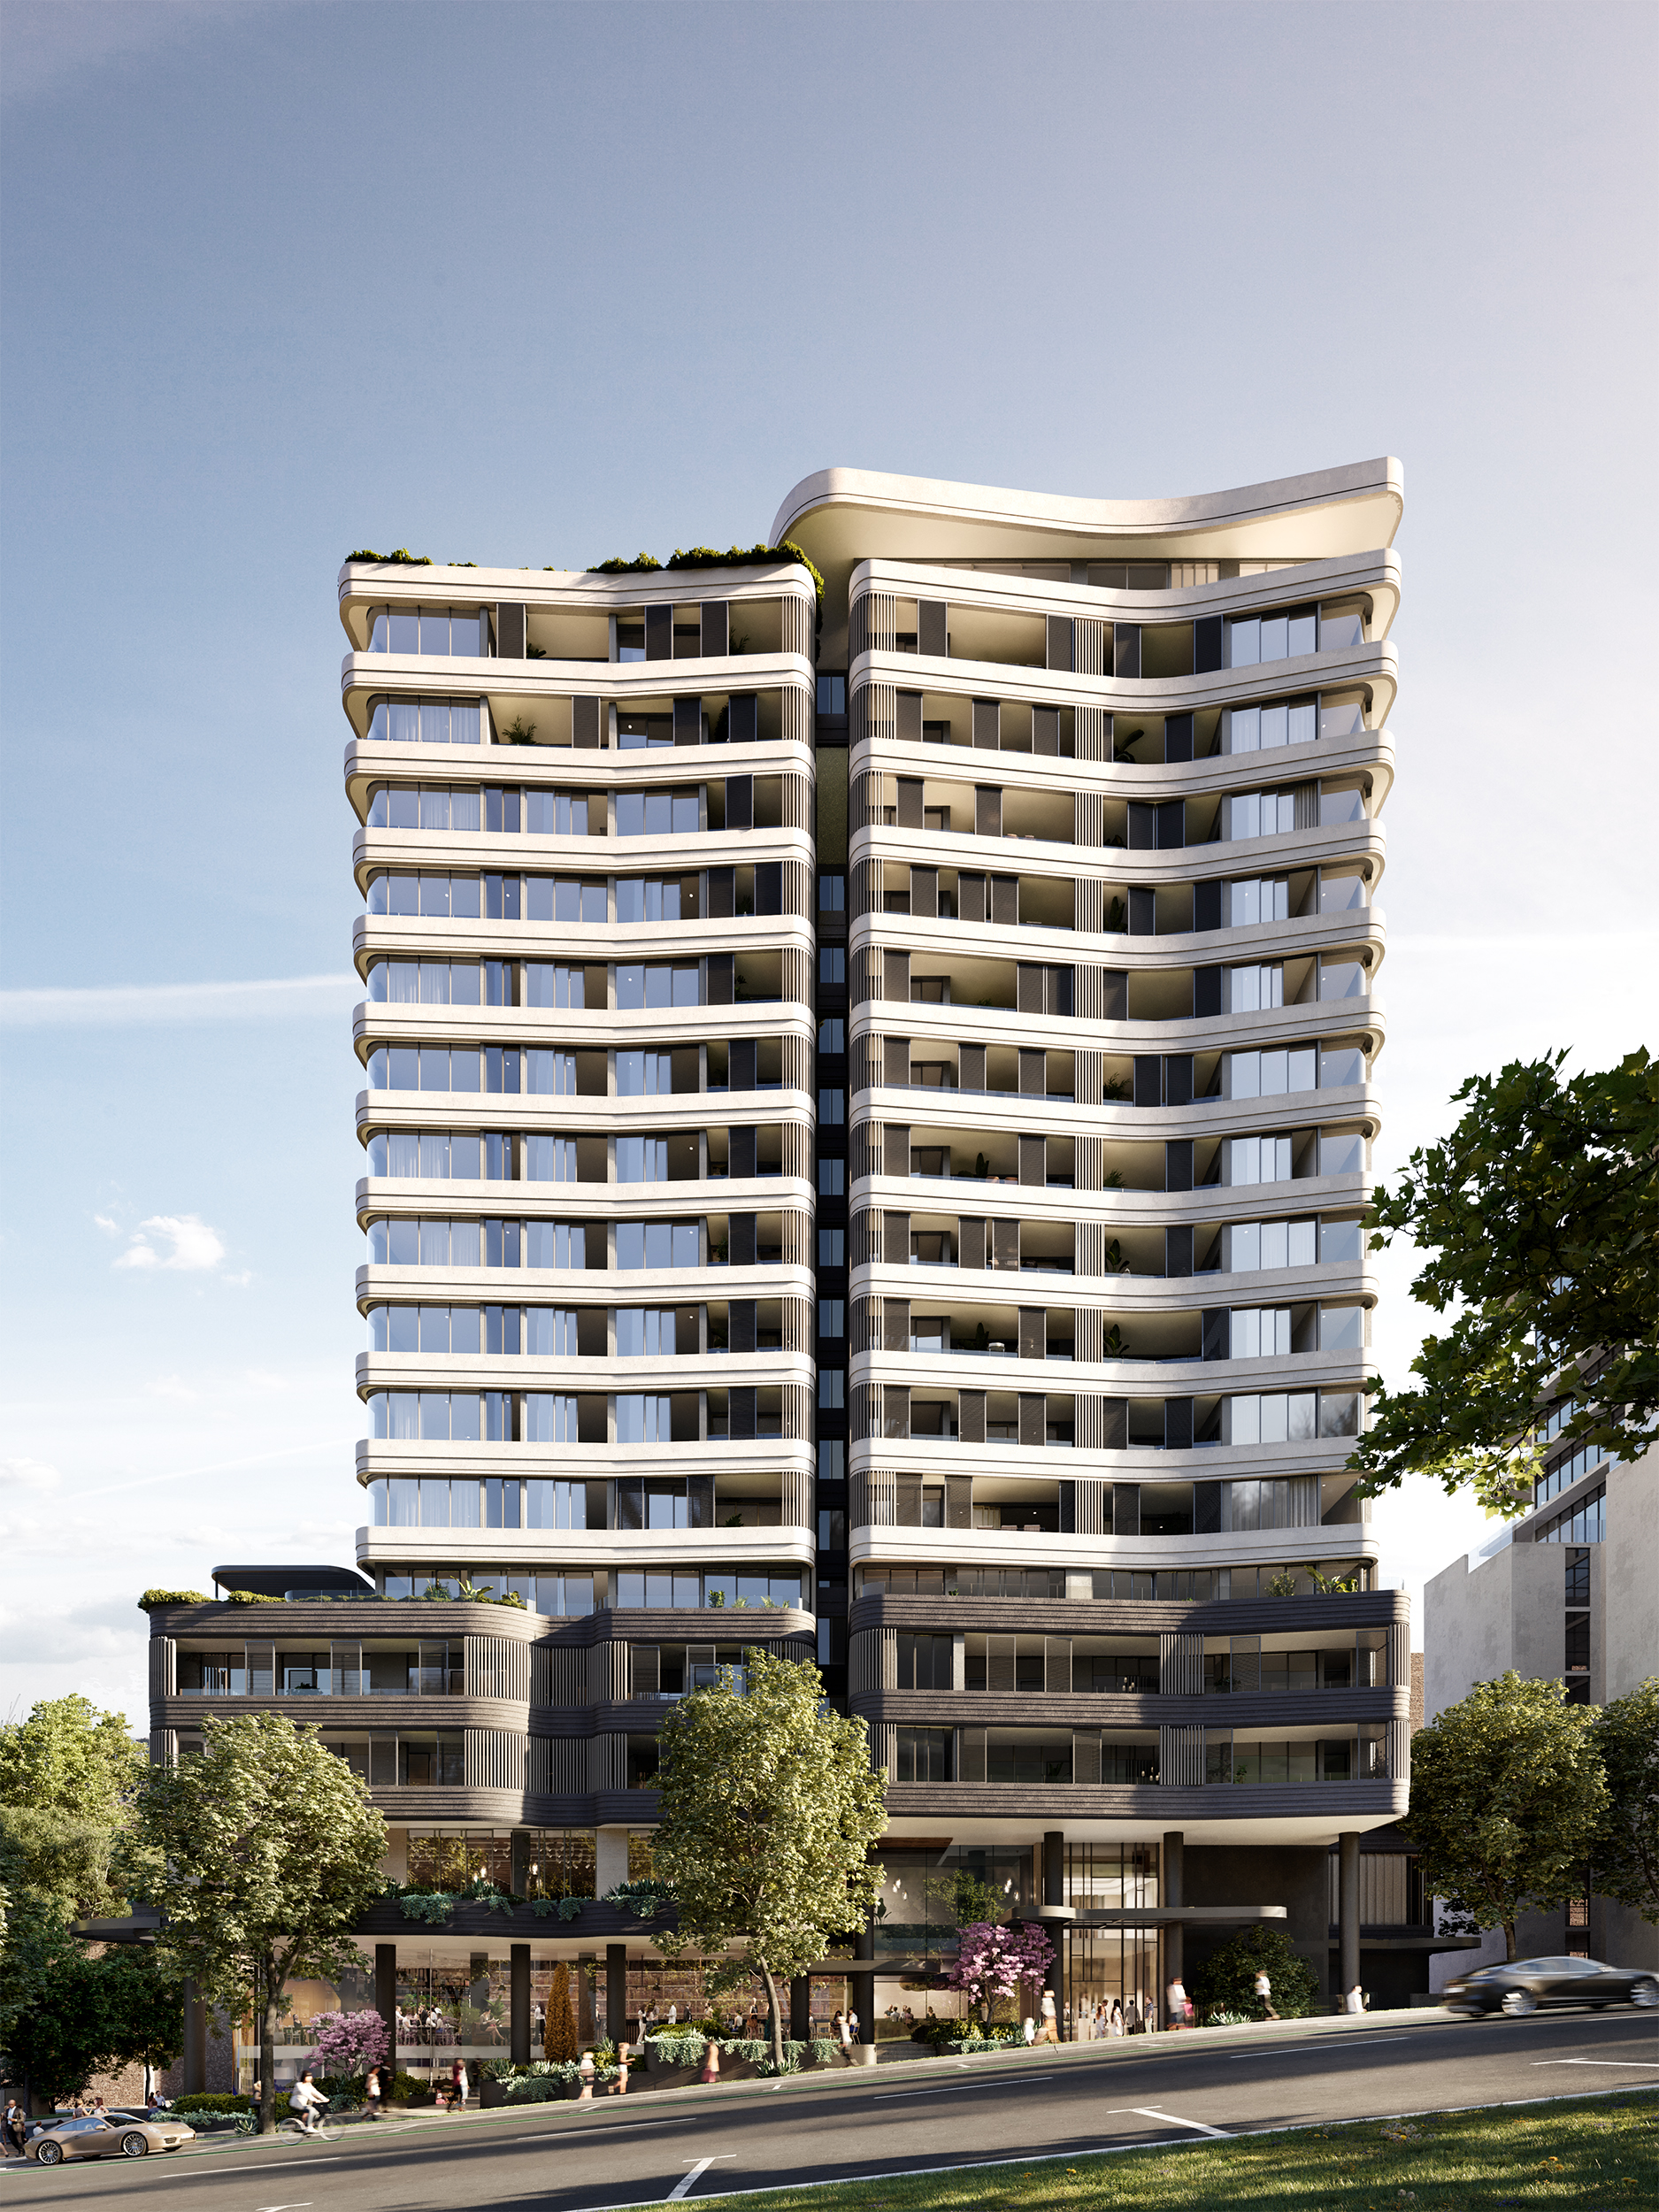
Located steps from Crows Nest Metro, the near-complete development brings luxury living to Sydney’s Lower North Shore.