War, Politics Eclipse Economics on Davos Leaders’ Minds
Hot and cold wars, fragmenting trade and key elections fuel anxiety at annual forum

 4 min
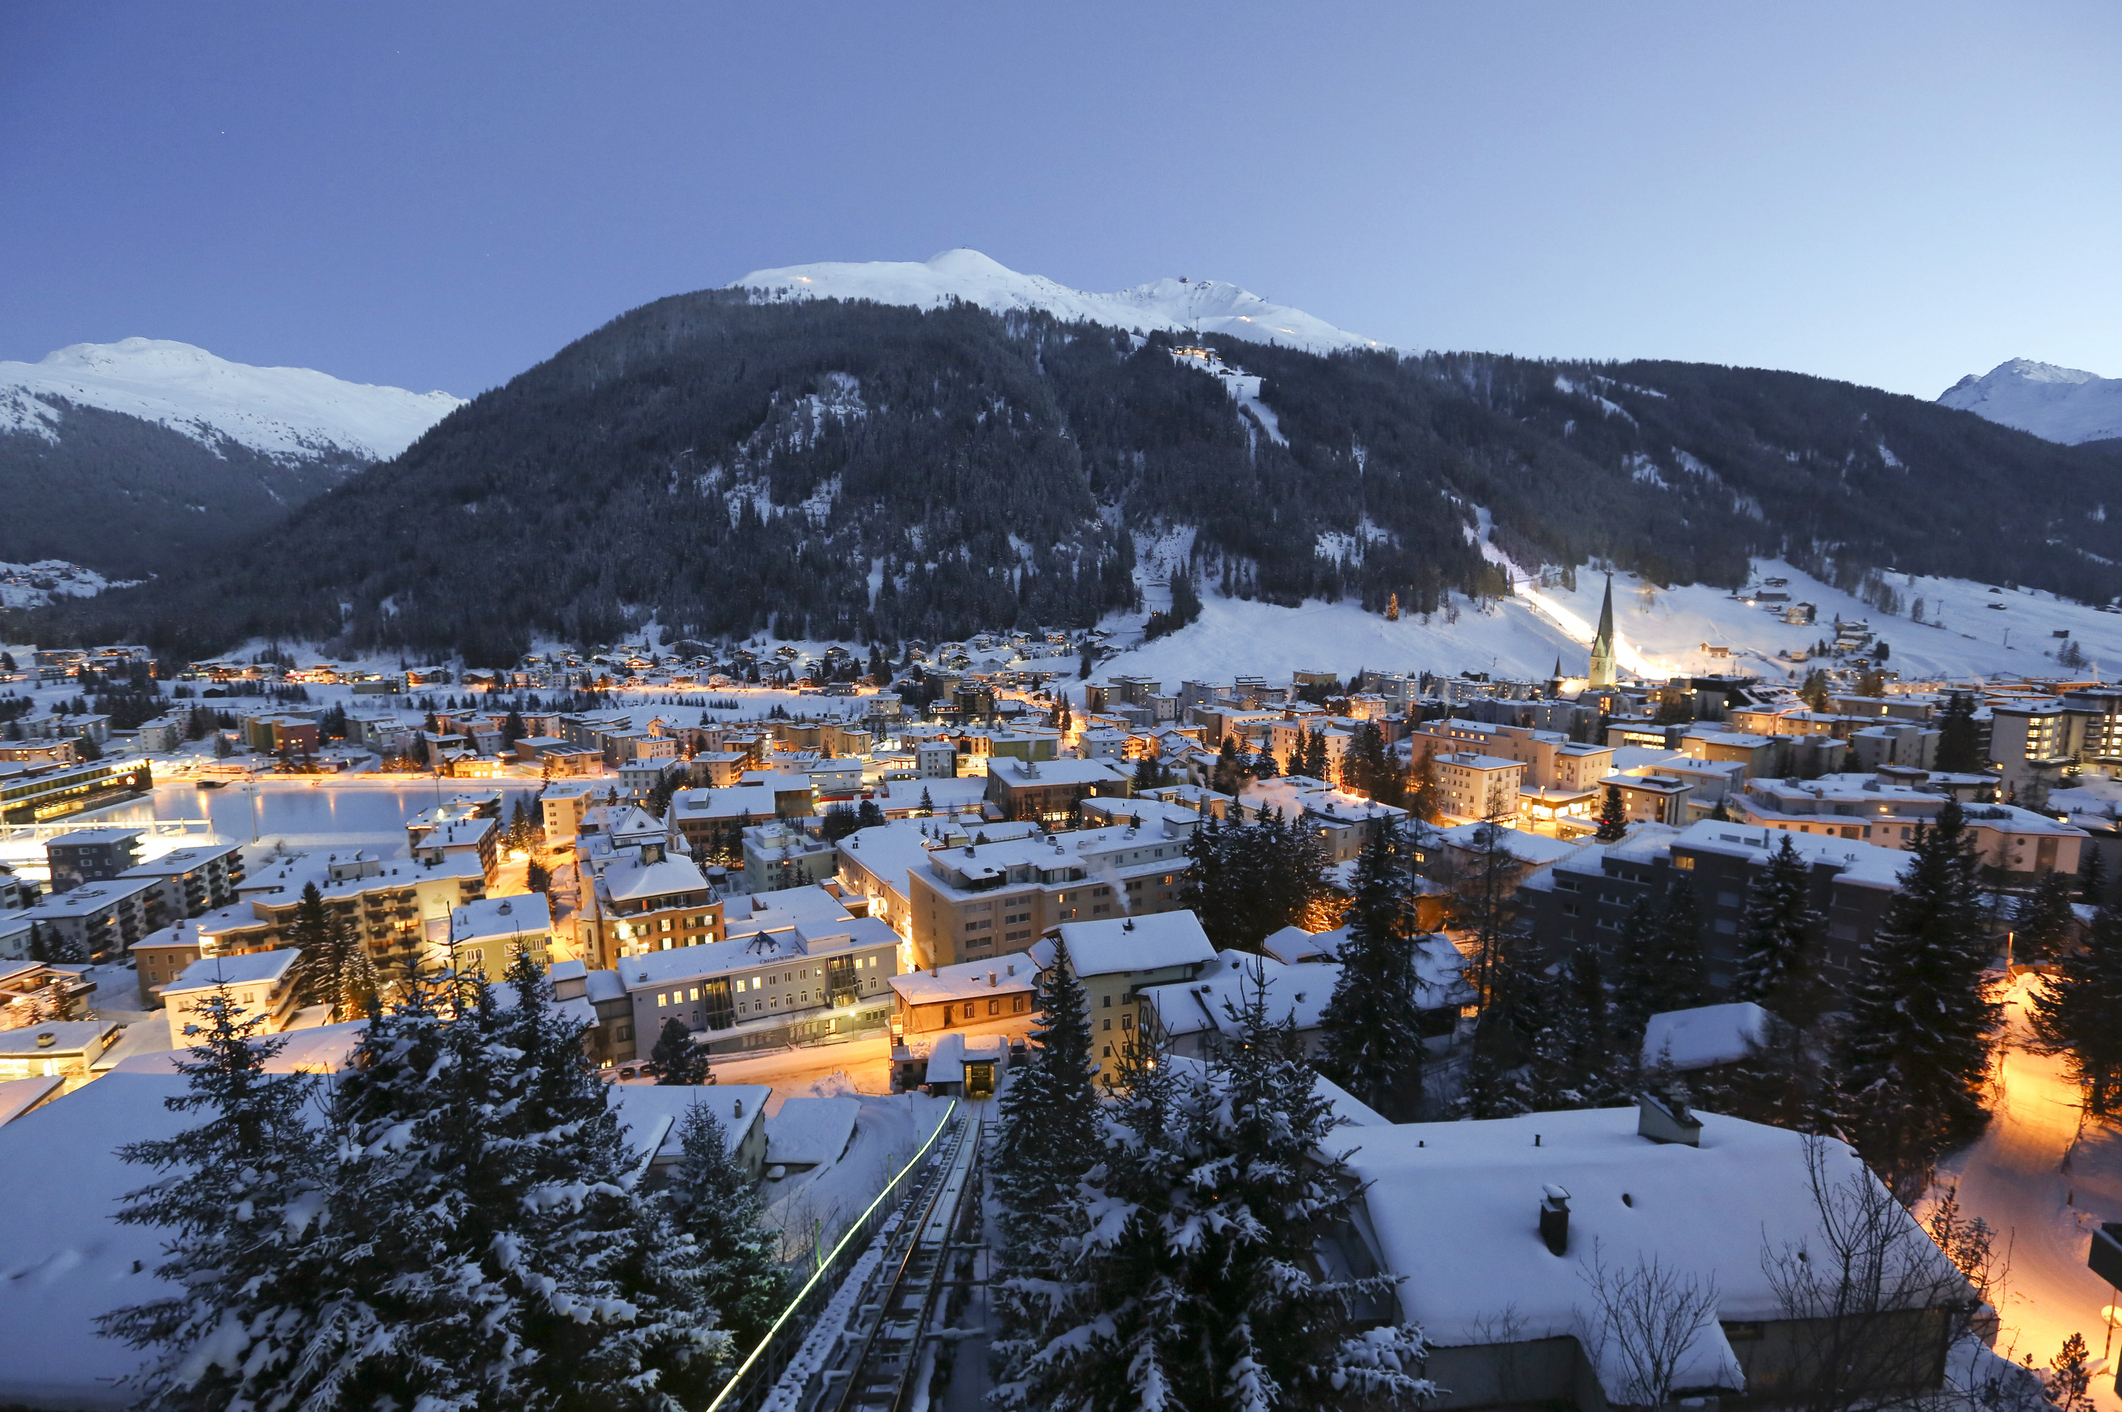
Never mind interest rates, inflation or recession. The economic concerns that usually preoccupy the global elite at their annual gathering in Davos are taking a back seat to hot war in Ukraine and the Middle East, cold war between the West and China and watershed elections from India to the U.S.
For government and business leaders, it is a disorienting departure from a world in which fortunes were mainly driven by financial forces. The World Economic Forum, which hosts the meeting, is now the de facto world geopolitical forum.
“There’s a higher-level issue than the economy, which is geopolitics,” said Christian Mumenthaler, chief executive of reinsurance giant Swiss Re, which insures risks around the world. Geopolitics hasn’t been so big an economic threat since the height of the first Cold War in the 1980s, he said.
“We’re starting this year with the longest list I ever recall of potential disruptions,” said Christian Ulbrich, chief executive of real-estate company JLL, which operates around the world. “You really have to run your organisation in an extremely agile way so that you can react immediately.”
Longtime Davos attendees came of age in a world in which products, capital and people flowed ever more freely. But globalisation began fragmenting in 2016 when Britain voted to leave the European Union and Donald Trump was elected president—and who went on to withdraw from a global climate accord and a trade pact with Pacific nations and then hike tariffs sharply, especially on China.
Deglobalisation has gathered speed with the pandemic, Russia’s invasion of Ukraine, the intensifying rivalry between the U.S and China and the newfound appeal of industrial policy—governments directing resources to favoured home industries. That is over and above the hazards thrown up by the natural world, such as extreme weather.
The upshot is that political events that were once peripheral to business leaders’ concerns are now central, especially when optimism is high that major economies will lower inflation without recession, so-called soft landings.
The U.S. election is on everyone’s minds because of the potential for Trump to return to the White House. On Monday, Trump won the first Republican nominating contest, in Iowa, by a wide margin.
“Every conversation begins with a query about my assessment of the outcome of Iowa, who’s going to win New Hampshire, and what are the odds of Trump 2.0,” said Tim Adams, president of the Institute of International Finance, a Washington-based group of international banks, and a former senior Treasury official under President George W. Bush. The questions are driven by trepidation, curiosity and fear that “the U.S. retreats, engages in protectionism, isolationism.”
One European bank chief said he has conducted “game-boarding exercises” to figure out how a Trump administration could play out for his business.
The U.S. election is one of many taking place this year, and for some companies, it isn’t necessarily the most salient. Last Saturday, Taiwan elected as president the candidate most opposed by Communist-ruled China, which is pressing for reunification with the self-governing island. Taiwan is home to Taiwan Semiconductor Manufacturing Co., the world’s dominant supplier of the most advanced microchips.
Many major tech companies depend on those chips. They must reckon with the possibility that military or economic coercion by China, or even war that draws in the U.S., could interrupt that supply. U.S. restrictions on investment and trade related to crucial technologies, including chips, have already disrupted what was once one of the world’s most integrated industries.
The threat to the chip supply “is a risk. That needs to be factored into all analyses you can do,” said Börje Ekholm, chief executive of Swedish telecommunications manufacturer Ericsson. The company has been focused on diversifying its supply chain for semiconductors and other parts since 2018, he said. “You also need to think about how you’re going to manage the situation where chip supply will be constrained.”
Gita Gopinath, the No. 2 official at the International Monetary Fund, said business leaders are worried about geopolitics interfering with trade and investment for good reason: “Fragmentation is a reality, it’s not just a threat.”
While trade has slowed everywhere since Russia’s invasion of Ukraine, it has slowed down more between blocs of allied countries—such as between the West and China or Russia—than within blocs. She said this shows that efforts to confine trade restrictions to strategic sectors, such as high tech, are failing, and a more general decoupling between blocs might be under way.
A study released by the McKinsey Global Institute Wednesday echoed the IMF’s findings. China, Germany, the United Kingdom and the U.S. have all reoriented trade toward allies or nonaligned countries like Mexico and Vietnam, it said
China’s share of U.S. imports of laptop computers and mobile phones, though not subject to tariffs, fell between 2017 and 2022, with much of that share going to Vietnam, the report said. Mexico, it noted, became the largest trade partner of the U.S. last year. Germany all but halted imports of natural gas from Russia while vastly increasing imports from Norway, a fellow member of the North Atlantic Treaty Organization.
That politics, not economics, might govern where companies sell and invest is a new reality that is taking some getting used to. Mike Henry, chief executive of Australian coal and mineral company BHP, said the company has always advocated free trade as the most efficient way to bring commodities to market. “A world of open trade and where countries are able to compete on natural advantage—that’s the world of the past. That’s not the reality we live in today.”
A few years ago China, upset with Australia for demanding an inquiry into Covid’s origins, cut many imports from the country, including coal from BHP, which saw its sales there fall. Though relations between Australia and China have since improved, BHP has since found other markets for that coal. Still, Henry said that in time, economic factors such as shipping rates will once again influence where it sells.
Some executives see hopeful signs, in particular that a rapprochement between China and the U.S. that began last fall will continue, in part because China is trying to help its faltering economy.
Geopolitical tensions also have beneficiaries. After artificial intelligence, the loudest buzz in Davos might be directed at India. Many executives called it their most promising foreign market, and its appeal has only grown now that Russia and much of China are off limits.
“When disruptions take place, people are trying to hedge,” said Hardeep Singh Puri, India’s minister of oil and gas. “But India has a growth story of its own. That is what is driving interest in India.”
For some companies, geopolitical tensions are weighing on employees, not just management. “People are concerned about what’s going on in the world,” JLL’s Ulbrich said. Conflict, or the threat of it, in Europe, Israel/Gaza and China weighs on people, he added. “They don’t know what’s going to happen and look to other people, leaders, for what’s going to happen, but leaders don’t know either.”
—Chip Cutter and Alex Frangos contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From Tokyo backstreets to quiet coastal towns and off-grid cabins, top executives reveal where they holiday and why stepping away makes the grind worthwhile.

From Italian vegetable-tanned leather to real-world training insight, Australian brand PK9 Gear is redefining what luxury means for discerning dog owners.