The One-Child Policy Supercharged China’s Economic Miracle. Now It’s Paying the Price.
Revised U.N. data shows the speed of China’s aging after it accelerated its ‘demographic dividend’

 5 min
When China launched its one-child policy more than four decades ago, it sped up an evolution toward smaller family sizes that would have happened more gradually.
The policy supercharged the country’s workforce: By caring for fewer children, young people could be more productive and put aside more money. For years, just as China was opening its economy, the share of working-age Chinese grew faster than the parts of the population that didn’t work. That was a big factor in China’s economic miracle.
There was a price and China is now paying it. Limiting births then means fewer workers now, and fewer women to give birth. A United Nations forecast published Thursday shows how quickly China is aging, a demographic crunch that the U.N. predicts will cut China’s population by more than half by the end of the century.
In the late 1970s, China’s leaders feared a population explosion that would drain the country’s resources. When Deng Xiaoping rolled out the one-child policy nationwide in 1980, he said, “We must do this. Otherwise, our economy cannot be developed well.”
A young population has helped drive economic growth in developing countries across the world, including in China’s neighbor Japan starting in the 1950s. Economists call it a demographic dividend—the window, generally of a few decades, when a country has far more working-age people than young and elderly dependents. As such countries grow wealthier, people naturally choose to have fewer children and the population starts to age.
That was also the trajectory in China—just faster.
Knowingly or not, China essentially borrowed from its own future by accelerating its so-called demographic window. How the effects of the policy have sped up China’s demographic bind is scrambling the long-term models demographers usually work with.
“The challenge with China is that from one year to another the situation can change quite fast,” said Patrick Gerland , head of the U.N.’s population estimates and projection section. “Within the last decade, the changes have been very big, both in policy and in the numbers.”
For example, in its just-published global estimates, the U.N. expects China’s population to drop from 1.4 billion today to 639 million by 2100, a much steeper drop than the 766.7 million it predicted just two years ago.
Even so, the U.N.’s prediction looks optimistic compared with other estimates. Researchers from Victoria University in Australia and the Shanghai Academy of Social Sciences have predicted that China will have just 525 million people by the end of the century.
It is impossible to say what China’s population trajectory would have been without the one-child policy. But a comparison with a broad group of other countries gives a clue.
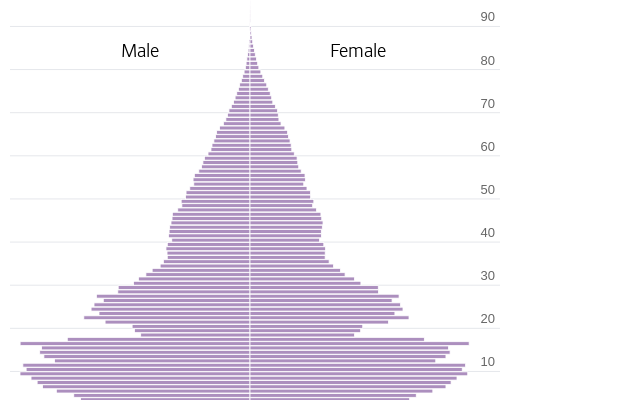
Research by U.N. demographers illustrates how China’s demographic window opened faster and more sharply than in other “less developed” countries, and then closed equally quickly. The population of Chinese aged 20-64—the age when people are most likely to work—grew faster than children and the elderly in the years after the one-child policy was implemented. Before the policy ended, the trajectories had already reversed.
The broader group of other countries shows a smoother ride with the demographic window lasting well into the 2040s.
With China’s opening to the West, it became the world’s factory floor with millions of young people determined to work their way out of poverty. For most of the next decades, Chinese growth topped double-digit percentages.
The optimism was on full display during the 2008 Beijing Summer Olympic Games. When the global financial crisis hit soon after, China kept growth humming and was credited with helping to save the global economy. A few years later, China overtook Japan as the world’s No. 2 economy .
But by 2013, China’s demographic dividend was largely over, according to research by Andrew Mason , an emeritus professor of economics at the University of Hawaii, and Wang Feng , a sociology professor at the University of California, Irvine.
Now, slowing economic growth and demographic changes feed off each other for a gloomy outlook.
“People always count on the [Chinese] government to do more to prop up the economy but the reality is that there’s not a lot the government can do,” Wang said.
Over the next decades, China’s population is likely to show a contrast from, say, India, where the age distribution is following a more natural progression, or the U.S., where immigrant inflows help counteract the aging of the population.
By the end of the century, the U.S. population will be about two-thirds of China’s, compared with less than a quarter now, according to the U.N.’s latest projections. And by then, India, which has overtaken China as the world’s most populous country , will have more than twice as many people as China.
The real demographic impact in China won’t fully hit until the middle of the century, when many of those born during the one-child policy will reach retirement—while still caring for aging parents, said Wang.
By 2050, the U.N. now projects 31% of Chinese will be 65 or older. By 2100, the share will be 46%, approaching half of the population. In the U.S., the share is expected to be 23% and 28%, respectively.
The U.N.’s revised forecasts see Chinese births dropping below nine million this year. In 2022, it had predicted that 10.6 million would be born in China in 2024. The U.N. now expects China will have only 3.1 million newborns a year by 2100.
Not only are there fewer women to give birth these days, but many young women, mindful of their mothers’ suffering during the one-child policy, are less interested in marriage and children , driving down the fertility rate.
As births slip, China’s elderly population is ballooning.
China expects a glut of more than 40 million new retirees—more than the population of Canada—over the five-year period ending in 2025.
The old-age support ratio, a rough indicator of the number of workers for each retiree used by the Organization for Economic Cooperation and Development, is projected to decline from more than four now to fewer than two in 2050, according to The Wall Street Journal’s calculations of the U.N.’s latest data. It will likely reach one worker per retiree by the end of the century.
In reality, due to China’s low retirement age , with women clocking out as early as 50 and men at 60, the support ratio could be even lower.
Beijing as well as demographers and sociologists have said a highly educated population and the advancement of technology such as artificial intelligence, could help China weather such shocks, as more jobs will be automated.
The U.N.’s Gerland said that while the one-child policy was the main demographic event in recent decades, the waxing and waning in different Chinese age groups also reflect tumultuous periods in China’s past, such as the Cultural Revolution and Great Leap Forward, which had substantial demographic impact on the size of the various cohorts born during these years.
“Because of China’s history, the population is going to carry over some of these memories of the past and it will take many generations for all of these past stories to be forgotten,” he said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.

By improving sluggish performance or replacing a broken screen, you can make your old iPhone feel new agai
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.