Buying Australian: why it’s no longer a sign of parochialism
As the Australian made edition of Kanebridge Quarterly magazine hits stands this weekend, we examine the case for purchasing locally made product
 5 min
Mention Australian made products to family and friends and it’s likely everyone will agree it’s a good thing to do.
Polling by Roy Morgan as recently as February this year shows 80 percent of shoppers consider buying Australian made products important, mainly because it supports local jobs and the wider economy. The survey also found that 67 percent of shoppers reported buying Australian-made products ‘often’ or ‘always’.
But while most of us are happy to buy, say, Australian made peanut butter or even skin care products, we’re less inclined to choose a locally crafted table over an imported product, mainly because of the price.
Canberra-based craftsman Rolf Barfoed says COVID changed attitudes to buying local. With many working from home and borders closed to everyone and everything — including many goods manufactured offshore — Australians began to reassess their buying practices, as well as their domestic environments.
“We got quite busy after COVID struck because people were forced to look inwards and instead of going overseas on holiday, they had a bit of money to spend locally,” Barfoed says of his workshop where he manages a team of three. “There were a lot of people working from home and they were looking at their homes more critically.”
Desks and bookshelves were a popular choice, as many looked to properly furnish home offices, while beds and bedside tables also rated highly, providing a sense of sanctuary and comfort during uncertain times.
However, as restrictions lifted and with more people growing concerned about rising cost of living pressures, Barfoed says he has noticed a shift in buying patterns.
“Ever since the threat of recession, things have tightened up and sales have slowed,” he says.
For more stories like this, order your copy of the latest issue of Kanebridge Quarterly magazine here
While some may be put off by the higher costs — a reflection of higher wages being paid to Australian workers — Barfoed says the final price is just the start of the story. He gains most of his work from Sydney and Canberra via word-of-mouth commissions, allowing buyers to connect with their piece of furniture from the start. And some connections are stronger than others.
“In Canberra there is a pool in Manuka and there was a big oak tree over the pool which came down in a storm,” he says. “We had people who had swum in that pool as children who asked if we could make something out of the tree for them, so we created two dining tables. It helps that the timber miller is well connected in town and he has the means to pick up trees like that.”
Most timber, however, is sourced through more traditional avenues, although local timbers have been harder to find since the 2019/2020 bushfires.
For those after something unique and fit for purpose though, the experience of commissioning from a local maker is unmatched.
“The option for customisation is a big factor and we will tailor it to exactly what the client wants,” Barfoed says. “It is always a nerve wracking experience handing over a piece of furniture. You want the client to be happy with your work.”
Kate Stokes, co-founder of award-winning Melbourne lighting and furniture studio Coco Flip says ‘locally made’ also means shorter lead times and more reliable supply chains for retailers, designers and homeowners.
“We have really good relationships with all our manufacturers which means there’s a lot more quality assurance,” she says. “If something goes wrong, you just send it back to us. You can’t do that so easily if it’s arrived by ship.”
While the products, which include their Coco pendant light, Mayu floor lamp and Sequence dining tables often do cost more upfront than imported items, Stokes says they are better financial investments over the long term.
“We want to design things that people are not going to tire of in five years so our designs are classic, contemporary and able to fit into a range of styles and interiors,” she says. “Construction has to be robust and material choices have to be solid and last a long time.
“We want people to love them for a long time.”
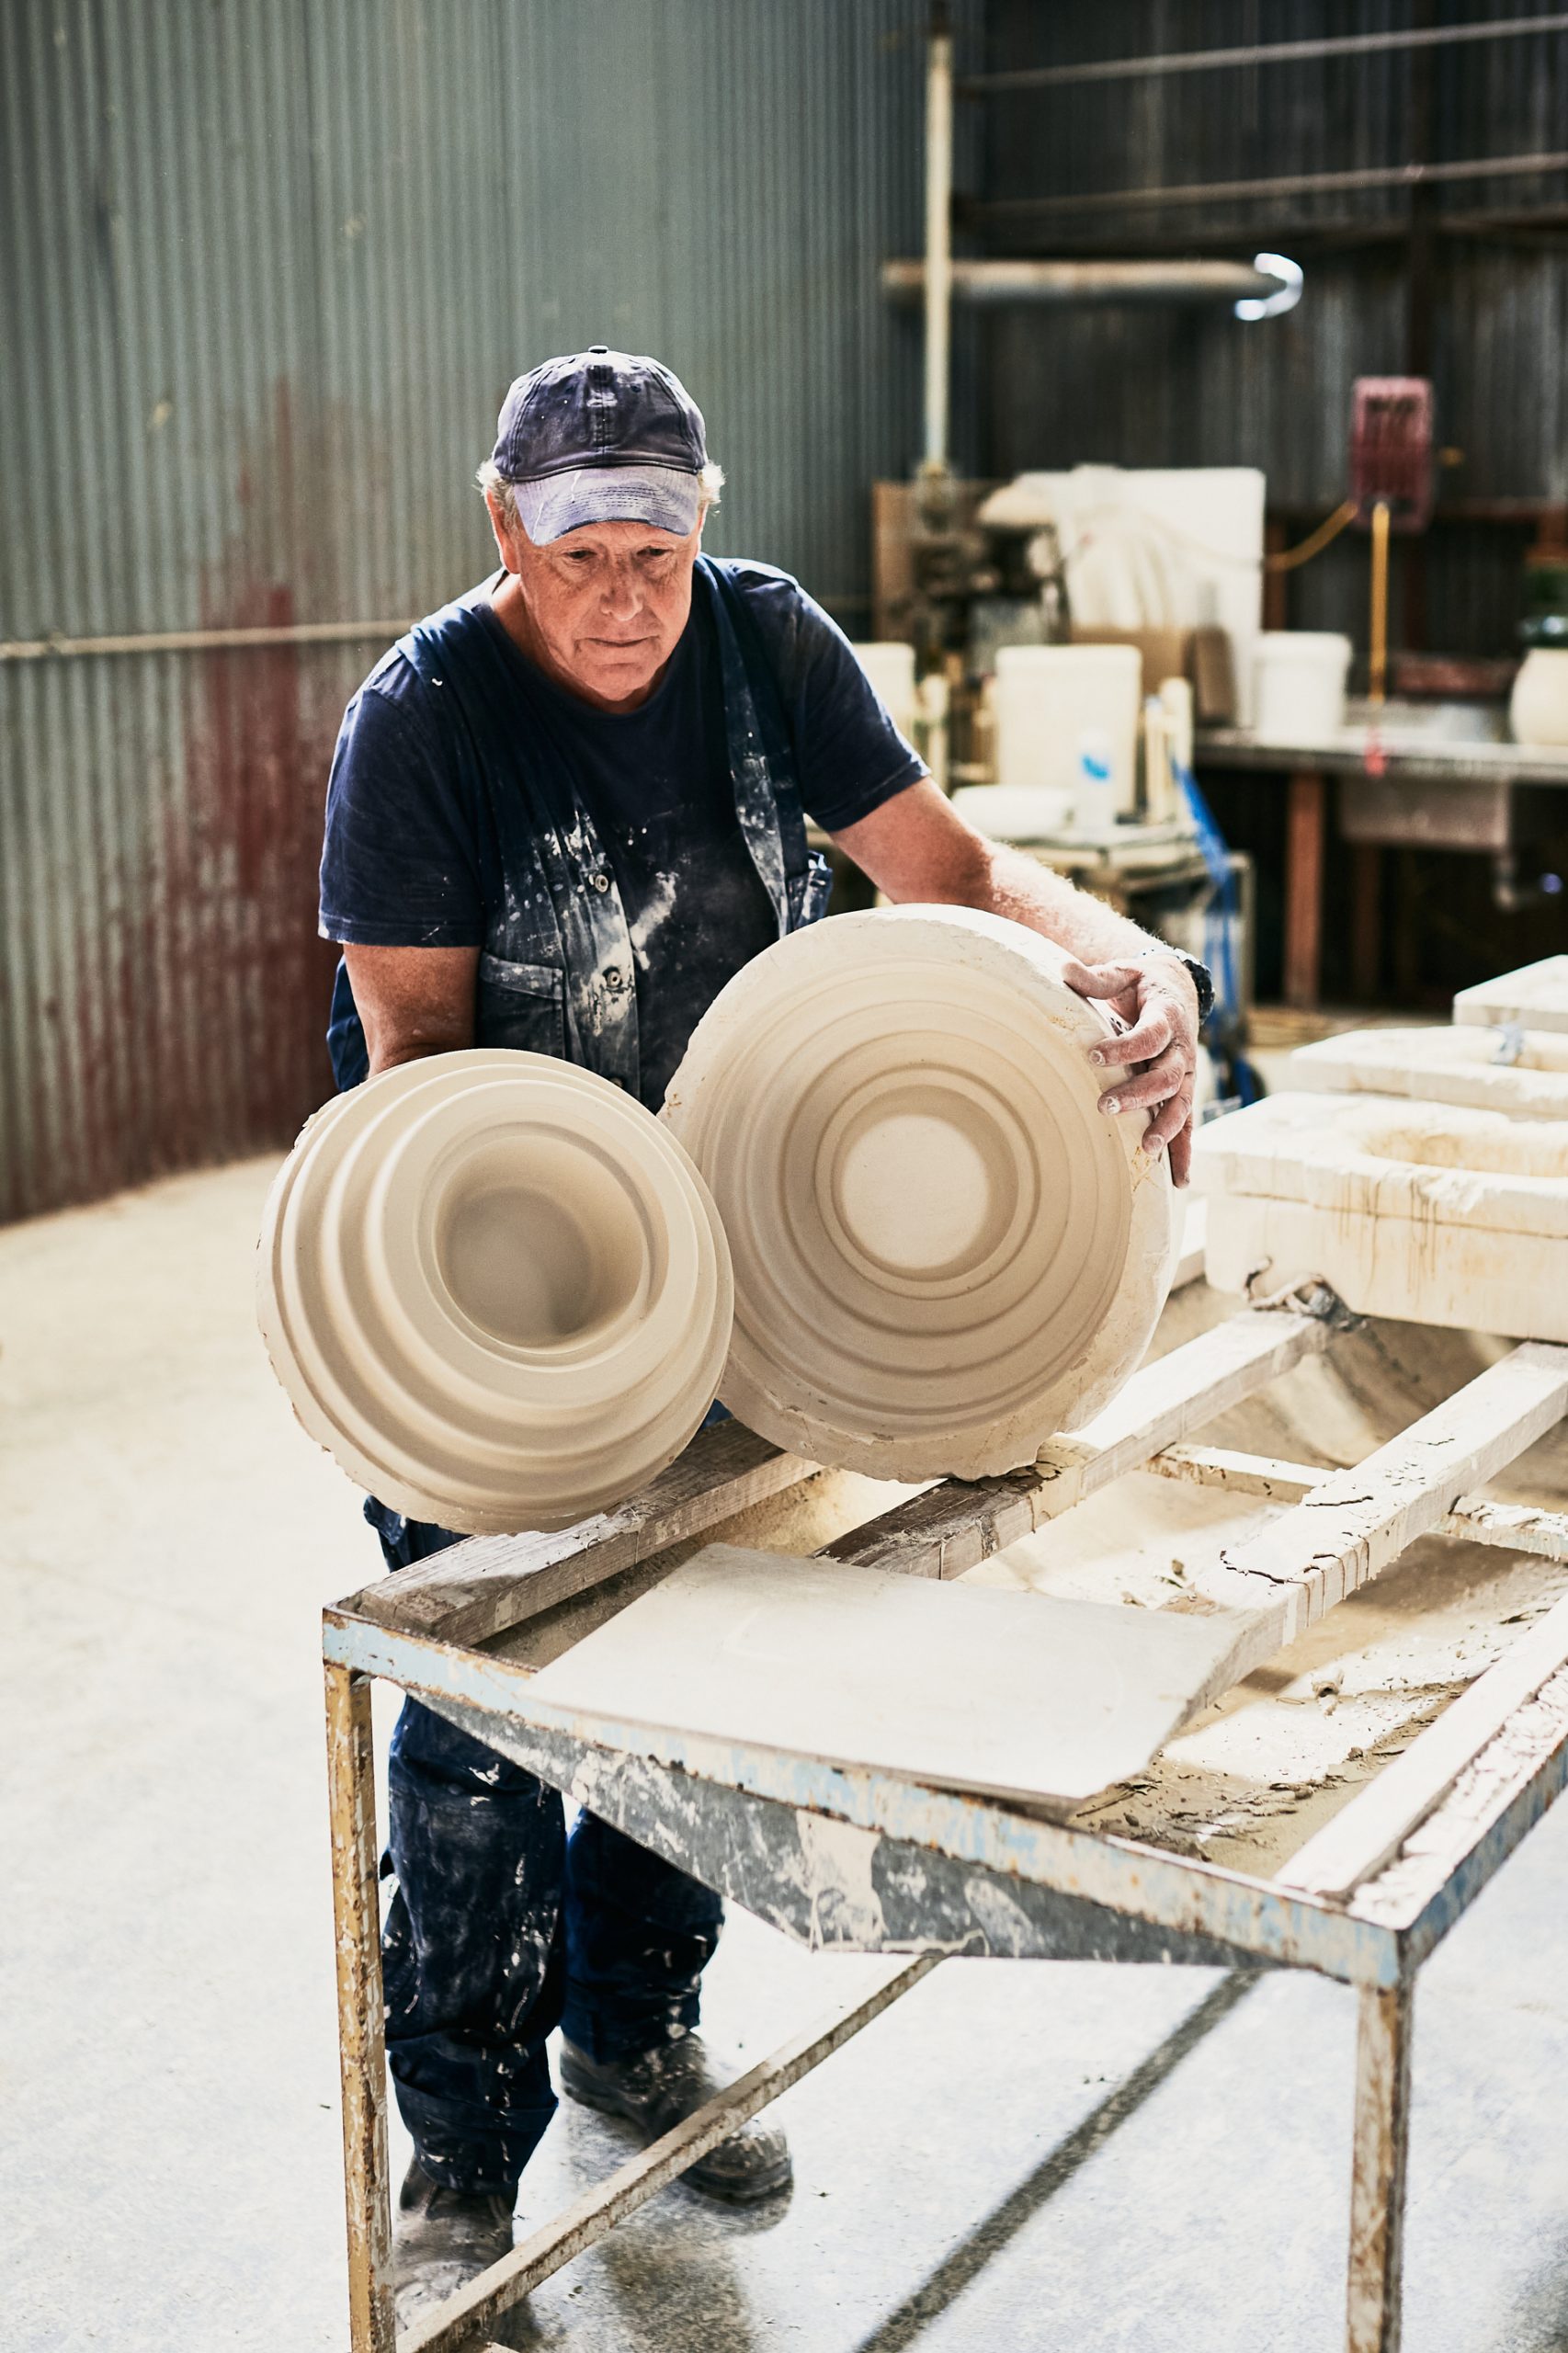
Stokes and co-founder Haslett Grounds also work with longstanding manufacturers such as Specialty Pleaters in Williamstown, which was founded in 1925 and is now the last remaining pleating studio in Melbourne.
“We love working with local manufacturers and Specialty Pleaters have been in business for about 100 years but they are potentially facing closure because production is increasingly going off shore,” Stokes says.
Australian furniture manufacturing legend, Tony Parker, of Parker Furniture fame says if Australians don’t support locally made furniture and homewares, they will cease to exist — and those traditional skills will all but vanish.
“When you buy locally made, the goods are also serviced in Australia and the infrastructure to manufacture is here,” Parker says. “You have apprenticeships for training people in cabinetwork, upholstery and other skilled trades.”
He laments what he sees as the decline in quality of mass produced goods flooding the Australian market from overseas, not just because it means jobs are taken offshore, but that buyers are not getting value for money.
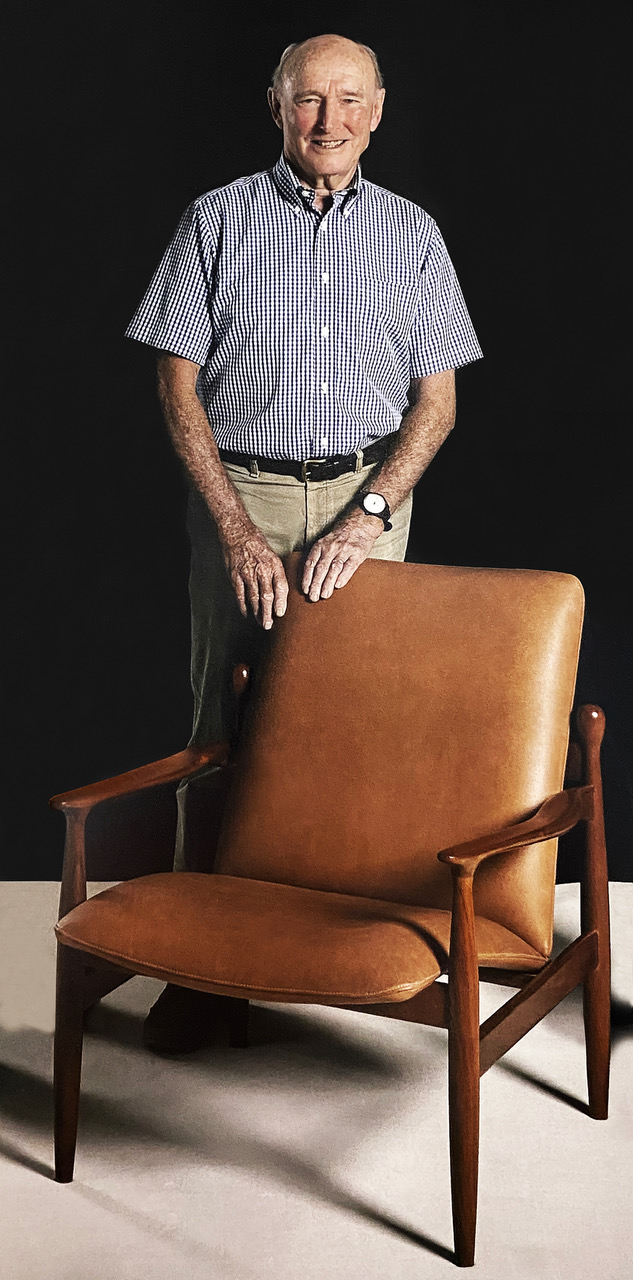
“They have slowly eroded quality,” he says. “Everyone closes on price. In actual fact, people are paying more than they were in the 70s, relative to wages, and it was better made then.
“The retailer is looking for a cheaper price and the customer is not looking at quality.”
Fred Kimel, founder of Handkrafted, which connects Australian makers directly with the public, says buying locally is an investment in the future, in more ways than one.
“The result is (a piece) typically much higher quality than the vast majority of furniture that is manufactured overseas,” Kimel says. Locally made bespoke furniture is made-to-last and will retain value as it can always be sold or passed on — it’s far less likely to find its way into landfill.
“On the sustainability front, our local regulations help to ensure that timber used by local makers is forestry certified and not from unregulated or illegally logged forest timber.”
And if it’s that lovely rush of endorphins experienced when you buy that floats your boat, buying an Australian made product has to be the ultimate shopping high.
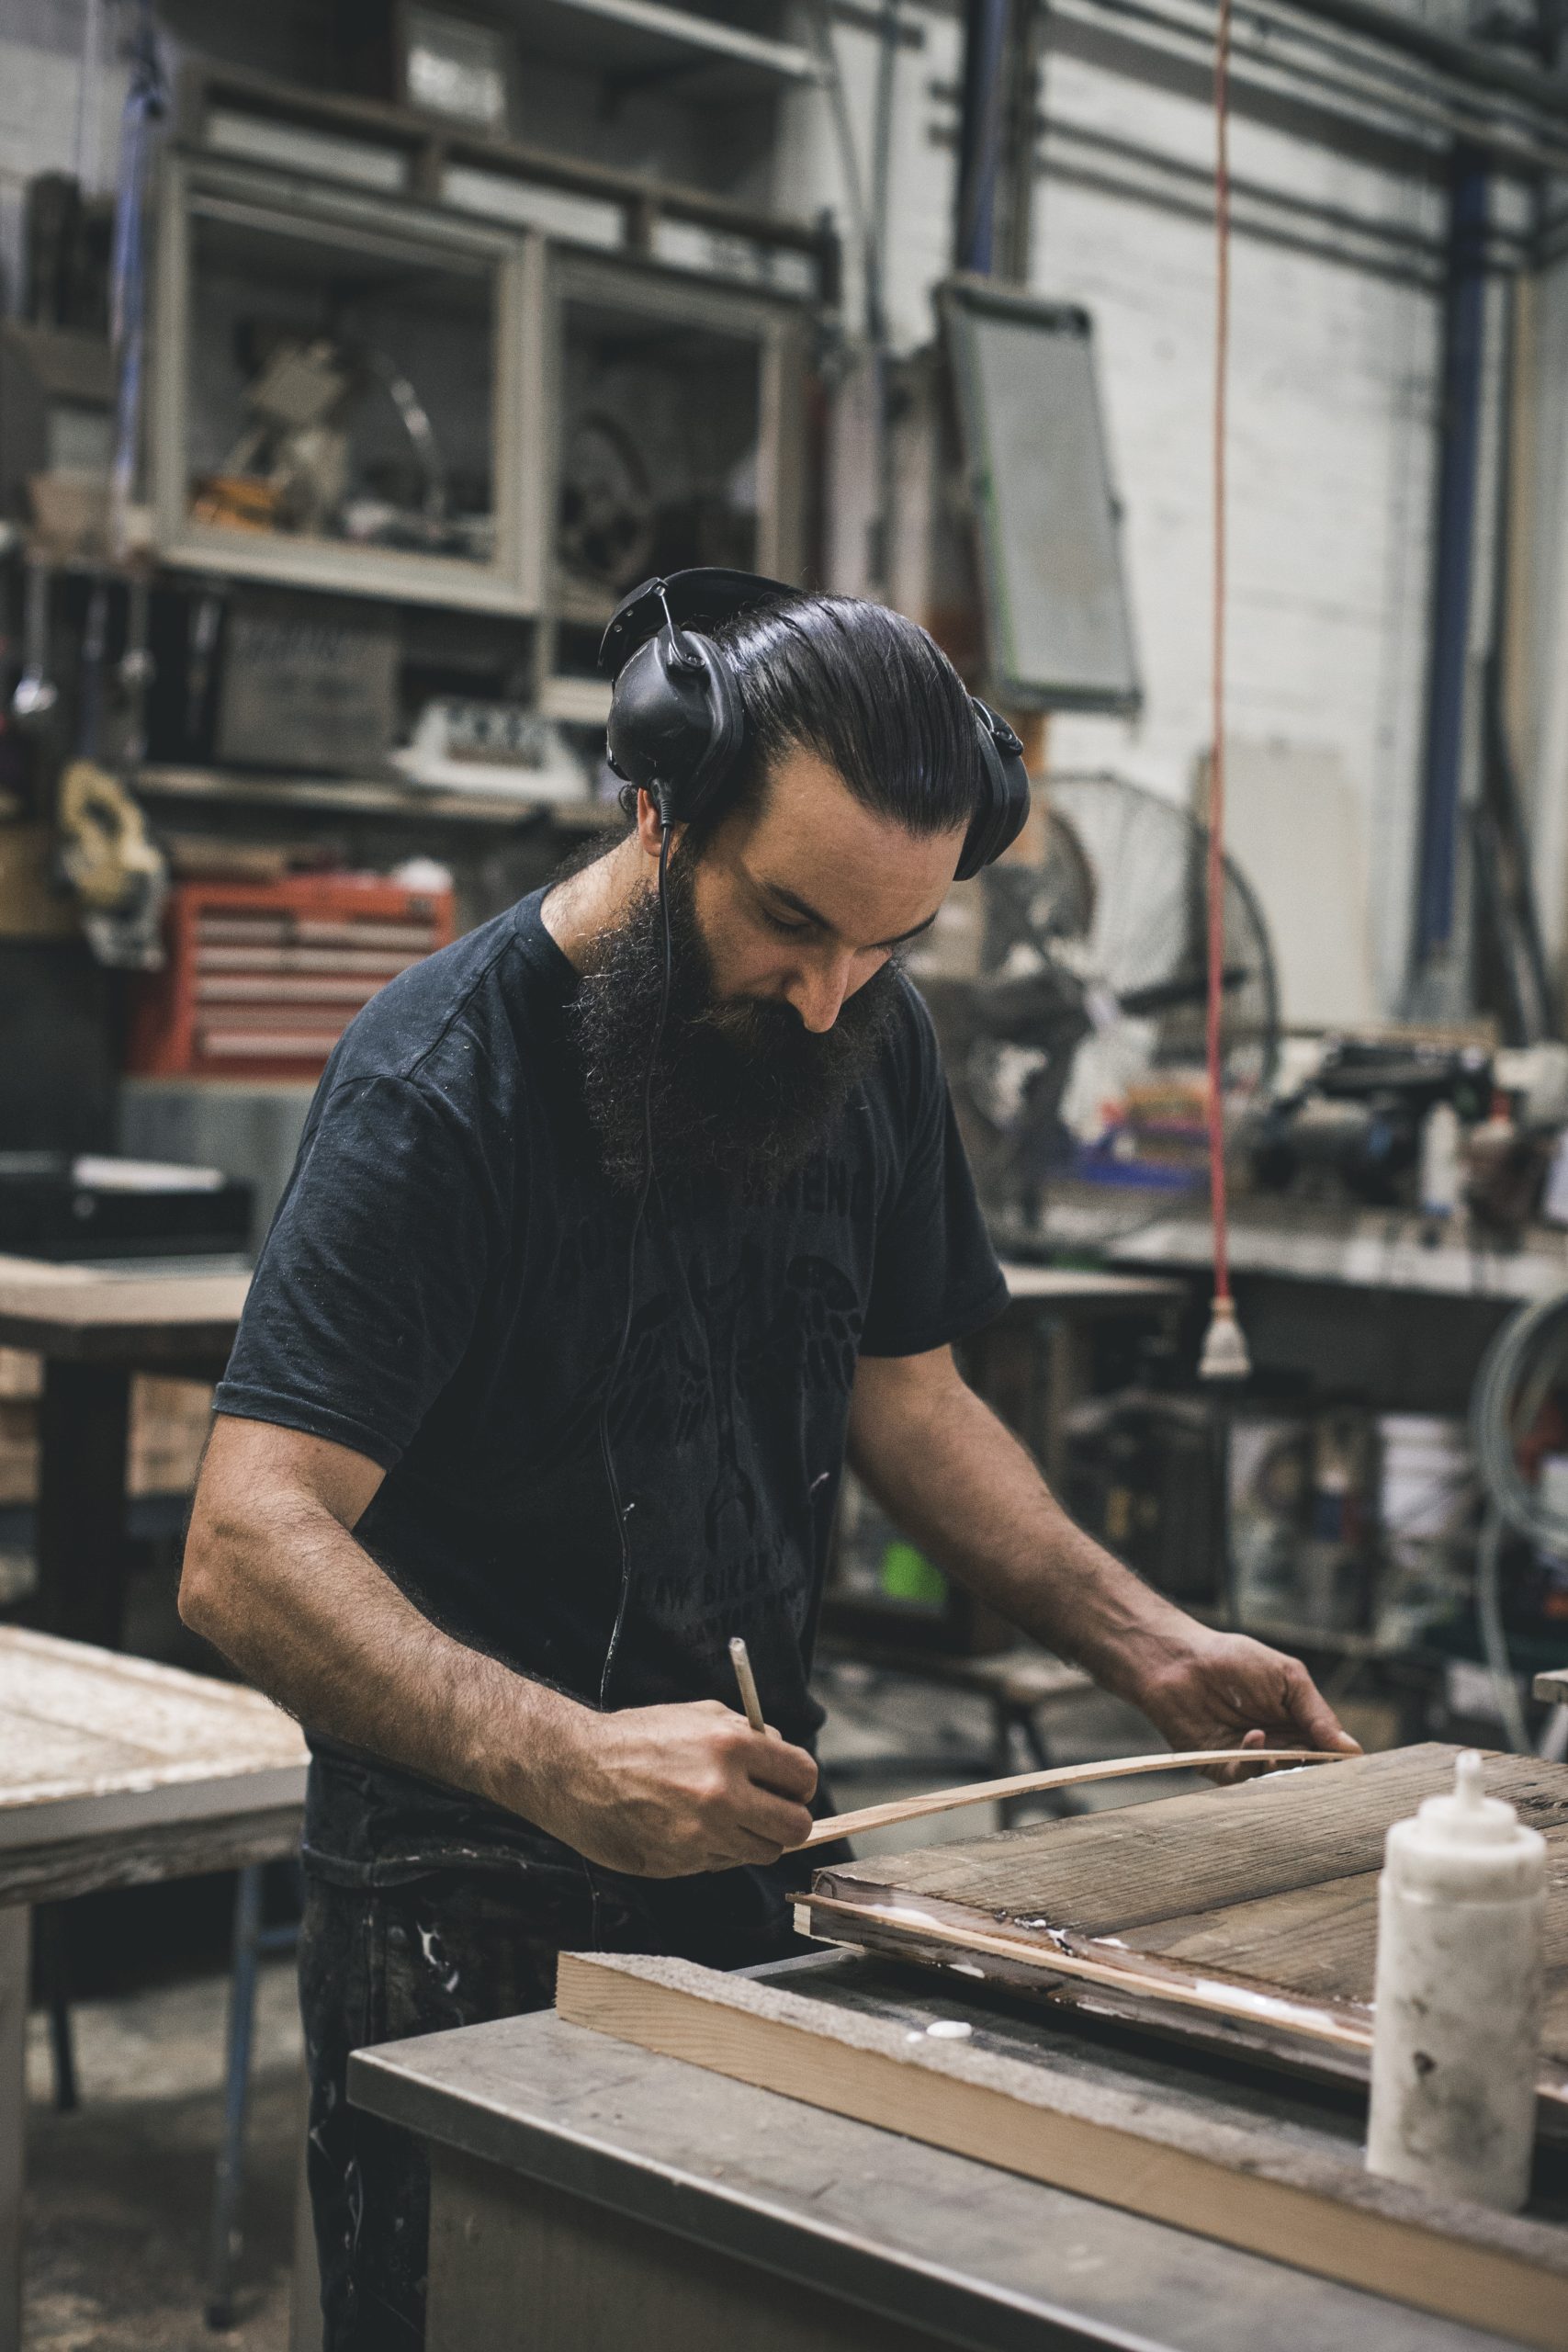
“Perhaps one of the biggest draw cards is simply the enjoyable process of working so closely with a local maker,” Kimel says.
“Clients will often visit their workshops and take much more interest in the selection of raw materials, design decisions and production methods. It’s an experience that lives on through the product.”
Advance Australia fair, indeed.

From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Barnet, in North London, lays claim to two of the country’s most expensive roads to own a home.
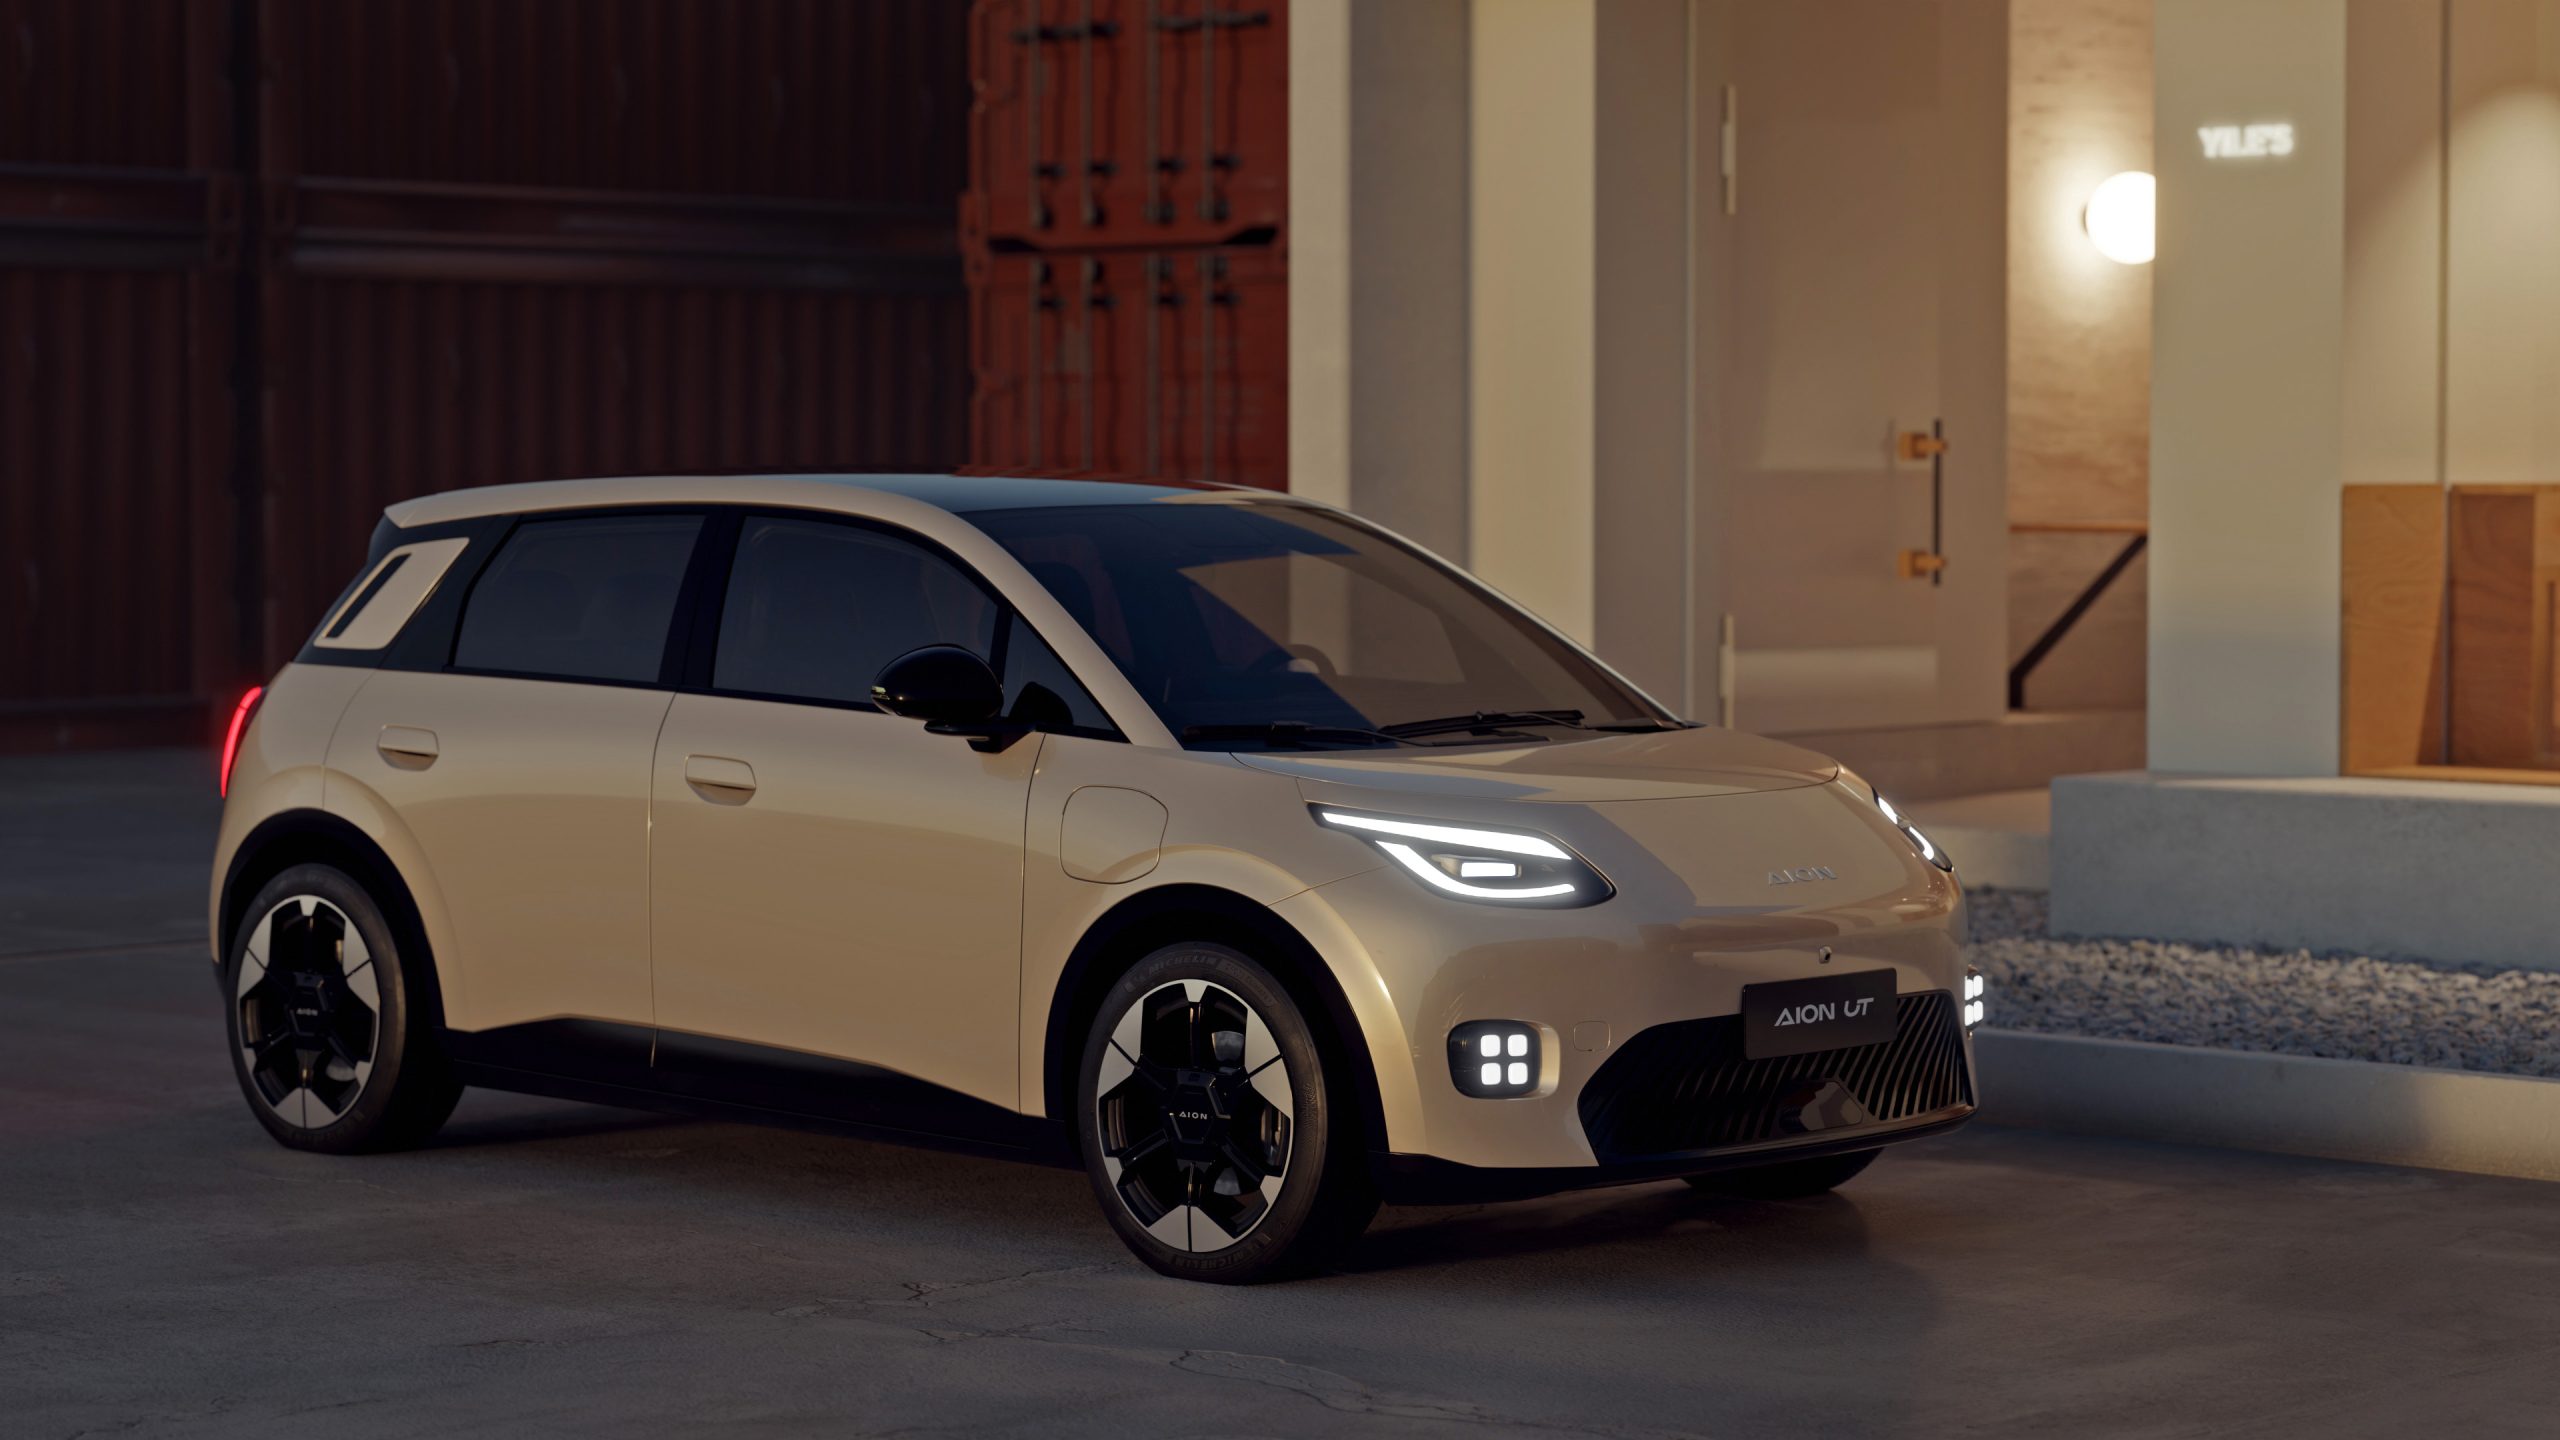
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.