

Why Is Inflation So Sticky? It Could Be Corporate Profits
Some companies might have been raising prices faster than their costs have increased

 4 min
Inflation has proved more stubborn than central banks bargained for when prices started surging two years ago. Now some economists think they know why: Businesses are using a rare opportunity to boost their profit margins.
Figures released Tuesday by the European Union’s statistics agency showed consumer prices in the eurozone were 7.0% higher than a year earlier in April, a pickup from March and more than three times the European Central Bank’s target. However, the core rate of inflation—which excludes food and energy prices—edged down to 5.6% in April from a record high of 5.7% in March.
Inflation rates also remain uncomfortably high in the U.S. and many other parts of the world despite interest-rate rises that have gone further and been delivered more quickly than at any time since the 1980s.
There have been good reasons for businesses to raise their prices in recent months. The supply-chain disruptions caused by the Covid-19 pandemic and the energy, food and raw-material bottlenecks that followed Russia’s invasion of Ukraine have pushed costs higher.
But there are signs that companies are doing more than covering their costs.
According to economists at the ECB, businesses have been padding their profits. That, they said, was a bigger factor in fuelling inflation during the second half of last year than rising wages were.
Jan Philipp Jenisch, chief executive of construction-materials maker Holcim, said on a recent earnings call: “We are in that inflationary environment already for almost two years now…We have done the pricing in a very proactive way, so that our results aren’t suffering. On the contrary, they are improving the margins.”
One puzzle is why consumers have played ball. Usually, economists would expect any business that raised its prices to lose customers to competitors that don’t, or not by as much.
But these aren’t normal times. In rare situations—such as an economy’s reopening after a pandemic—widespread knowledge that costs are rising allows businesses to raise their prices knowing that their competitors will act in the same way, according to a paper by Isabella Weber, assistant professor of economics at the University of Massachusetts, Amherst, and her colleague, Evan Wasner.
That is a pattern the two economists said has played out in an analysis of recent earning calls in which executives at U.S. businesses present their financial results to analysts.
“We do have to think about pricing differently,” said Ms. Weber. “A cost shock, or bottlenecks can create an implicit agreement among firms that raise their prices, so they can expect others to act likewise.”
Consumers have also been unusually willing to accept higher prices lately. Paul Donovan, chief economist at UBS Global Wealth Management, said businesses are betting that consumers will go along because they know about supply bottlenecks and higher energy prices.
“They are confident that they can convince consumers that it isn’t their fault, and it won’t damage their brand,” Mr. Donovan said.
The latest round of earning calls by large consumer-facing companies underlined that. Food and health company Nestlé last week said it had boosted sales by 5.6% in the first three months of the year despite raising its prices by 9.8%—its CEO said the company was simply matching cost increases over the previous two years.
“We’re still in the process of catching up with some of the hits we’ve taken,” said Mark Schneider in a call with analysts.
Elsewhere, the desire to boost margins, rather than just cover increased costs, appears to be one reason why food prices have continued to rise rapidly in Europe.
Much of the surge in food prices since the middle of last year stems from higher costs, particularly for energy, since most food production is quite energy-intensive. But economists at insurance company Allianz have calculated that about 10% of the rise reflects the search for higher profits. They suggest that is possible because key parts of the food-supply chain are dominated by a small number of firms.
“There is not enough competition in the food sector, especially in distribution,” said Ludovic Subran, chief economist at Allianz.
Not all businesses are opportunistically boosting their margins and Ms. Weber said that when some do, it can cause problems for others that are closer to the final consumer and are at greatest risk of facing a backlash.
Over recent months, Germany’s largest retailer, Edeka, has complained about the pricing behaviour of its suppliers of branded goods and has stopped stocking some of their products.
“We call on the branded-products industry to live up to its responsibility and stop artificially driving up inflation,” said Edeka’s CEO Markus Mosa.
There are some signs that food-price inflation is starting to slow. In France, food prices were 14.9% higher in April than a year earlier, a slowdown from 15.9% in March. In Germany, food inflation slowed to 17.2% from 22.3%. But the British Retail Consortium, a group that represents U.K. stores, said food inflation accelerated in April to hit a record high.
In recent earnings calls, some executives said consumers were becoming more resistant to price rises.
“We will probably see pricing moving down,” said Francois-Xavier Roger, Nestlé’s chief financial officer.
Last month, Procter & Gamble said it had boosted its profit margins in the first three months of the year, thanks in large part to higher prices. It warned that there were limits to how far it could push that tactic before consumers switched to cheaper alternatives.
“We’ve made several adjustments to price gaps, not just versus private label, but versus branded competition as we’ve gone through this period of pricing, and we need to continue to be sensitive to that,” said Jon Moeller, the company’s CEO.
For Mr. Donovan at UBS, the period of profit-driven inflation might be coming to an end, in part because of rising public scrutiny.
“We are probably at a point where companies may be reassessing whether to push this,” he said. “A reputation for being poor value for money stays for a long time.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


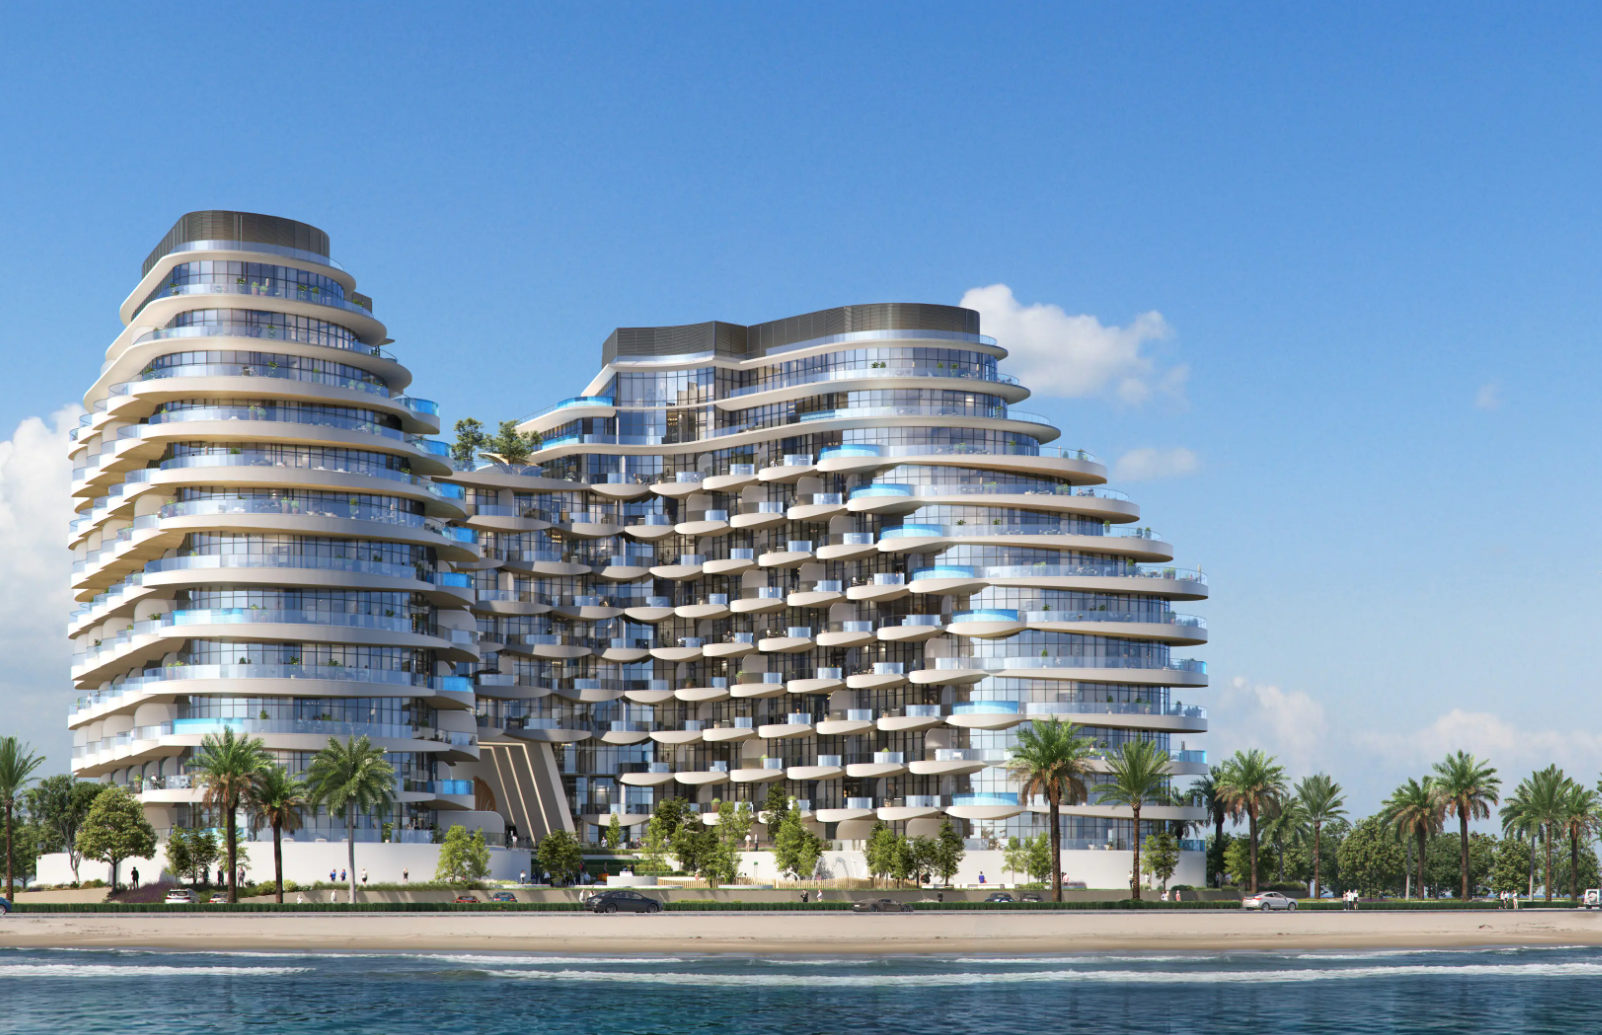
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”
 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
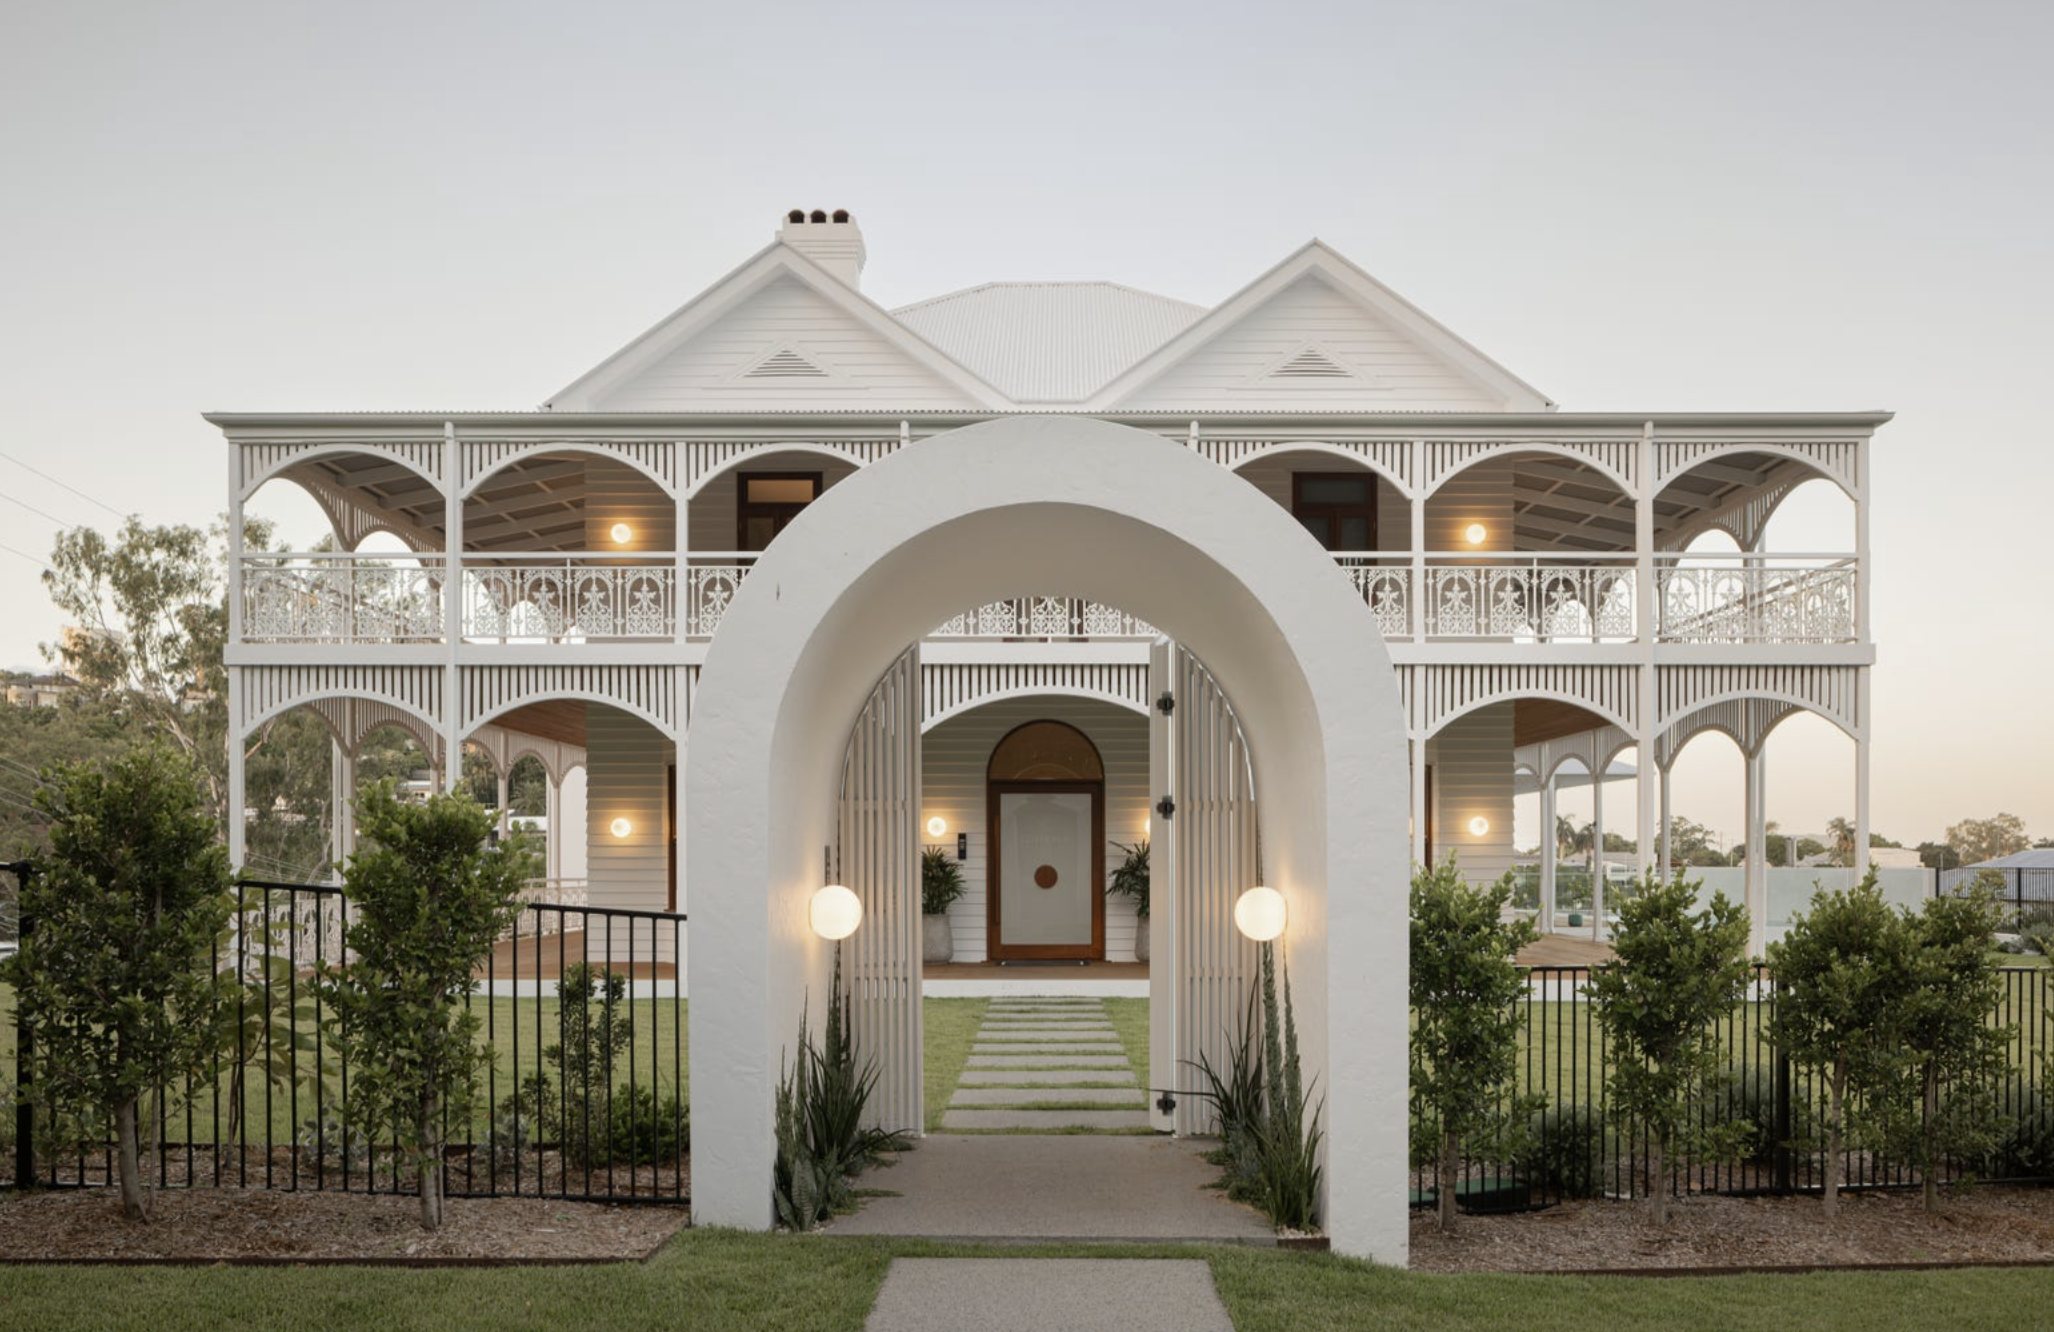
A restored 1860s Brisbane residence transformed by GRAYA has smashed Paddington’s house price record, selling for more than $12 million.

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.