Trump Administration Could Bring an Economic ‘Detox.’ What It Means for Stocks.
Investors may have nothing to fear but fear itself. But sometimes fear is more than enough.

 4 min

As another week begins with more selling–all three major indexes are falling, with the Nasdaq Composite hit hardest–fear is undoubtedly running high in the market. The Cboe Volatility Index, Wall Street’s fear gauge, jumped 15% to 27 on Monday morning. That would be its highest close since Dec. 18, when it was at 27.62.
Uncertainty about government policy and the health of the economy is overshadowing positive data.
Tariffs are one part of the problem. Not only are they disruptive to global trade and lead to higher prices, but President Donald Trump has walked back their implementation and doubled down enough to give the market whiplash. And then there are worries about huge cuts to federal spending, including mass firings and slashing outlays for programs, with a budget fight that could lead to a government shutdown at the end of the week.
Investors have little incentive to keep the faith, especially because signs of economic weakness are starting to emerge.
“Prior to tariff uncertainty, Momentum factors were leading, and risk factor returns were stable,” notes 22V Research’s Dennis DeBusschere. “ Payrolls and PMI data indicate weaker growth at the same time tariffs are adding to uncertainty about the path of economic data and earnings.” The result is that stocks are swinging wildly, riskier names are out of favor, and defensive shares are the flavor of the month.
According to Sevens Report’s Tom Essaye, “until there’s some movement towards stable policy, the best we can hope for is a churn sideways between around 5,700 and 6,000 in the S&P 500.” The index broke below 5650 in morning trading Monday.
The problem is that the greater the losses, the more the market could be closing in on a “liquidation avalanche,” as Dohmen Capital Research’s Bert Dohmen puts it. The concern is that forced selling, such as to raise cash for margin calls on shares bought with borrowed money, or by money managers desperate to limit losses, creates a downward spiral.
Wall Street famously abhors unpredictability, but even more worrisome may be rhetoric from Washington, D.C., that indicates the Trump administration is fine with causing what it believes will be a short-lived downturn as it pursues long-term goals it considers more important.
Asked whether a recession on the way, the president declined to rule out the possibility. “I hate to predict things like that,” Trump told Fox News’ Sunday Morning Futures. “There is a period of transition, because what we’re doing is very big. We’re bringing wealth back to America.”
Treasury Secretary Scott Bessent, a former hedge fund manager, predicted “a natural adjustment as we move away from public spending to private spending, in an interview with CNBC. “The market and the economy have just become hooked, and we’ve become addicted to this government spending, and there’s going to be a detox period. There’s going to be a detox.”
As T.S. Lombard’s Dario Perkins notes, Elon Musk and others in Trump’s orbit have pointed to Argentina as a successful example of this strategy. President Javier Milei imposed strict austerity measures to combat inflation, leading to a brief recession in 2024.
Of course, “copying the policies of a country that had massive endemic corruption and was on the brink of hyperinflation is, er, problematic,” Perkins writes. “Yes, inflation is a bit high, but not so high that Musk and co should deliberately engineer a recession. Perhaps the new U.S. administration has forgotten what a ‘real’ recession is like.”
The 2008-2009 financial crisis was nearly two decades ago, and the U.S. only rebounded from the Covid-19 downturn so quickly and strongly because of huge government spending. That means it is “odd to see US policymakers talk as if they want to inflict damage on the economy, or at least do things that risk causing damage,” he notes.
The White House didn’t immediately respond to a request for comment.
Damage could snowball quickly. If big government layoffs continue at a time when hiring is already weak, it could lead to a further loss of confidence and even higher unemployment. And as history shows, recessions aren’t always quick or without damage.
“The US is not Argentina, and it is not facing an imminent debt crisis,” Perkins writes. “In any case, does anyone seriously think a recession in 2025 would lower America’s debt trajectory? Every recession I know has had the exact opposite effect.”
The good news is that we aren’t there yet. Earnings have held up well, and while the mention of tariffs in fourth-quarter conference calls was up 40% from their prior peak in 2018, mentions of a recession fell to their lowest point since the first quarter of 2018, as DataTrek Research’s Nicolas Colas notes.
“The dichotomy between record high ‘tariff’ and near-record low ‘recession’ mentions on investor calls neatly reflects the mood of corporate America,” he writes. “The C-suite is struggling to come to grips with tariff policy but remains fairly optimistic on the US economy. So far, anyway…Any change to the latter view would be unwelcomed.”
For his part, TS Lombard’s Perkins isn’t predicting a recession. Sevens Reports’ Essaye notes that concern about tariffs so far has been worse than their effects. While it makes sense to brace for volatility, “that negative scenario is not a foregone conclusion and actual facts on the economy and earnings [are] hanging on.” he says.
22V Research’s DeBusschere highlights that in aggregate, macroeconomic data still point to a very high probability that the U.S. economy is still expanding. “Over the past few weeks though, market internals have weakened to a level more consistent with economic slowdowns/heightened recession risk,” he says. “Markets are discounting a sharp slowdown that is not evident TODAY in actual data.”
The problem is that as long as chaotic moves in Washington, D.C., continue, that won’t matter for stocks.
“Although the U.S. will still likely avoid a recession this year, investor sentiment does appear to be headed toward another recession scare,” writes Paulsen Perspectives’ Jim Paulsen. “An actual recession would probably result in a bear market, but even an ongoing or worsening ‘fear’ of recession will likely magnify the current stock market correction.”
When the market gets clarity about what comes next, prices can recover. But until then, it is hard to see how stocks can rise consistently. Just the fear of a recession is enough to weigh on markets.
Write to Teresa Rivas at teresa.rivas@barrons.com
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
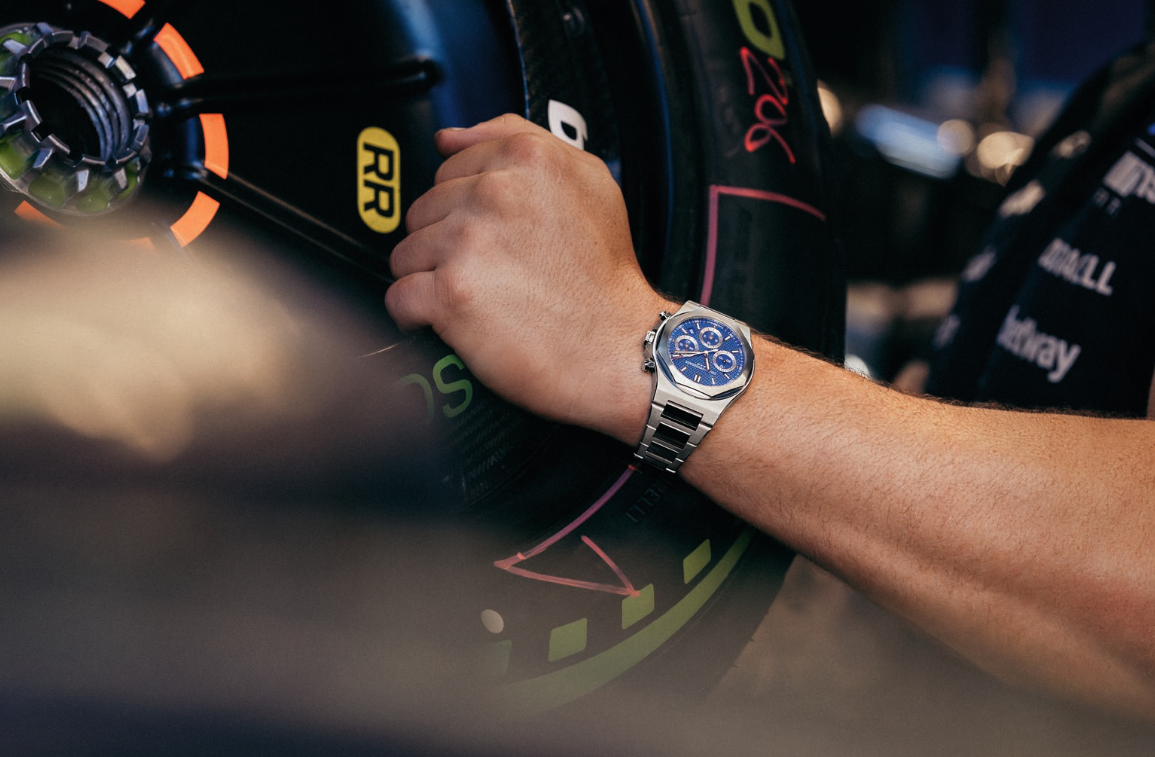
The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.
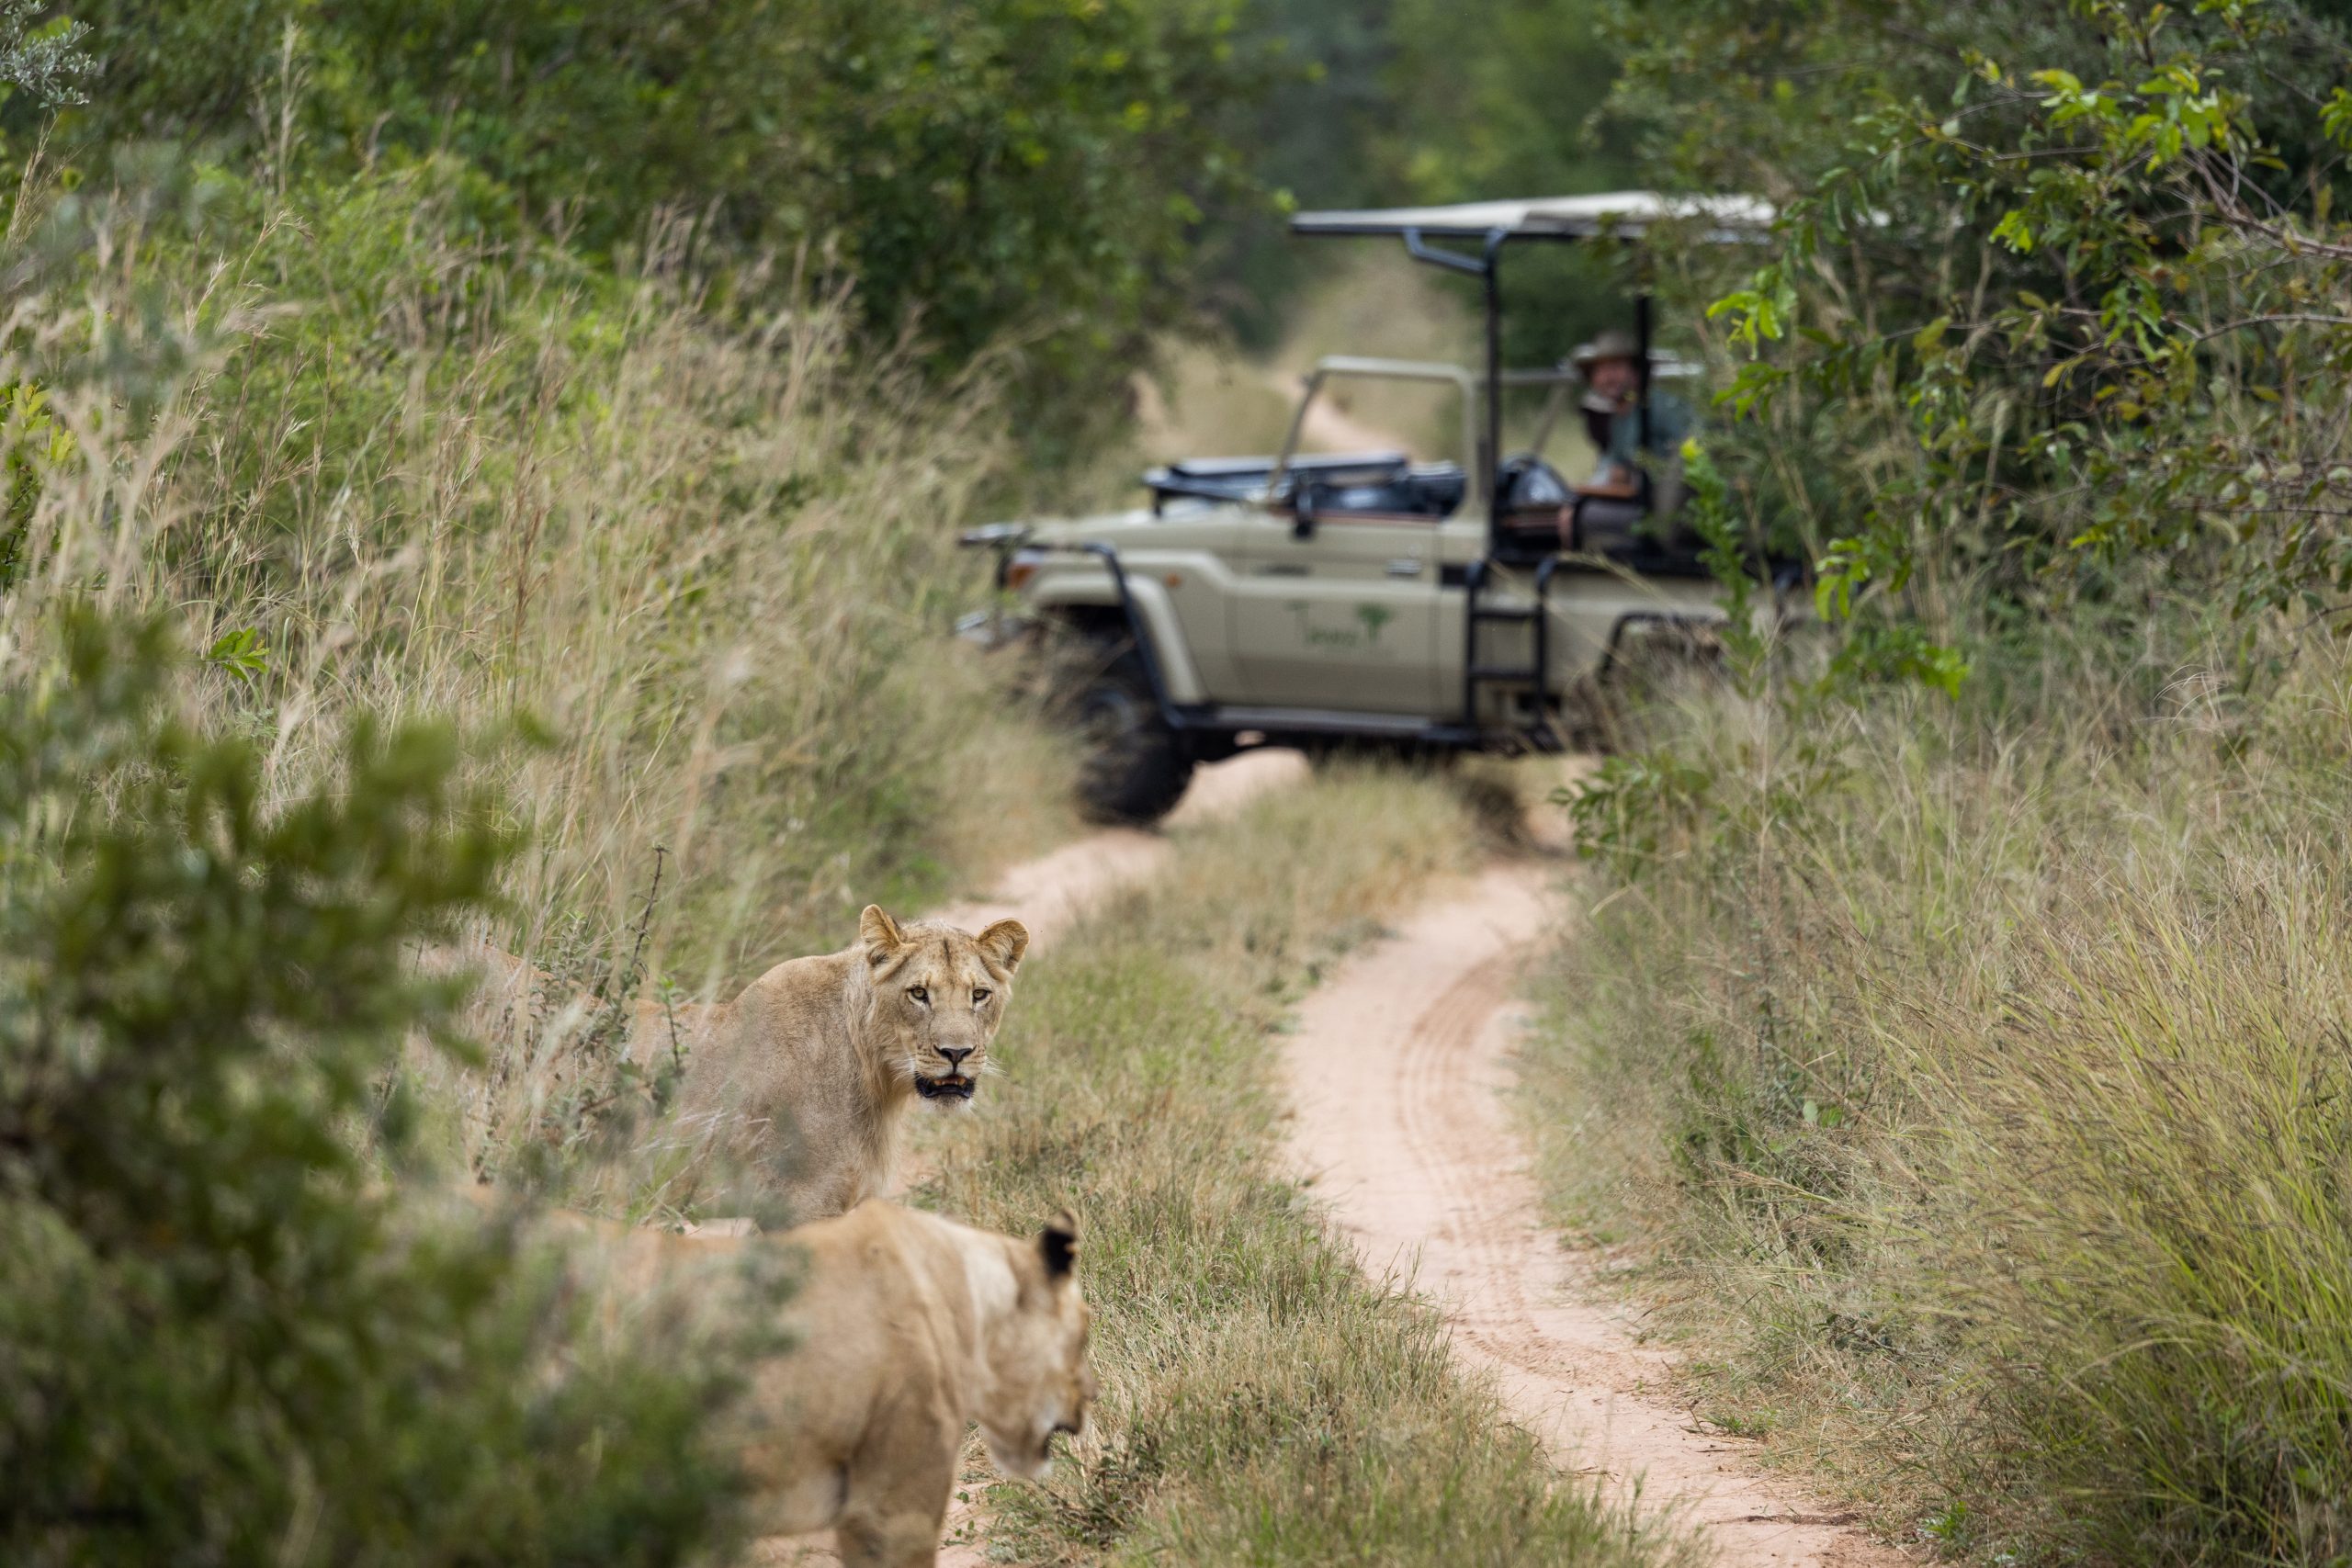
Exclusive eco-conscious lodges are attracting wealthy travellers seeking immersive experiences that prioritise conservation, community and restraint over excess.