




ETFs Are Replacing Property as the First Step for Young Investors
Among investors aged 18–29, 24 per cent use AI for investment advice, compared with 19 per cent using financial planners or advisers.
 2 min
ETF ownership has more than doubled since 2020, while Australians preparing to enter the market are showing substantially less interest in residential investment property.
For generations of Australians, the first serious investment tended to be a parcel of shares, a term deposit or a residential property.
That progression is changing as exchange-traded funds become one of the principal entry points into investing.
The ASX Australian Investor Study 2026 estimates that 2.82 million Australians now hold ETFs, more than double the 1.35 million recorded in 2020. ETF ownership has grown from 20 per cent of investors in 2023 to 24 per cent in 2026.
Among Australians intending to invest during the next 12 months, the shift is more pronounced. One-third expect to invest in ETFs, up from 21 per cent in 2023. Australian-listed shares remain the most popular prospective investment at 41 per cent, but ETFs are now comfortably in second place.
Residential investment property has moved in the opposite direction. The proportion of intending investors considering it fell from 36 per cent in 2023 to 20 per cent in 2026.
For investors aged between 18 and 29, ETFs now equal residential property as a first-ever investment. Each was nominated by 22 per cent of younger investors, while Australian-listed shares remained narrowly ahead at 26 per cent.
The comparison reflects a fundamental difference in accessibility. A residential investment can require a six-figure deposit, borrowing approval, stamp duty and the capacity to absorb ongoing maintenance and interest costs. An ETF can be purchased through an online brokerage account with a comparatively modest amount.
ETFs can also provide exposure to dozens or hundreds of underlying securities through a single transaction. That makes them attractive to newer investors who want diversification without researching and selecting numerous individual companies.
Their growth does not mean every ETF is simple or low risk. Products can track Australian shares, global markets, bonds, commodities, currencies, sectors or highly concentrated investment themes. Leveraged and inverse funds introduce additional complexity.
Investors still need to understand what a fund owns, its fees, index methodology, liquidity, currency exposure and the risks particular to its strategy.
The number of available products is expanding alongside demand. At 30 June 2026, 458 ETFs were quoted on the ASX, up from 298 three years earlier. Their combined market capitalisation had reached $361 billion, representing growth of almost 33 per cent over 12 months.
Participation is also relatively balanced between men and women. Twenty-six per cent of male investors and 22 per cent of female investors hold or trade ETFs—a narrower gender gap than that found in cryptocurrency and overseas shares.
The strongest ETF participation comes from investors aged between 30 and 49, at 34 per cent, followed by those aged 18 to 29 at 31 per cent. Activity falls to 16 per cent among pre-retirees and 8 per cent among retirees.
Property remains an important component of Australian household wealth, and the study does not suggest young people have abandoned home ownership. It does show that listed funds increasingly offer a more achievable first step for those who cannot—or do not want to—begin with real estate.
ETF snapshot
Australians holding ETFs: 2.82 million
ETF investors in 2020: 1.35 million
Share of current investors holding ETFs: 24 per cent
Intending investors considering ETFs: 33 per cent
Intending investors considering residential property: 20 per cent
ETFs quoted on ASX at 30 June 2026: 458
Combined ASX ETF market capitalisation: $361 billion
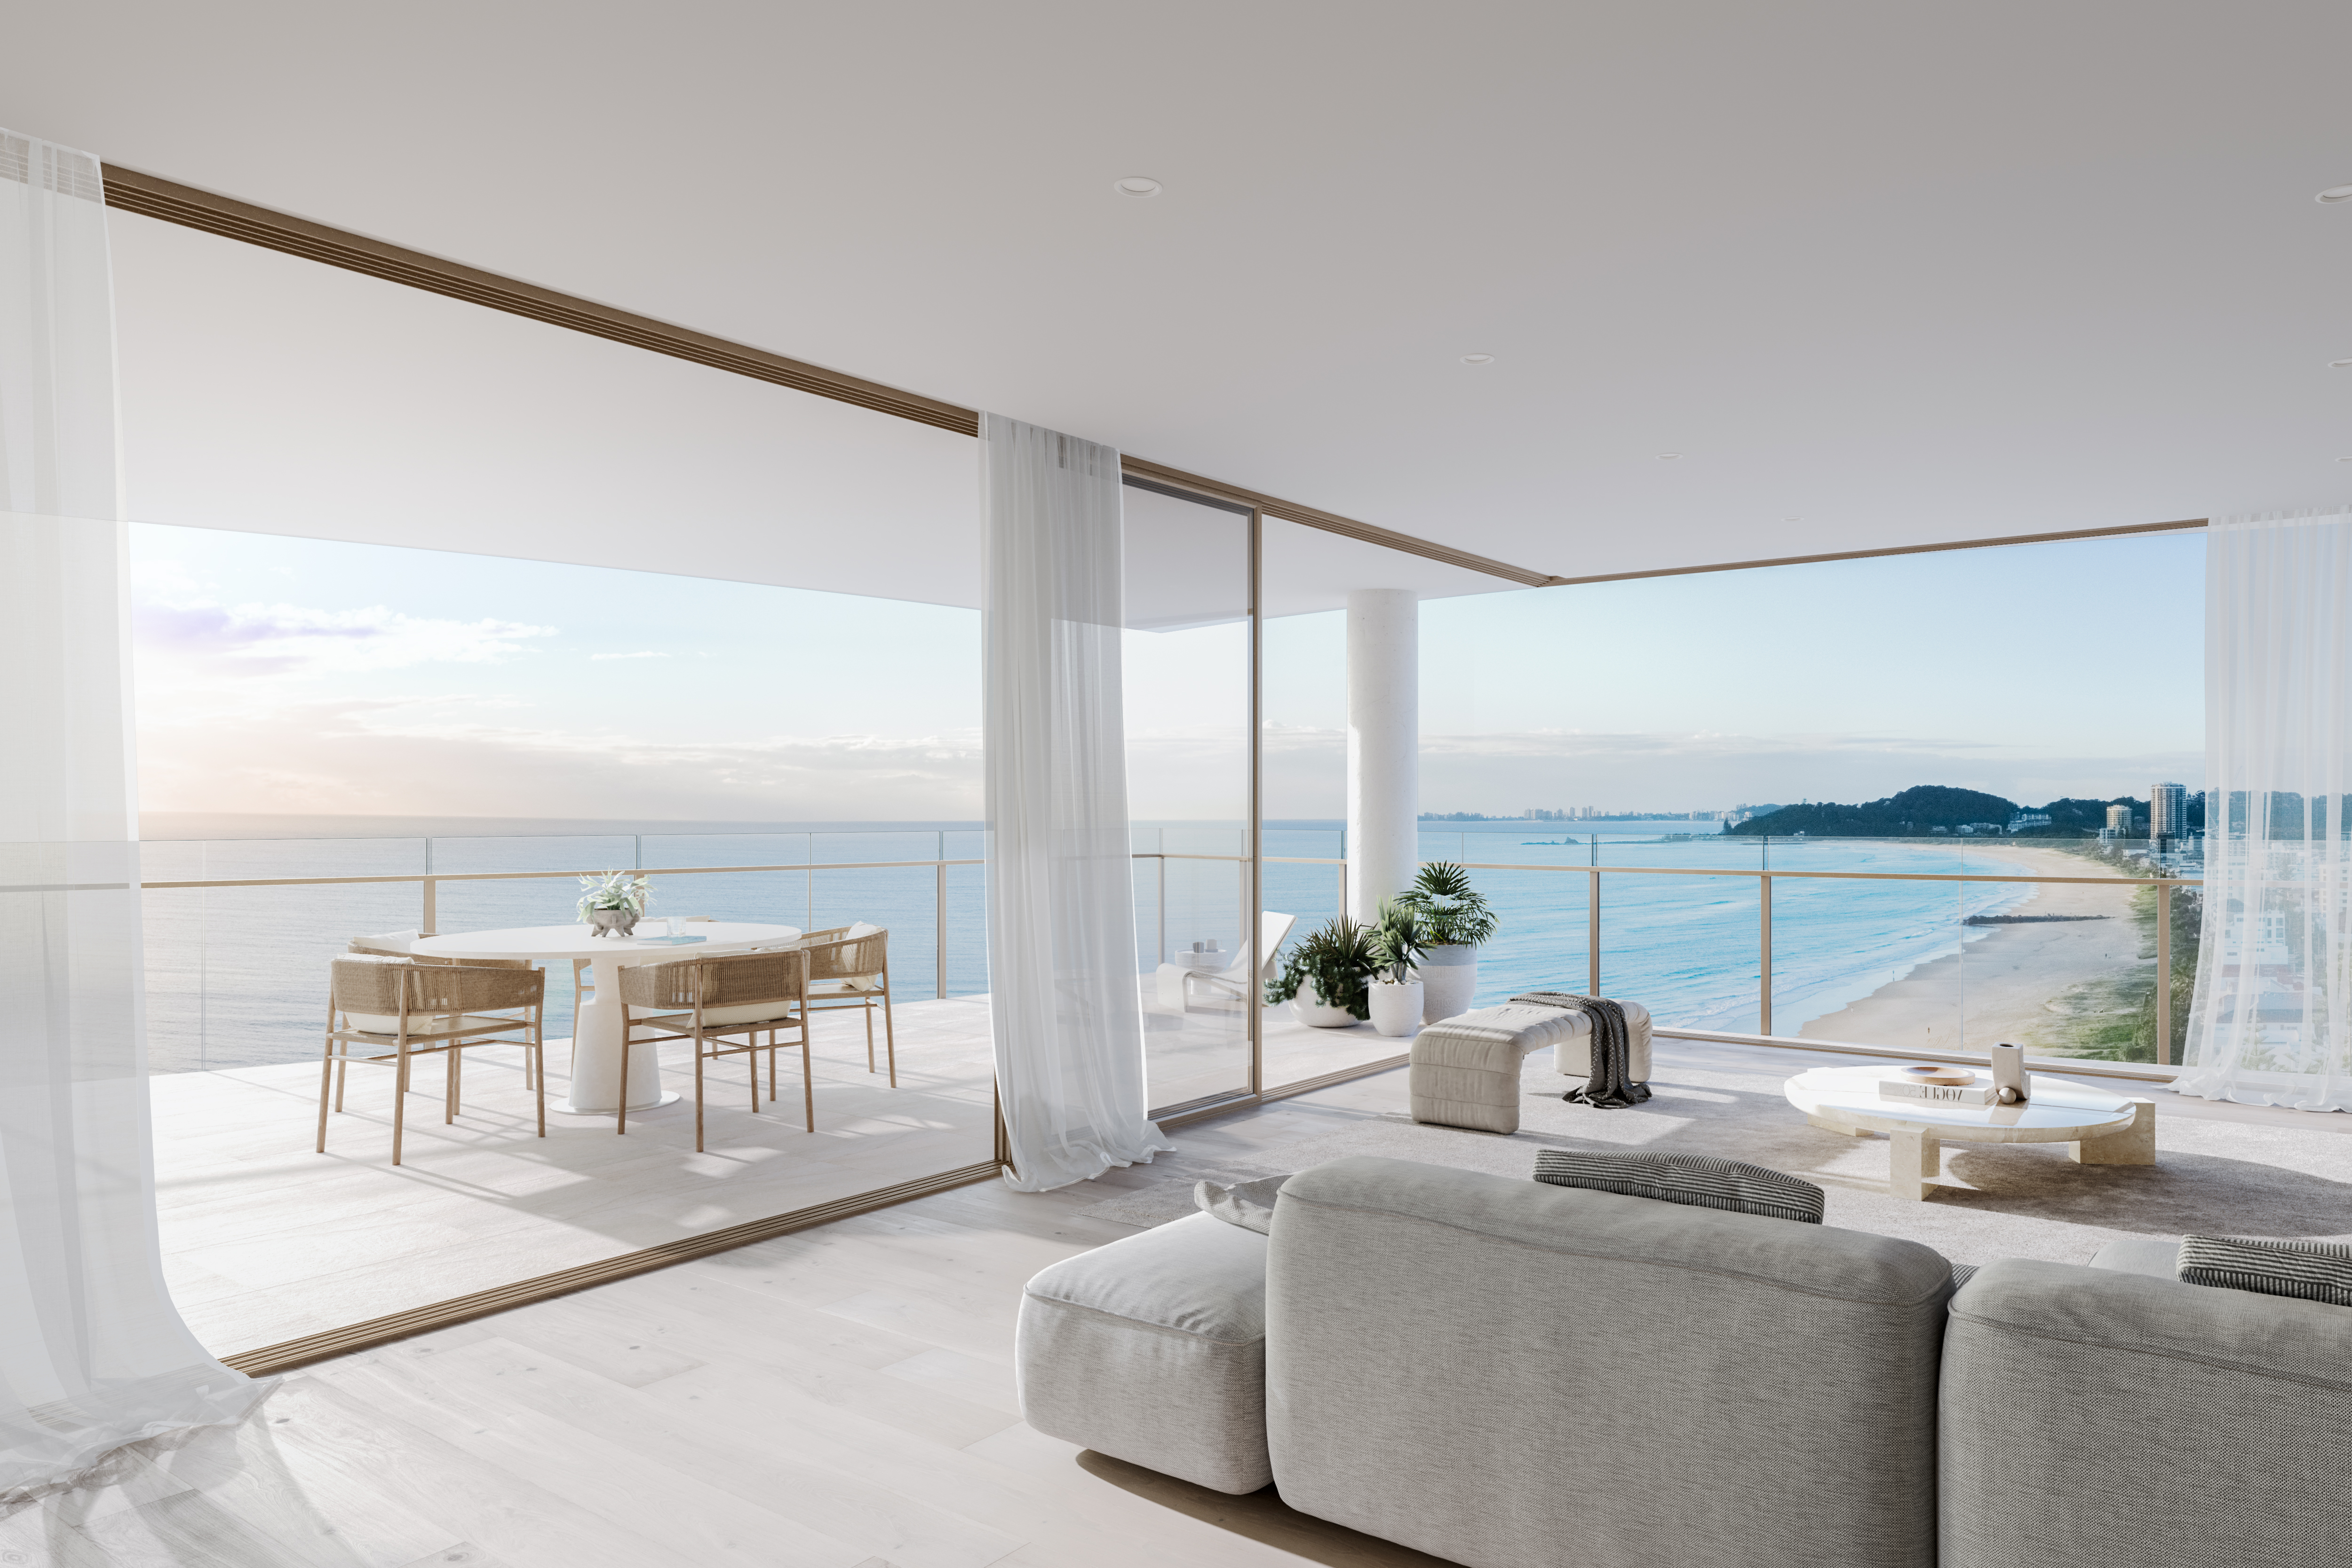
A Sydney couple has paid $15.5 million for the Grand Penthouse at Marquee’s $285 million La Belle Residences beachfront development which is nearing completion at Palm Beach, eclipsing the record for an off-the-plan apartment sale on the southern Gold Coast. The sprawling single level 640 sqm beachfront residence, with sweeping views of the Gold Coast …
Continue reading “$15.5m La Belle Penthouse eclipses southern Gold Coast record”
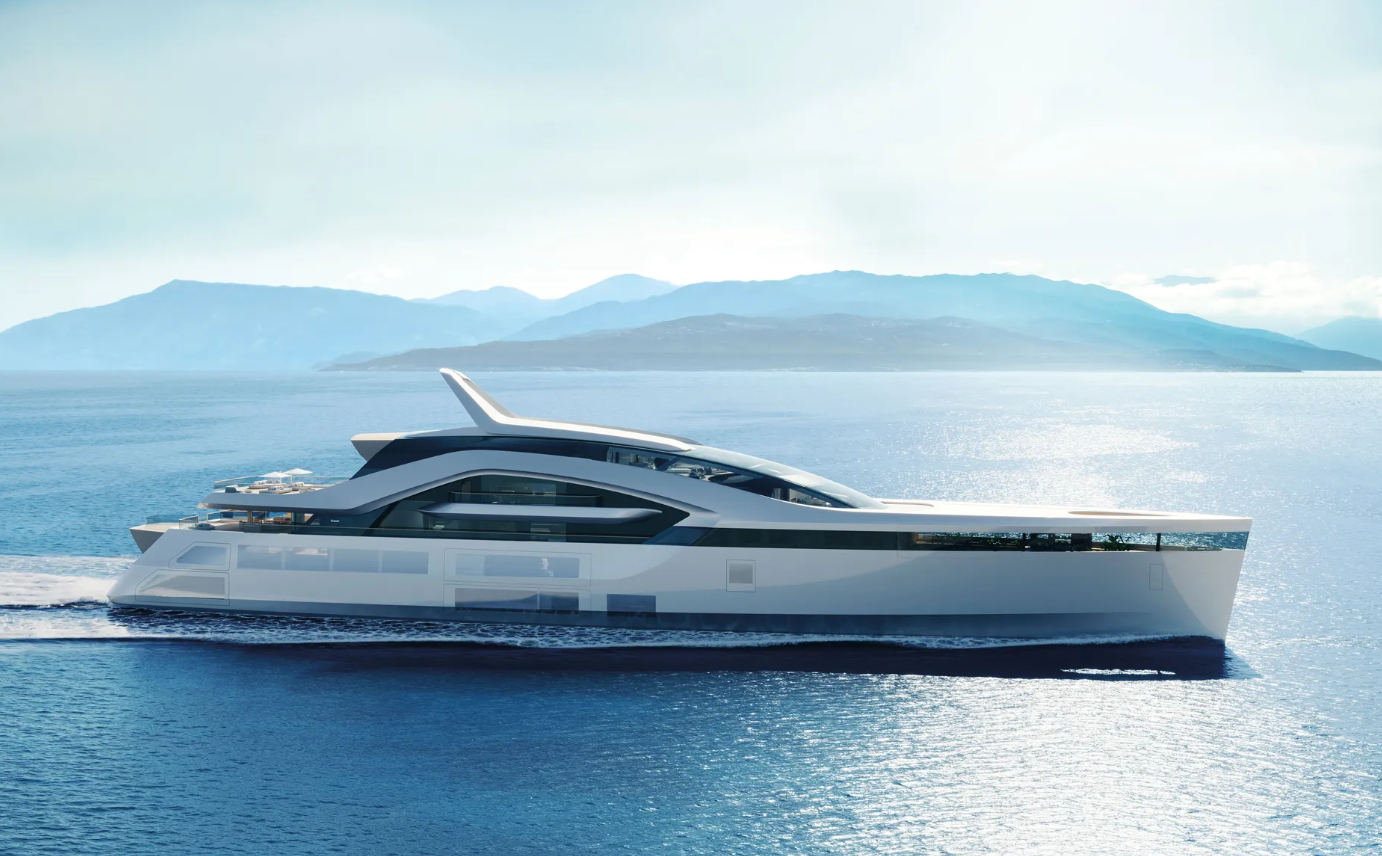
On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
The ASX 200 rose 1.28 per cent in the week ending 30 October as miners rallied, consumer stocks fell and rate-rise expectations climbed
6 min
The Australian sharemarket rose during four of five sessions in the week ending 30 October, but the headline gain concealed a sharp divide between recovering miners, rate-sensitive property stocks and retailers hit by inflation and weaker trading updates.
The Australian sharemarket finished October with a positive week, although the route higher was anything but uniform.
The S&P/ASX 200 closed Friday 30 October at 8,908.1, gaining 112.9 points, or 1.28 per cent, from the previous Friday’s close of 8,795.2.
The All Ordinaries advanced 1.34 per cent to 9,025, while the more concentrated S&P/ASX 20 gained 1.11 per cent.
The benchmark rose during four of the week’s five sessions. It added 0.17 per cent on Monday and 0.46 per cent on Tuesday, before slipping 0.03 per cent on Wednesday. It recovered 0.50 per cent on Thursday and gained another 0.18 per cent on Friday.
The index briefly reached 8,933.3 but again failed to establish itself above the psychologically important 9,000-point mark.
The week’s central tension was between a resources recovery and a less forgiving domestic interest-rate outlook.
Materials gained 4.06 per cent, reclaiming part of the previous week’s heavy fall. Australian real estate investment trusts rose 3.77 per cent, financials gained 1.05 per cent and energy advanced 1.39 per cent.
At the other end of the market, consumer staples fell 5.13 per cent and consumer discretionary shares lost 2.35 per cent. Utilities declined 0.73 per cent and communication services eased 0.68 per cent.
Inflation changes the conversation
Australia’s September inflation data was the week’s pivotal domestic release.
Annual inflation of 4.3 per cent pushed market pricing towards another possible Reserve Bank increase and disrupted Wednesday’s early sharemarket rally.
By Thursday’s close, one widely followed market measure placed the probability of an increase in the cash rate to 4.85 per cent at approximately 80 per cent.
That pricing does not make an increase certain. It does, however, change the framework through which investors assess Australian businesses.
Companies dependent on discretionary household spending face renewed pressure on sales and margins. Property trusts, banks, developers and highly leveraged companies must be considered against the prospect of higher funding costs.
Banks present a more complicated equation. Higher rates can support margins, but they may also slow credit growth and increase arrears.
Miners recover
BHP gained 4.56 per cent across the week to close at $57.56, making a substantial contribution to the benchmark’s rise.
The recovery followed an 8.3 per cent fall during the previous week and helped lift the broader materials sector.
Northern Star Resources added 4.59 per cent, while Goodman Group advanced 6.85 per cent to become the strongest performer in the ASX 20.
The commodities picture was mixed. Gold fell approximately 3.12 per cent on the cited weekly measure, while Brent crude added around 0.68 per cent.
The Australian dollar was little changed at approximately US70.35 cents at the reference point.
Supermarkets and consumer shares retreat
The consumer-staples story was markedly weaker.
Coles fell 11.77 per cent after its first-quarter update, making it one of the largest significant-company declines of the week.
Woolworths lost 3.66 per cent and Wesfarmers fell 4.48 per cent to $76.69 as investors processed company trading commentary against the prospect of another squeeze on household demand.
The moves illustrate how quickly expectations can change when an apparently defensive company disappoints.
Supermarkets still benefit from the recurring need for groceries, but customers can trade down, shift between chains and reduce spending on higher-margin discretionary lines.
Wesfarmers carries exposure to several consumer categories through businesses including Bunnings, Kmart and Officeworks. A renewed rate increase would place more pressure on households already confronting higher prices.
The wider market’s biggest movements
Among companies outside the ASX 20, Mesoblast surged 27.32 per cent, SiteMinder gained 22.74 per cent and Zip rose 22.60 per cent.
The sharpest weekly falls included 4DMedical, down 33.51 per cent; Tuas, down 29.95 per cent; Catalyst Metals, down 17.47 per cent; and Champion Iron, down 13.35 per cent.
Those percentages require context.
The movements in BHP, Commonwealth Bank and other very large companies had substantially more influence on the index than similarly dramatic changes among smaller companies.
A 20 per cent move in a relatively small stock may attract more attention than a two per cent rise in a major bank, but the bank can have the greater effect on the market.
How the ASX 20 moved
The following list uses the S&P/ASX 20 constituents and five-session movements reported at the 30 October close.
Where the component feed did not publish a valid five-day comparison, no figure has been estimated.
BHP Group: Up 4.56 per cent
Commonwealth Bank: Up 1.66 per cent
Rio Tinto: Down 2.20 per cent
National Australia Bank: Up 0.48 per cent
Westpac: Up 0.08 per cent
ANZ Group: Up 1.92 per cent
CSL: Up 2.05 per cent
Macquarie Group: Up 2.19 per cent
Wesfarmers: Down 4.48 per cent
Woodside Energy: Up 1.43 per cent
Goodman Group: Up 6.85 per cent
Telstra: Five-day comparison unavailable from the cited component feed
Woolworths: Down 3.66 per cent
Fortescue: Five-day comparison unavailable from the cited component feed
Transurban: Down 2.40 per cent
QBE Insurance: Down 1.21 per cent
Aristocrat Leisure: Up 0.63 per cent
Northern Star Resources: Up 4.59 per cent
Sigma Healthcare: Down 0.36 per cent
Brambles: Down 1.20 per cent
The companies dominating the conversation
Coles was the week’s standout media-facing company for the wrong reason.
Its trading update produced an outsized repricing and drew attention across the grocery and retail sectors. Woolworths and Wesfarmers were also scrutinised as investors considered how stubborn inflation and another possible rate rise could affect sales volumes.
Bank of Queensland offered a more positive corporate signal.
The bank reported that its FY26 net interest margin had risen six basis points to 1.70 per cent, ahead of the 1.68 per cent expected by the market according to contemporaneous reporting.
Bank of Queensland shares rose 5.8 per cent on Thursday, while the major banks also rallied.
Endeavour Group finished Friday at $3.39, up 4.31 per cent on the day, and released the results of its annual general meeting.
The movement was notable during a week in which investors were highly sensitive to consumer-facing companies. The AGM result should not, however, be presented as the sole cause of the share-price increase without further supporting company guidance.
Mesoblast’s 23.4 per cent Thursday rise and 27.32 per cent weekly gain returned the biotechnology company to the centre of market attention.
For editors, it is important to separate the size of that percentage movement from its influence on the index. Mesoblast was an eye-catching performer, but it did not drive the ASX 200 in the way BHP or Commonwealth Bank did.
Qantas remained part of the broader market conversation as investors watched travel demand and company updates.
However, the primary-source review did not locate a fresh Qantas announcement that justified attributing a major weekly market movement to new company information. The airline should therefore remain on the monitoring list rather than being forced into the week’s causal narrative.
Is Australia’s IPO market reopening?
The official ASX new-listings pipeline remains active but selective.
ASX’s upcoming-floats page included formal applications with offer timetables extending through October and at least one anticipated listing on 30 November.
The exchange notes that its page covers companies for which a formal listing application has been received. It does not represent every company privately exploring a float.
The wider debate concerns whether Australia’s public market is sufficiently competitive when high-growth businesses can pursue capital in the United States or remain privately funded for longer.
ASX has previously raised possible reforms designed to improve the attractiveness of the local market. These include debate about reducing minimum free-float requirements and streamlining aspects of the admissions process.
An enhanced fast-track pathway for qualifying applicants can shorten the review process, reducing the execution risk created when market conditions change during a long IPO timetable.
That does not remove the more fundamental challenge.
New floats still require credible earnings or a convincing growth pathway, sensible pricing and enough genuine free float to support trading after listing.
Investors can already obtain diversified exposure through low-cost exchange-traded funds or buy established, liquid businesses. A float must therefore offer more than novelty.
The current pipeline suggests that the IPO window is open, but it is not indiscriminate.
What investors will watch next
The Reserve Bank’s next decision now sits at the centre of the domestic outlook.
Any change in cash-rate expectations will flow rapidly through banks, retailers, property trusts, listed developers and companies carrying substantial debt.
Investors will also watch whether the materials recovery can continue, whether BHP can hold its rebound and whether consumer companies provide further evidence of slowing demand.
Overseas, technology-sector volatility, commodity prices and the United States interest-rate outlook will continue to shape Australian trading.
The week’s 1.28 per cent headline gain was encouraging, but it was not a broad declaration of confidence.
It was a rotation towards miners, selected financials and property securities—and away from consumer businesses facing a more difficult inflation and interest-rate equation.
Market dashboard
S&P/ASX 200: 8,908.1, up 1.28 per cent for the week
All Ordinaries: 9,025, up 1.34 per cent
S&P/ASX 20: 5,214.7, up 1.11 per cent over five sessions
Best sector: Materials, up 4.06 per cent
Next-best sector: A-REITs, up 3.77 per cent
Weakest sector: Consumer staples, down 5.13 per cent
Major large-cap winner: Goodman Group, up 6.85 per cent
Major large-cap loser: Coles, down 11.77 per cent
AUD/USD: Approximately US70.35 cents at the weekly reference point
Gold: Approximately US$3,885 an ounce, down 3.12 per cent on the cited weekly measure
Brent crude: Approximately US$117.70 a barrel, up 0.68 per cent on the cited weekly measure

Rugged coastal drives and fireside drams define a slow, indulgent journey through Scotland’s far north.
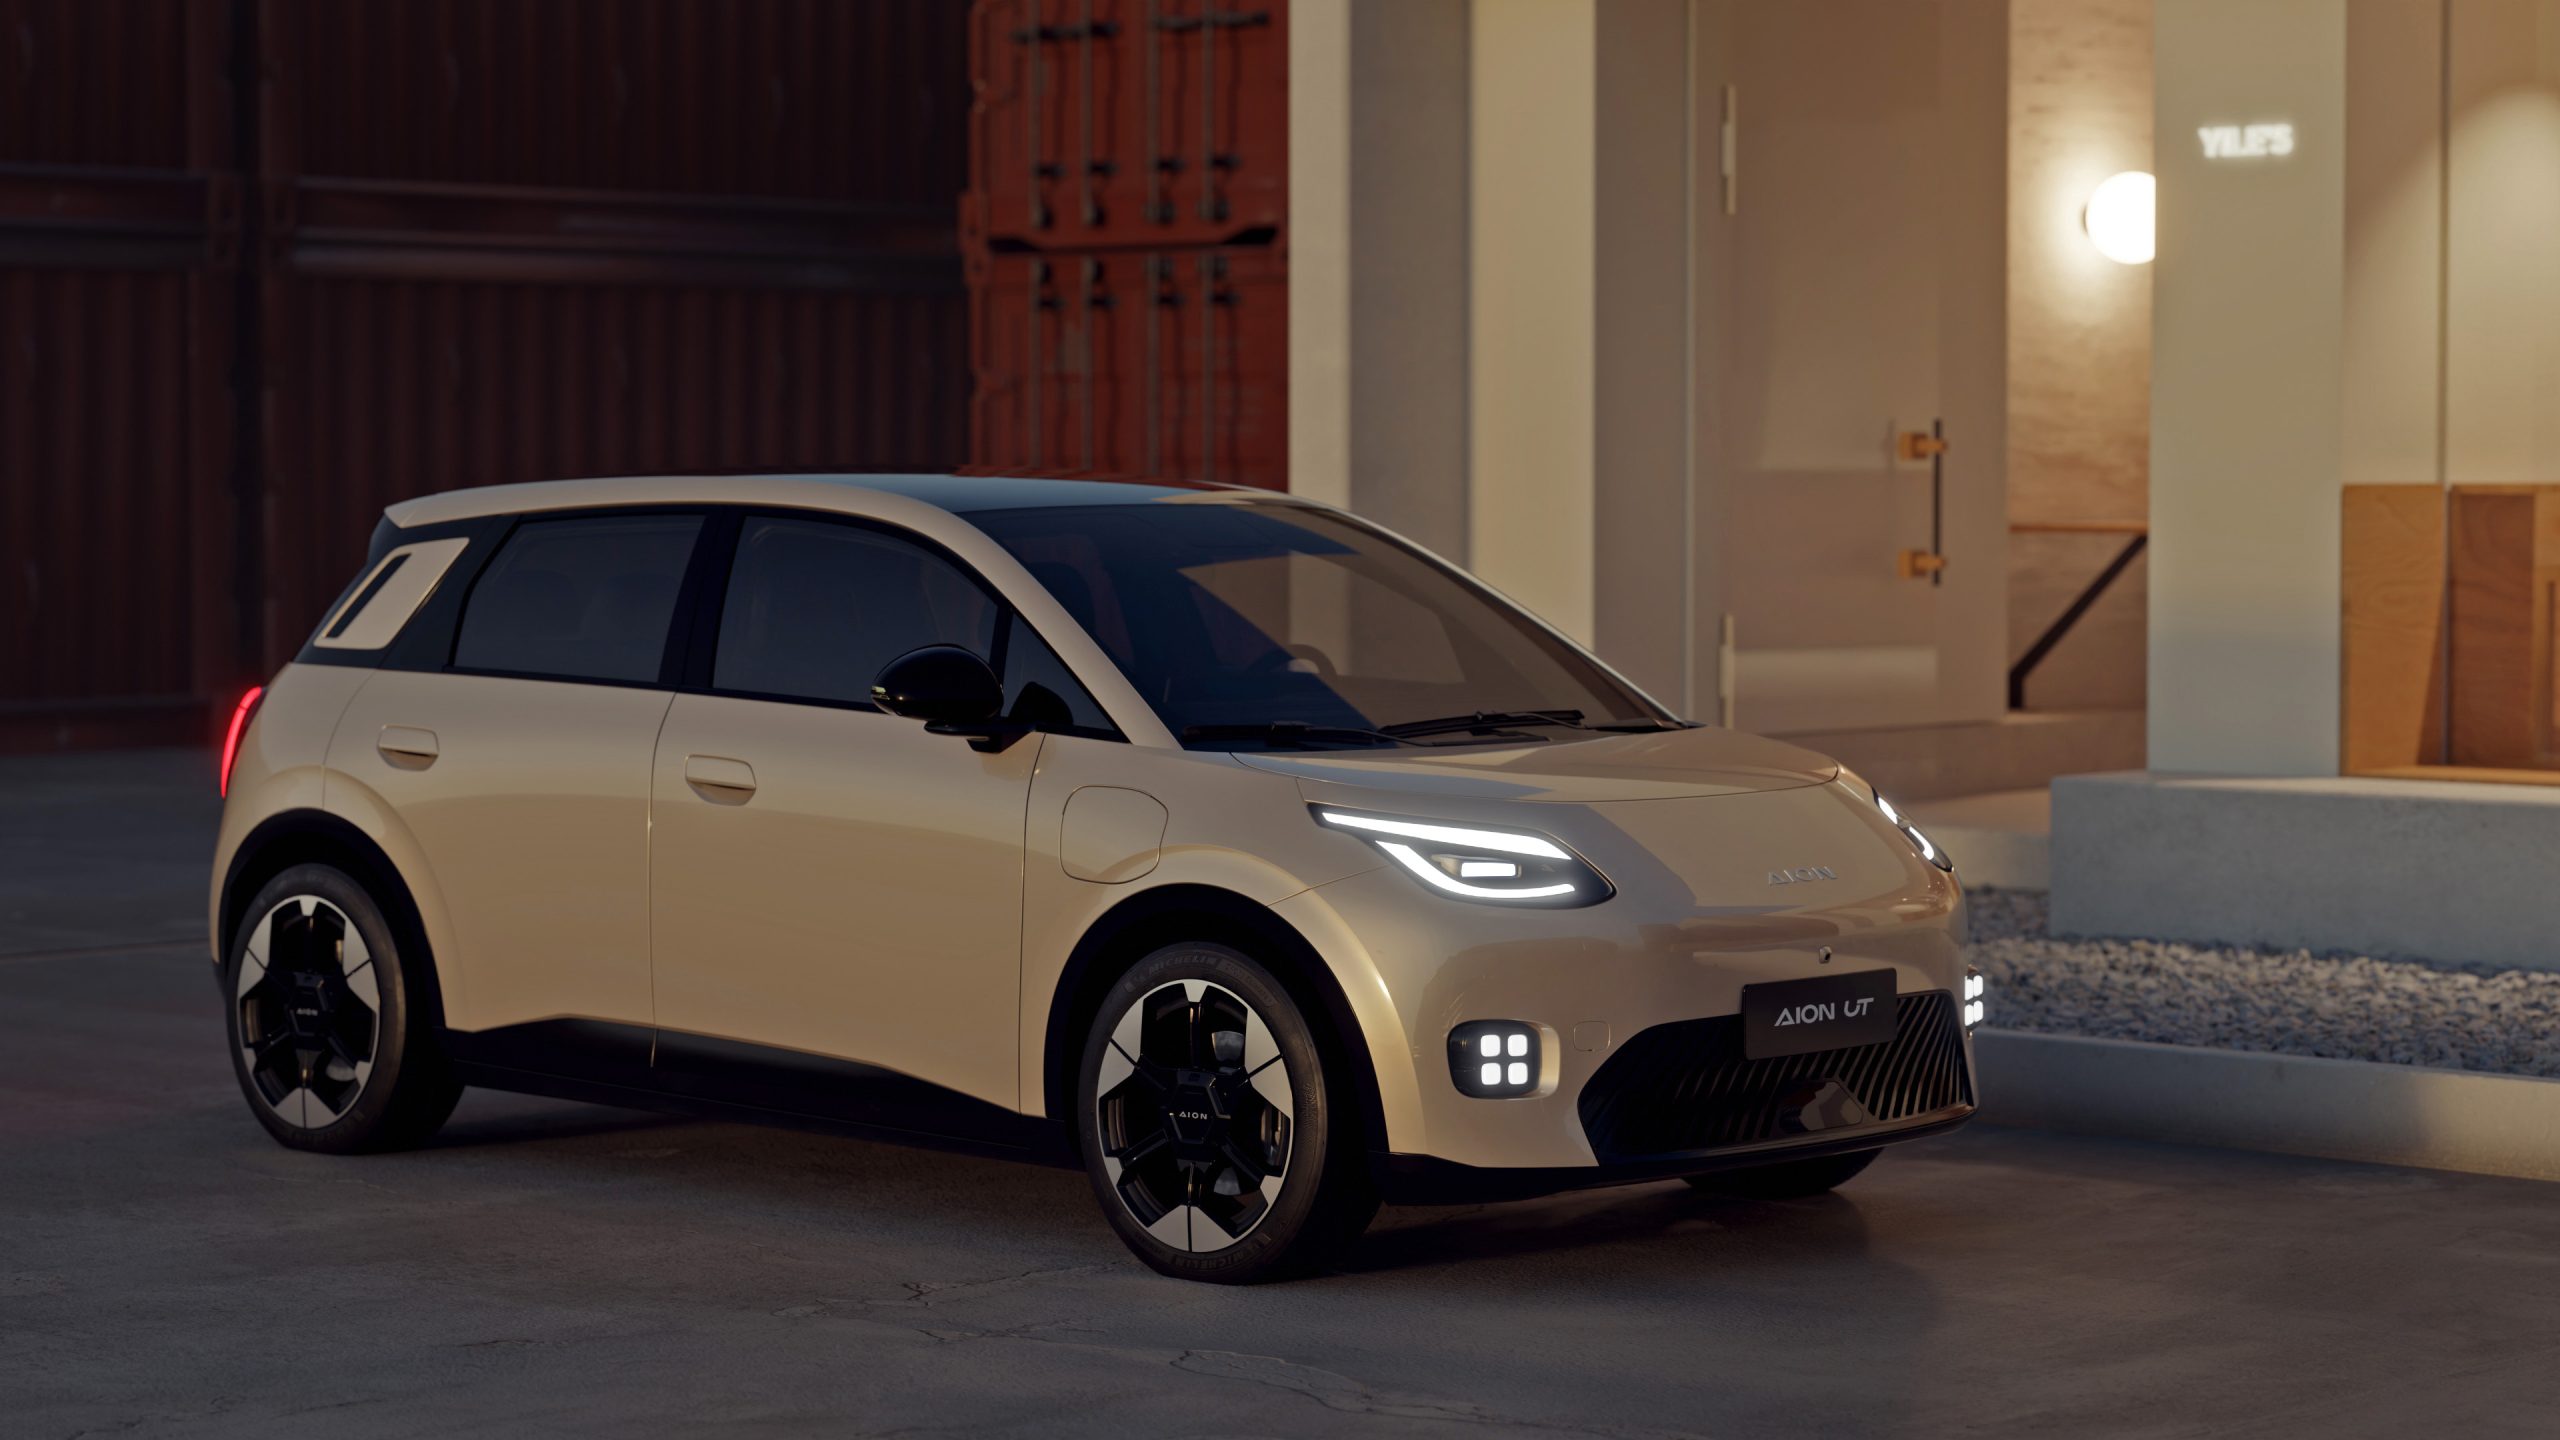
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.


