A Killer Golf Swing Is a Hot Job Skill Now
Companies are eager to hire strong players who use hybrid work schedules to schmooze clients on the course

 5 min
Standout golfers who aren’t quite PGA Tour material now have somewhere else to play professionally: Corporate America.
People who can smash 300-yard drives and sink birdie putts are sought-after hires in finance, consulting, sales and other industries, recruiters say. In the hybrid work era, the business golf outing is back in a big way.
Executive recruiter Shawn Cole says he gets so many requests to find ace golfers that he records candidates’ handicaps, an index based on average number of strokes over par, in the information packets he submits to clients. Golf alone can’t get you a plum job, he says—but not playing could cost you one.
“I know a guy that literally flies around the world in a private jet loaded with French wine, and he golfs and lands hundred-million-dollar deals,” Cole says.
Tee times and networking sessions have long gone hand-in-golf-glove. Despite criticism that doing business on the course undermines diversity, equity and inclusion efforts—and the fact that golf clubs haven’t always been open to women and minorities —people who mix golf and work say the outings are one of the last reprieves from 30-minute calendar blocks
Stars like Tiger Woods and Michelle Wie West helped expand participation in the sport. Still, just 22% of golfers are nonwhite and 26% are women, according to the National Golf Foundation.
To lure more people, clubs have relaxed rules against mobile-phone use on the course, embracing white-collar professionals who want to entertain clients on the links without disconnecting from the office. It’s no longer taboo to check email from your cart or take a quick call at the halfway turn.
With so much other business conducted virtually, shaking hands on the green and schmoozing over clubhouse beers is now seen as making an extra effort, not slacking off.
Americans played a record 531 million rounds last year. Weekday play has nearly doubled since 2019, with much of the action during business hours , according to research by Stanford University economist Nicholas Bloom .
“It would’ve been scandalous in 2019 to be having multiple meetings a week on the golf course,” Bloom says. “In 2024, if you’re producing results, no one’s going to see anything wrong with it.”
A financial adviser at a major Wall Street bank who competes on the amateur circuit told me he completes 90% of his tasks by 10 a.m. because he manages long-term investment plans that change infrequently. The rest of his workday often involves golfing with clients and prospects. He’s a member of a private club with a multiyear waiting list, and people jump at the chance to join him on a course they normally can’t access.
There is an art to bringing in business this way. He never initiates shoptalk, telling his playing partners the round is about having fun and getting to know each other. They can’t resist asking about investment strategies by the back nine, he says.
Work hard, play hard
Matt Parziale golfed professionally on minor-league tours for several years, but when his dream of making the big time ended, he had to get a regular job. He became a firefighter, like his dad.
A few years later he won one of the biggest amateur tournaments in the country, earning spots in the 2018 Masters and U.S. Open, where he tied for first among non-pros.
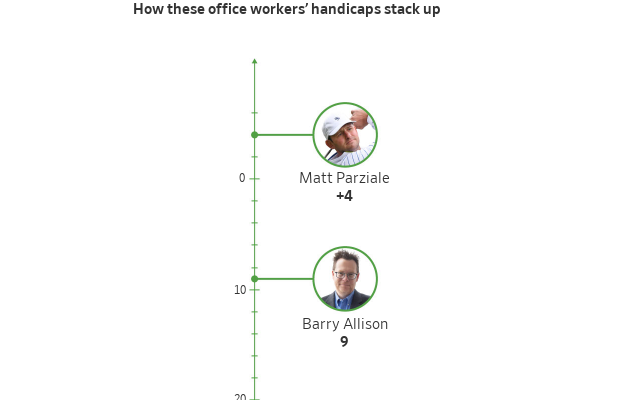
The brush with celebrity brought introductions to business types that Parziale, 35 years old, says he wouldn’t have met otherwise. One connection led to a job with a large insurance broker. In 2022 he jumped to Deland, Gibson Insurance Associates in Wellesley, Mass., which recognised his golf game as a tool to help win large accounts.
He rescheduled our interview because he was hosting clients at a private club on Cape Cod, and squeezed me in the next morning, before teeing off with a business group in Newport, R.I.
A short time ago, Parziale couldn’t imagine making a living this way. Now he’s the norm in elite amateur golf circles.
“I look around at the guys at the events I play, and they all have these jobs ,” he says.
His boss, Chief Executive Chip Gibson, says Parziale is good at bringing in business because he puts as much effort into building relationships as honing his game. A golf outing is merely an opportunity to build trust that can eventually lead to a deal, and it’s a misconception that people who golf during work hours don’t work hard, he says.
Barry Allison’s single-digit handicap is an asset in his role as a management consultant at Accenture , where he specialises in travel and hospitality. He splits time between Washington, D.C., and The Villages, Fla., a golf mecca that boasts more than 50 courses.
It can be hard to get to know people in distributed work environments, he says. Go golfing and you’ll learn a lot about someone’s temperament—especially after a bad shot.
“If you see a guy snap a club over his knee, you don’t know what he’s going to snap next,” Allison says.
Special access
On a recent afternoon I was a lunch guest at Brae Burn Country Club, a private enclave outside Boston that was the site of U.S. Golf Association championships won by legends like Walter Hagen and Bobby Jones. I parked in the second lot because the first one was full—on a Wednesday.
My host was Cullen Onstott, managing director of the Onstott Group executive search firm and a former collegiate golfer at Fairfield University. He explained one reason companies prize excellent golfers is they can put well-practiced swings on autopilot and devote most of their attention to chitchat.
It’s hard to talk with potential customers about their needs and interests when you’re hunting for errant shots in the woods. It’s also challenging if you show off.
The first hole at Brae Burn is a 318-yard par 4 that slopes down, enabling big hitters like Onstott to reach the putting green in a single stroke. But to stay close to his playing partners and keep the conversation flowing, he sometimes hits a shorter shot.
Having an “in” at an exclusive club can make you a catch. Bo Burch, an executive recruiter in North Carolina, says clubs in his region tend to attract members according to their business sectors. One might be chock-full of real-estate investors while another has potential buyers of industrial manufacturing equipment.
Burch looks for candidates who are members of clubs that align with his clients’ industries, though he stresses that business acumen comes first when filling positions.
Tami McQueen, a former Division I tennis player and current chief marketing officer at Atlanta investment firm BIP Capital, signed up for private golf lessons this year. She had noticed colleagues were wearing polos with course logos and bringing their clubs to work. She wanted in.
McQueen joined business associates on the golf course for the first time in March at the PGA National Resort in Palm Beach Gardens, Fla. She has lowered her handicap to a respectable 26 and says her new skill lends a professional edge.
“To be able to say, ‘I can play with you and we can have those business meetings on the course’ definitely opens a lot more doors,” she says.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
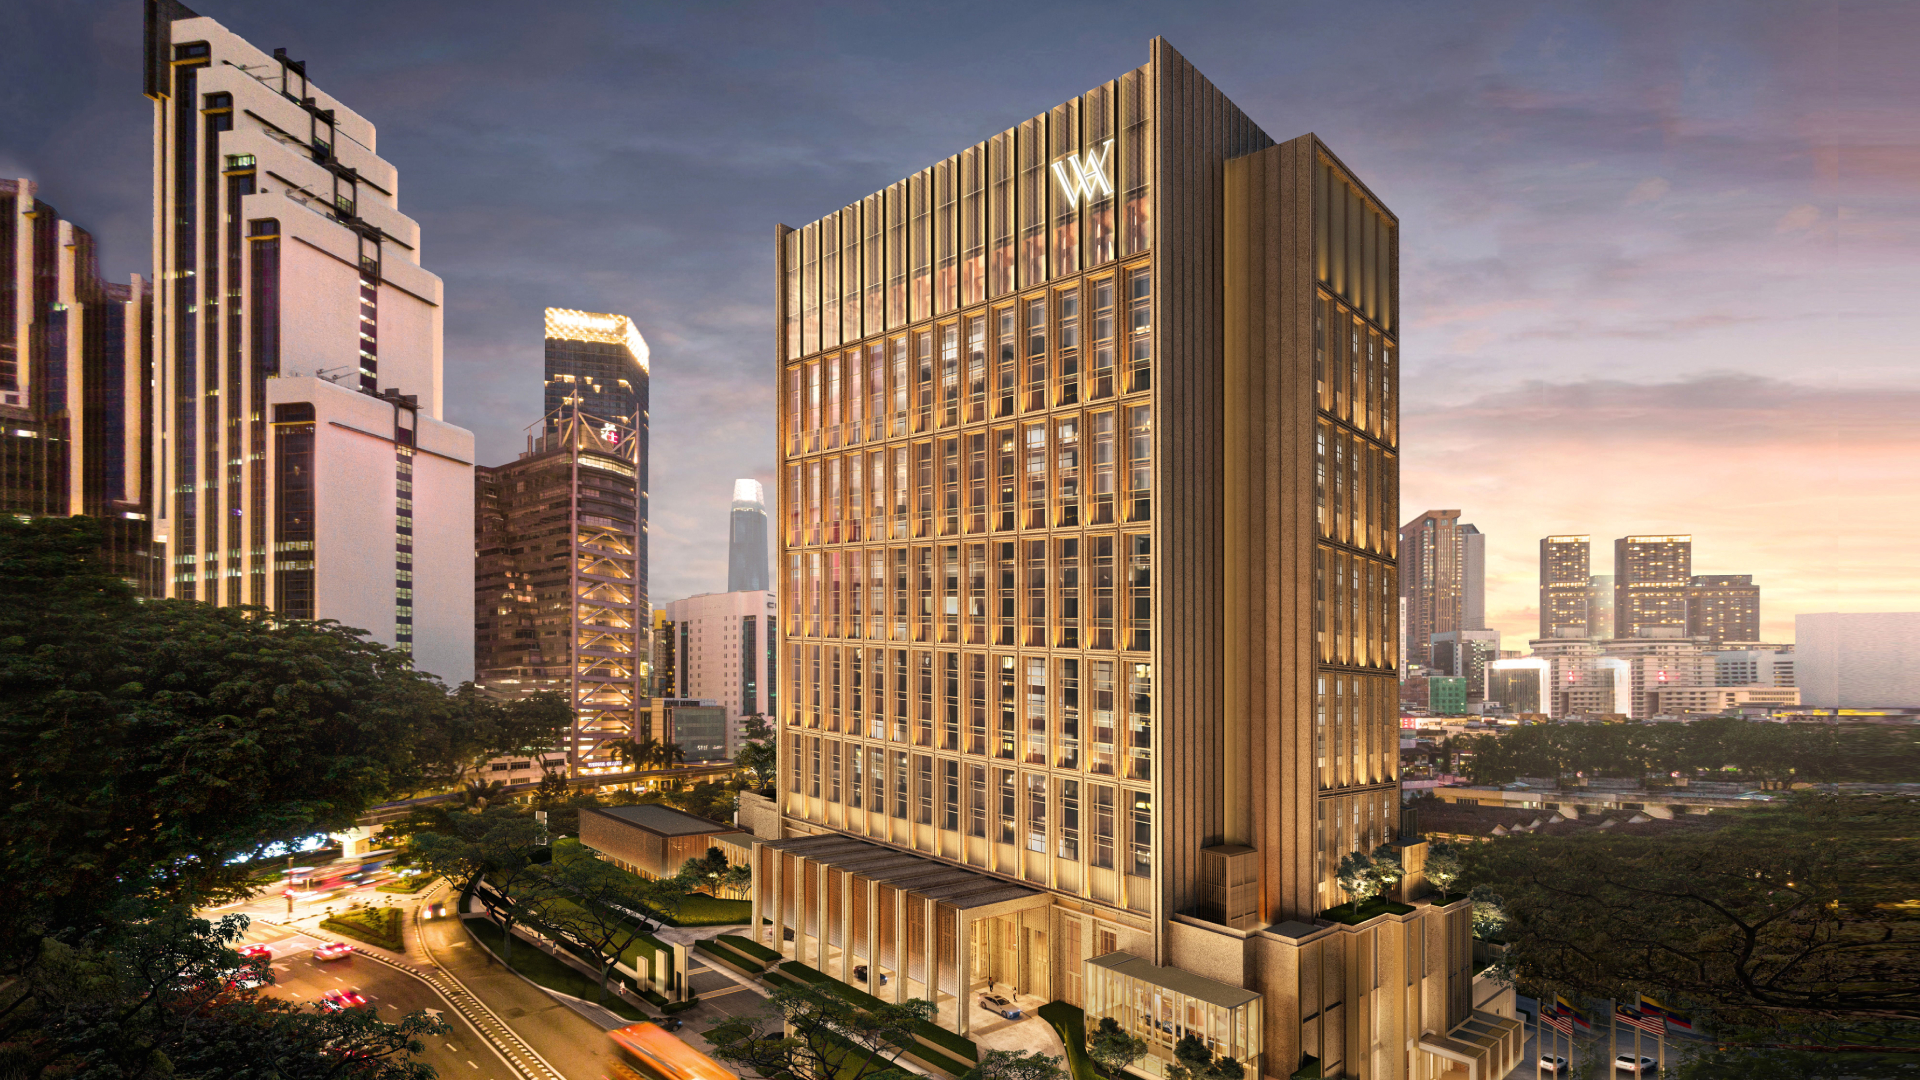
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.

Hand-built in Melbourne and limited to just 10 cars a year, the Zeigler/Bailey Z/B 4.4 is reshaping what a modern collector car can be.