Behind Many Powerful Women on Wall Street: A Doting ‘Househusband’
More men are staying home to facilitate the complex juggle of family life and their wives’ high-powered careers

 6 min
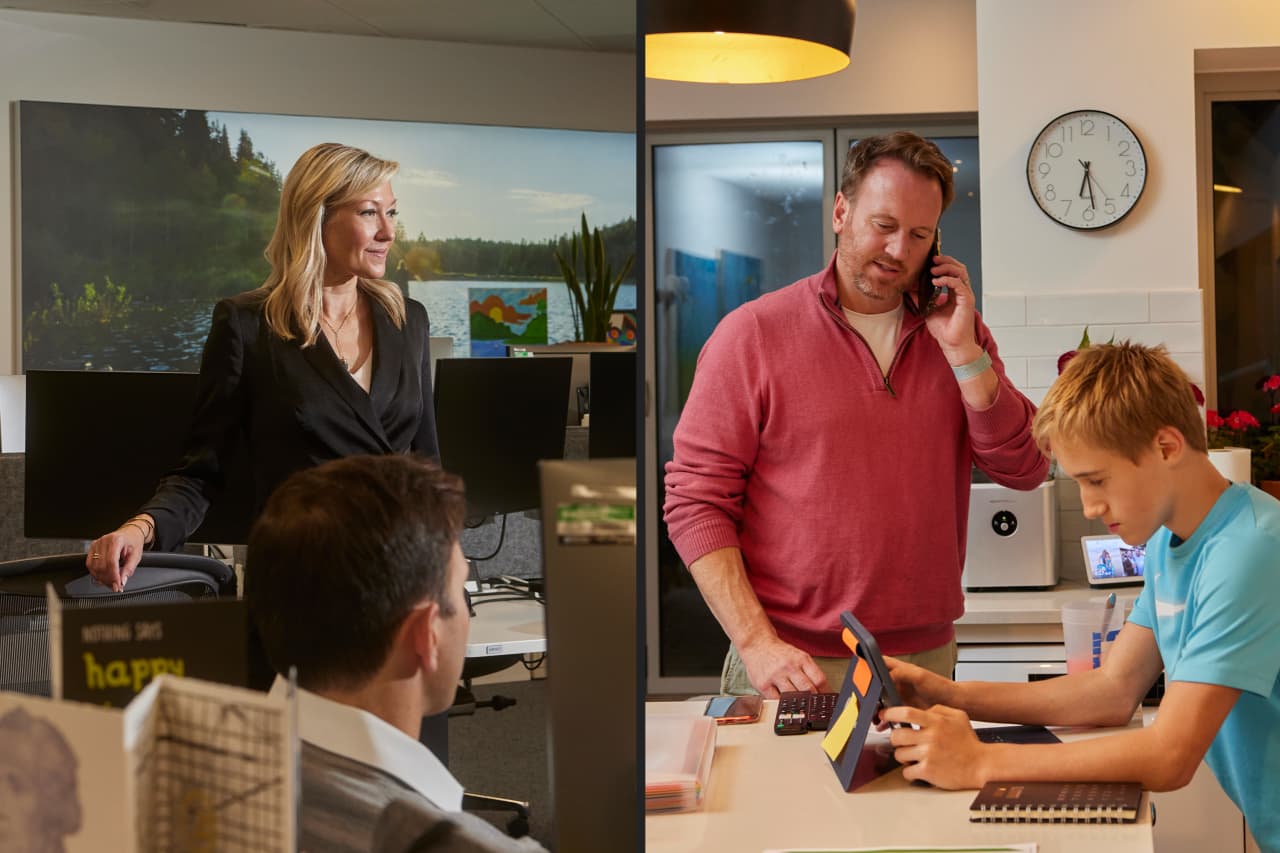
Suzanne Donohoe , a top executive at the private-equity firm EQT , started the month of September with a 10-day business trip through Asia and Europe. Back in New York, her husband, Matt Donohoe , was helping their three teenagers begin a new school year.
That was no simple task. Though the Donohoe children are close in age, each goes to a different school and has different extracurricular activities. Matt drove their 13-year-old to hockey practices in New Jersey and took all three children to Boston for a tournament. In between, there were groceries to buy, meals to prepare and homework to assist with.
It was all in a day’s work for Matt, who quit his job in 2007 to help out at home. A former emerging-markets trader with degrees from Georgetown and Columbia, he is part of a quiet but growing force of men who hold down the fort at home while their wives climb to the upper echelons of finance.
Wall Street has long struggled to elevate and retain women. A hotly competitive industry that demands long hours, frequent travel and the need to be on call constantly, it has been an unwelcoming environment for women, particularly those with children.
Women who have leadership roles in finance say that having a spouse who stays home—a househusband, if you will—can relieve that burden and allow them to rise. Even these privileged women, who have a spouse at home and often extra help beyond that, say maintaining the arrangements is a complex feat.
For the men, being a househusband can come with a stigma: Society often still assumes men will be the bigger earners and women the primary caregivers. But that is starting to change.
In 45% of U.S. opposite-sex marriages, the wife earns as much as or more than her husband, a share that has roughly tripled over the past 50 years, according to a 2023 report from Pew Research Center. Dads represented 18% of stay-at-home parents in 2021, up from 11% in 1989, another Pew study found.
There are now househusbands at the highest levels of power. Doug Emhoff , married to Democratic presidential nominee Kamala Harris, gave up his career—as an entertainment lawyer—to facilitate her political rise after she was elected vice president. On Wall Street, the list of women with husbands at home includes the chief executives of Citigroup and TIAA, the chief financial officer of the private-equity firm Vista Equity Partners, and the global co-head of Blackstone’s real-estate business, among others.
Senior female executives whose partners also work say they have to manage an intense balancing act and admit to being envious at times of their peers whose husbands don’t work.
“The prototype of the person you are competing with, the people in nearly all of the successful positions, have a stay-at-home partner,” says Suzanne Donohoe, who was a partner at Goldman Sachs and KKR before joining EQT in 2022. “The disheartening part of the message is somehow you can’t achieve if one parent isn’t at home.”
She says she doesn’t think that is the case and knows and admires people in demanding jobs who make it work with neither spouse at home.
‘Safety net for a trapeze artist’
Many couples say they started out with parallel professions but reached a point at which the woman’s career accelerated. When one person needed to devote more time to parenting, it made more sense for it to be the man.
Chip Kelly was working in tech sales at an international startup in 2009 when his wife, Natalie Hyche Kelly, who is a Visa executive, gave birth to their first child. After the couple didn’t move quickly enough to get a spot at the daycare they wanted, Chip volunteered to care for the baby and work while she slept.
He took calls while pushing their daughter in the stroller. When she went to sleep, he worked through dozens of emails. The couple had twins a few years later. Around that time, Natalie was promoted and started commuting to San Francisco four days a week from Charlotte, N.C., where the Kellys lived. Chip tried to work while caring for the twins and their older daughter when she wasn’t in preschool.
After the family moved to San Francisco, Chip realised that he was neither doing his job nor parenting as well as he wanted to. He decided to devote himself full time to the latter.
“It was kind of becoming a no-brainer because my wife’s career was going so well,” he says.
The Kellys are now starting their third year in London, where Natalie serves as the payments company’s chief risk officer for Europe. Chip considered going back to work a few years ago, but so far has decided against that because his family relies on his being at home.
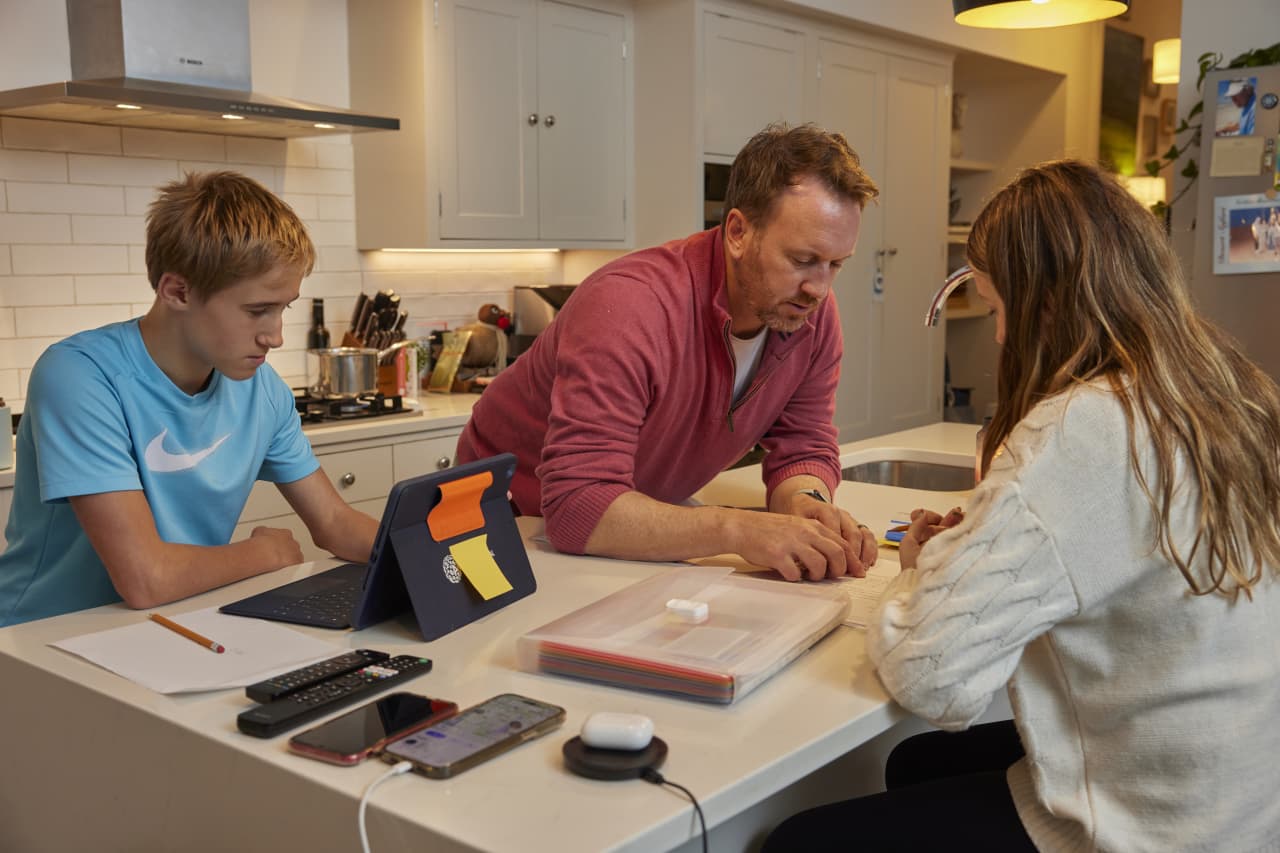
“I’m like the safety net for a trapeze artist,” he says. “You don’t think about it unless they take it away.”
Kathleen McCarthy Baldwin, Blackstone’s global co-head of real estate, was nursing her second child in 2015 when her husband, Matt Baldwin, left his job as the CFO of a research firm and decided to take some time off.
“The idea of him not working made me very anxious, mostly because of my fears about what it would do to our marriage,” she says. “Would I be envious that he had more time with the children? Would he resent that I had this really exciting and demanding job?”
Matt told her he wasn’t worried. After spending a summer with their daughters at the Jersey Shore while Kathleen mostly worked in the city, Matt decided to make the change permanent.
These days, he rises at 5:30 a.m., before the rest of the house is awake. He makes oatmeal for the family four mornings a week, giving himself one morning off. On most days, Kathleen takes the girls to school while Matt goes indoor rock climbing.
After school, he and their nanny divide the responsibilities, with one taking the older daughter to sports practice, drama and guitar lessons and the other transporting the younger one to swimming lessons, violin and dance. Matt, who has become a skilled cook, usually makes dinner. Specialties include salmon, soft-cooked eggs and spicy pasta.
Kathleen says her husband’s decision to stay home created the flexibility for her to pursue other interests outside work, such as serving on the board of an anti-hunger nonprofit.
“When I talk with other women in this position, we all say our husbands are a very special breed,” she says. “They don’t define themselves by their jobs.”
Awkward moments
Not all men are as comfortable in the position.
One stay-at-home dad whose wife works in private wealth at an investment bank says he sometimes tells other men that he manages real estate—technically true because the family owns a few buildings. He says he can identify other men in his position at private-school functions when they say they “manage investments” or “run a boutique hedge fund.”
“We’re all out there, but we can’t say anything about it,” he says.
Paul Sullivan has been trying to change that. He founded a group called the Company of Dads after leaving his job as a columnist for the New York Times in 2021. Sullivan’s wife runs an asset-management firm and became very busy with work after the Covid-19 pandemic.
Sullivan already defined himself as what he dubs a “lead dad,” the go-to parent for everything from playdates and doctors’ appointments. But he found no support groups for men in his position. He reached out to senior female executives and asked them about the idea of creating one. They approved. Some said their husbands didn’t help enough. Others said their husband’s friends made fun of them, calling them names like “Mr. Mom.”
“Two things can be true at once,” Sullivan says. “Moms can be discriminated against in the workplace, and dads can be afraid to take a lead role at home.”
Sullivan now organises events for lead dads such as a Father’s Day beer fest and a March Madness get-together. He gives talks at workplaces and hosts a podcast on which he interviews therapists, parenting coaches and fatherhood advocates. He counts the husbands of Goldman Sachs partners, JPMorgan Chase managing directors and top law partners among his members.
For the Donohoes, having Matt at home has meant that he has developed a close bond with his children. Suzanne says it has given her credibility with her colleagues when she needs to attend one of their doctor’s appointments or sporting events.
There are still mix-ups. Schools often call Suzanne first if one of the children is sick or needs permission to do something even though Matt is listed first on contact forms. Once it happened when she was in London on business. She gently asked the school administrator to call her husband. He was at their apartment five minutes away.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From Tokyo backstreets to quiet coastal towns and off-grid cabins, top executives reveal where they holiday and why stepping away makes the grind worthwhile.
Located steps from Crows Nest Metro, the near-complete development brings luxury living to Sydney’s Lower North Shore.