Alcoa Agrees to Acquire Australia’s Alumina for $3.35 Billion
Alumina said it recommends shareholders vote in favour of the offer, which comes after a number of previous bids by Alcoa were rejected.

 < 1 min
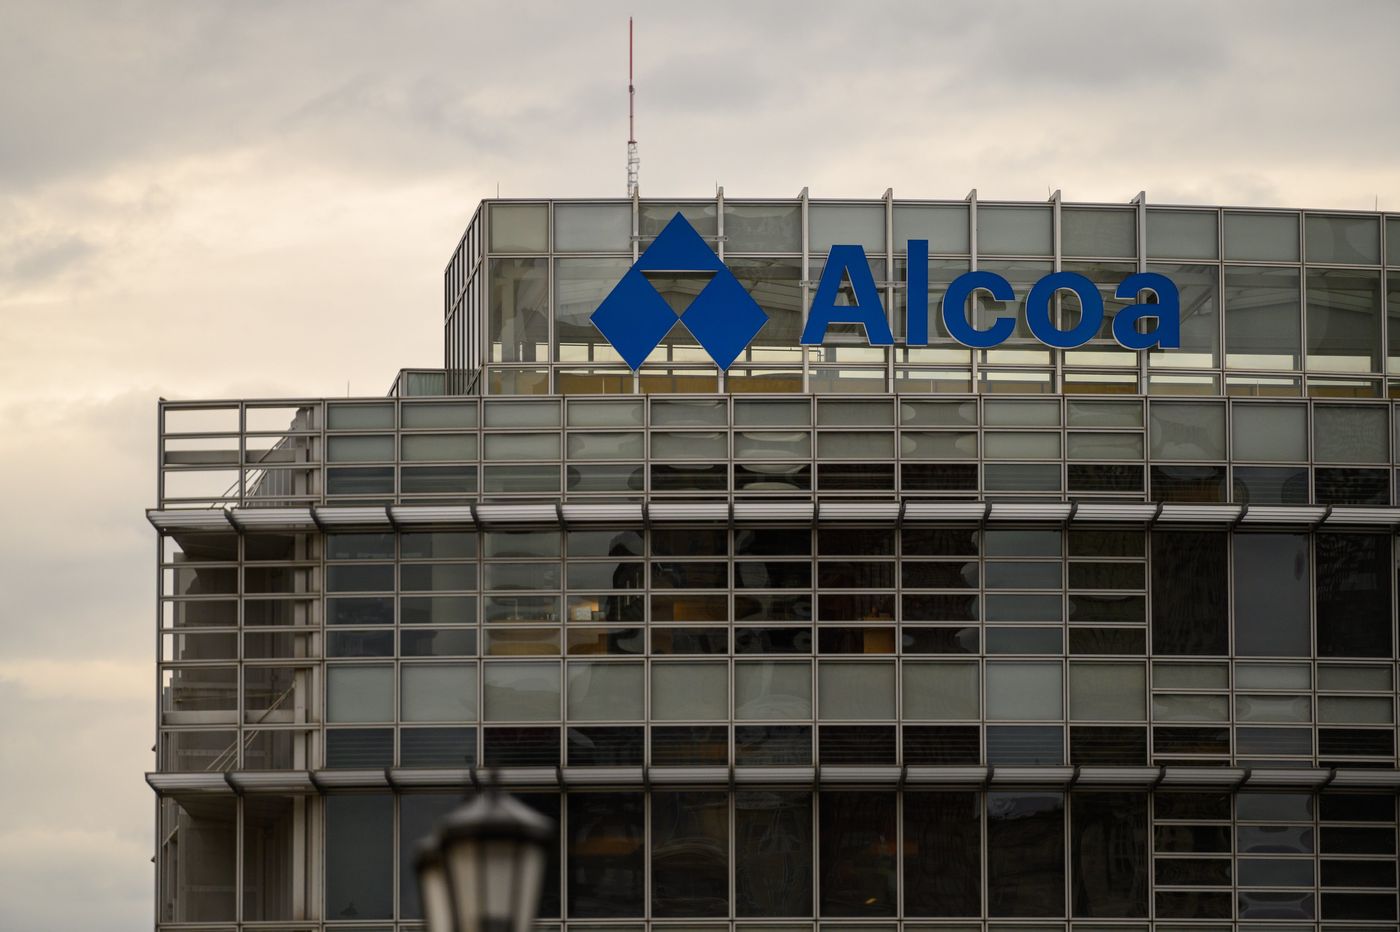
SYDNEY—Aluminium producer Alcoa has agreed to an all-stock deal to acquire Australia’s Alumina that values its equity at some 3.35 billion dollars.
Pittsburgh-based Alcoa is offering 0.02854 of its own stock for each Alumina share, representing a 13% premium to Alumina’s closing share price on Friday. Alumina said it recommends shareholders vote in favour of the offer, which comes after a number of previous bids by Alcoa were rejected.
Alcoa said it has reached an agreement with fund manager Allan Gray Australia that gives it the right to buy up to 19.9% of Alumina.
Alumina owns a 40% stake in Alcoa World Alumina & Chemicals, or AWAC, a joint venture with Alcoa that runs bauxite mining, alumina refining and aluminium smelting operations.
“Alcoa has been a proven operator of AWAC, and we recognise the value creation opportunities possible under a simplified ownership structure,” said William F. Oplinger , Alcoa’s president and chief executive.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices
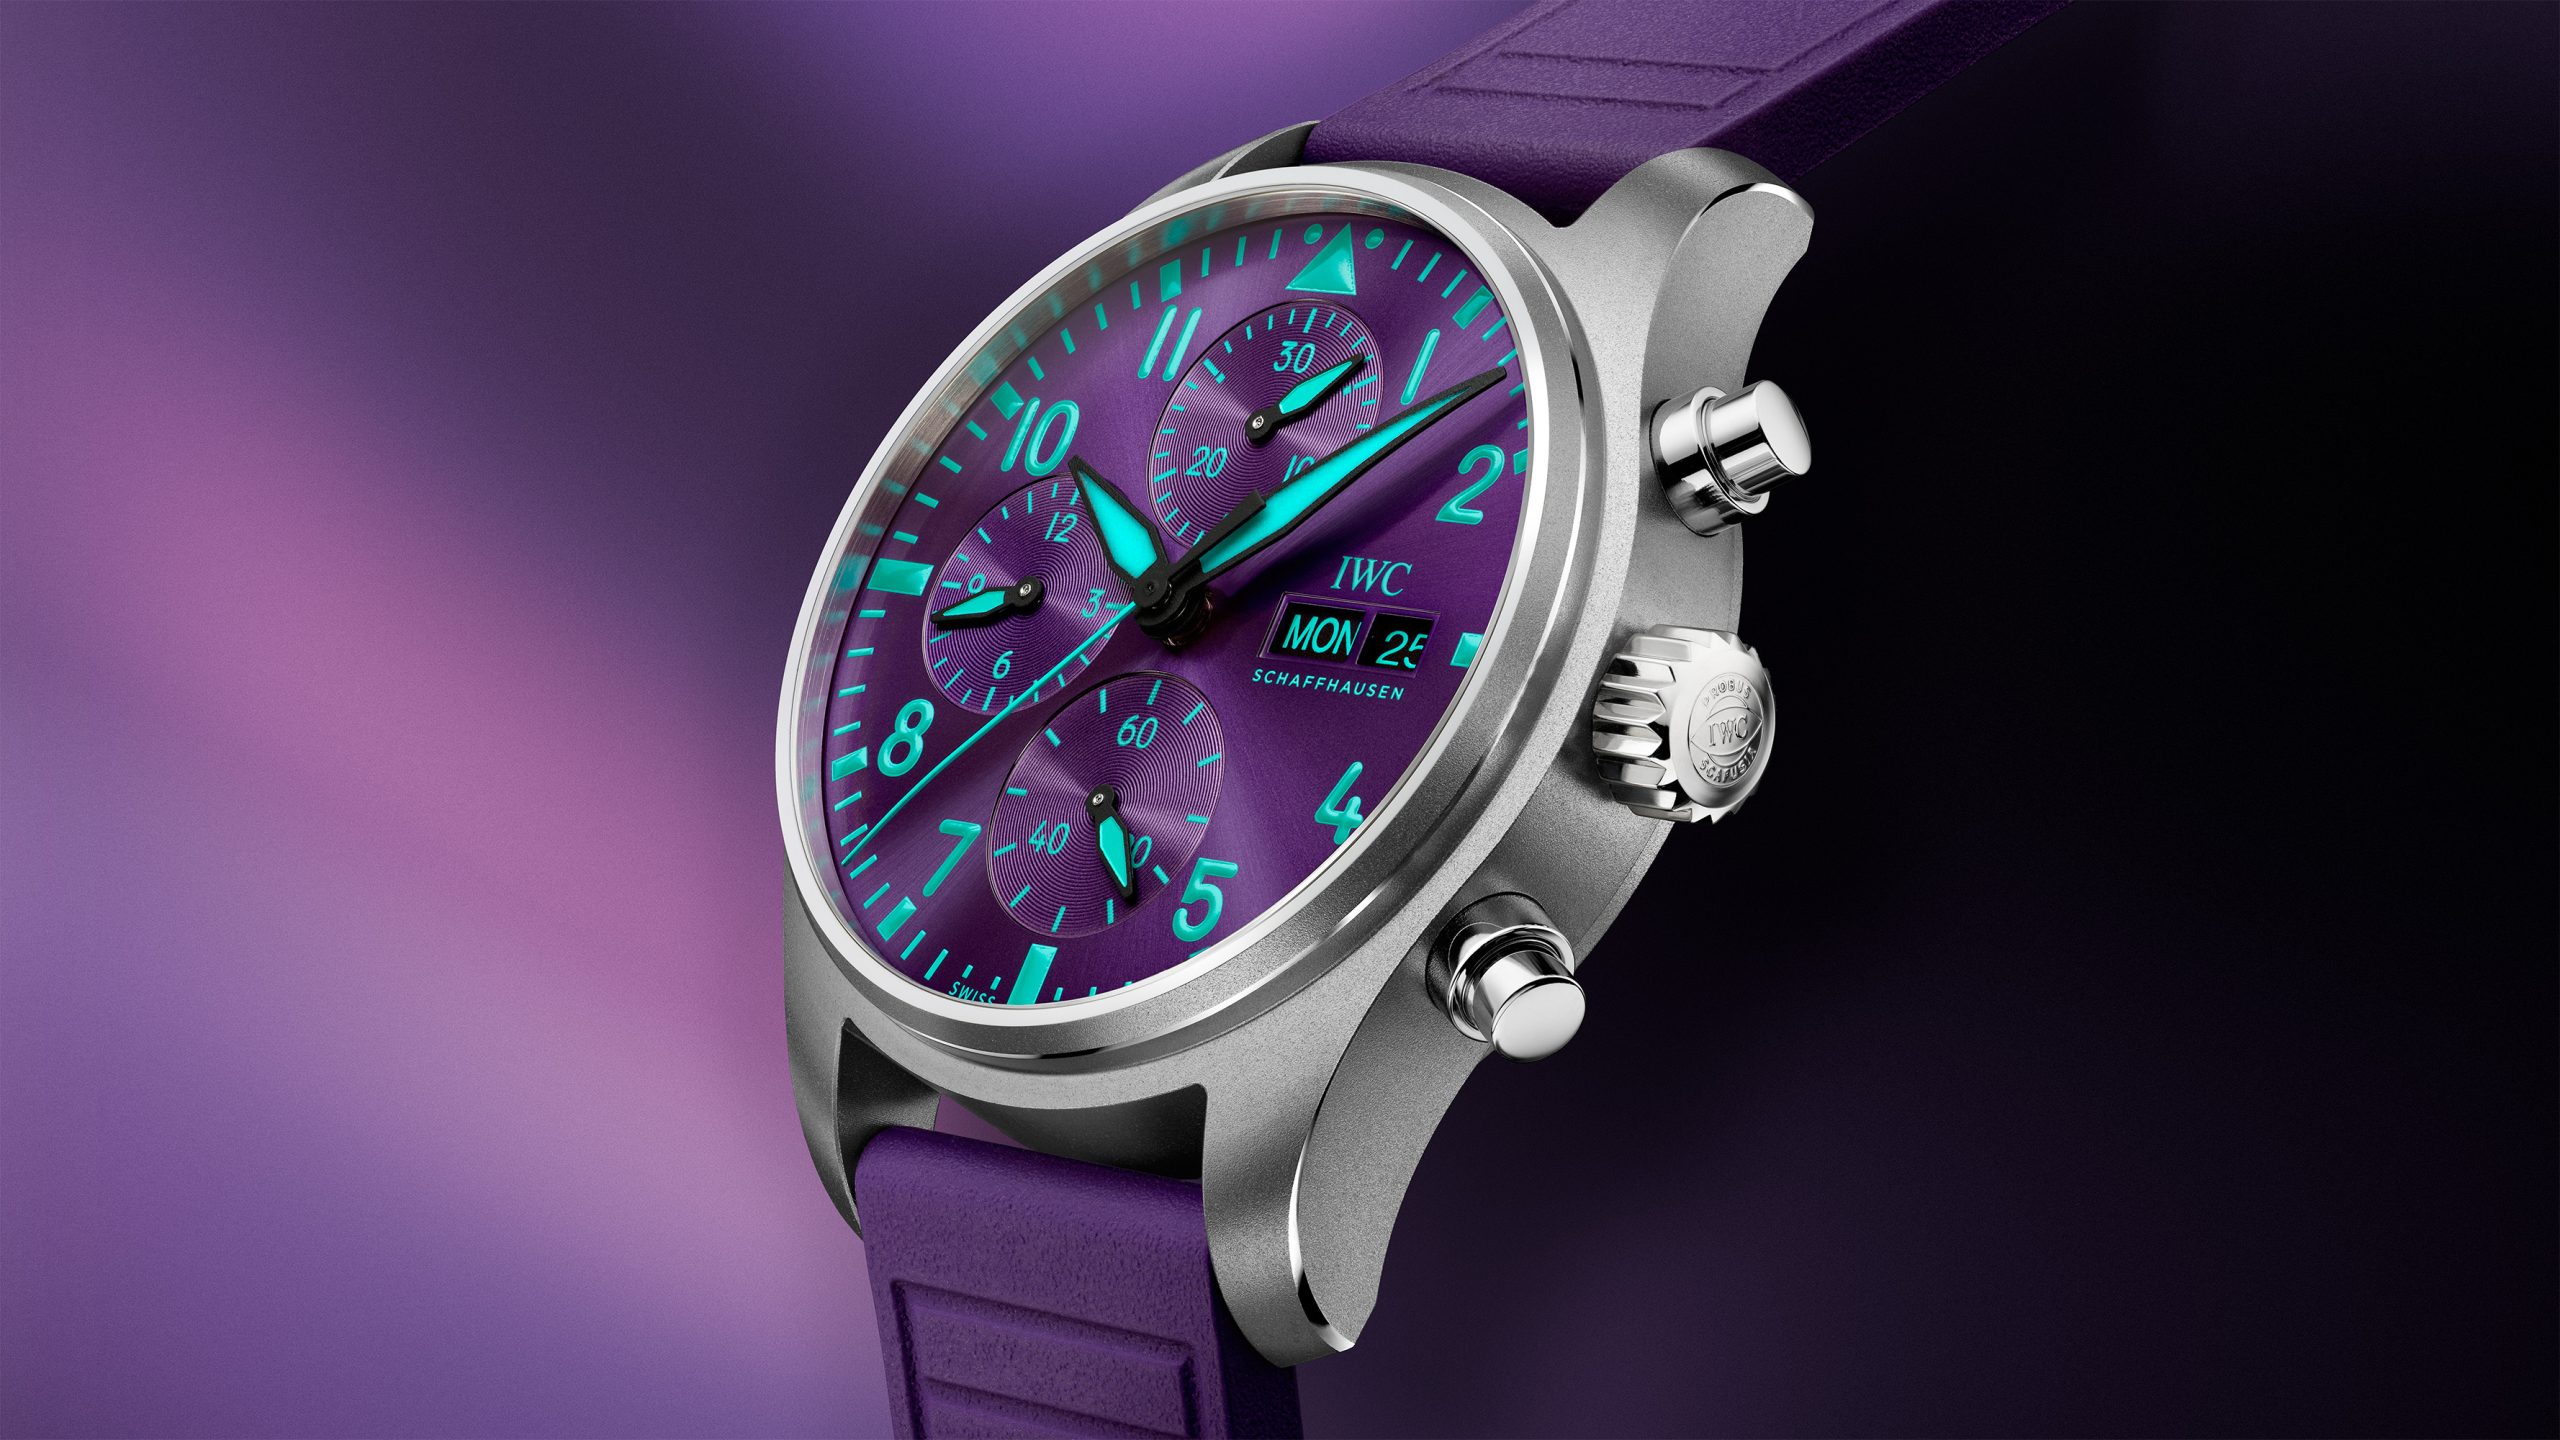
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”
Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.
3 min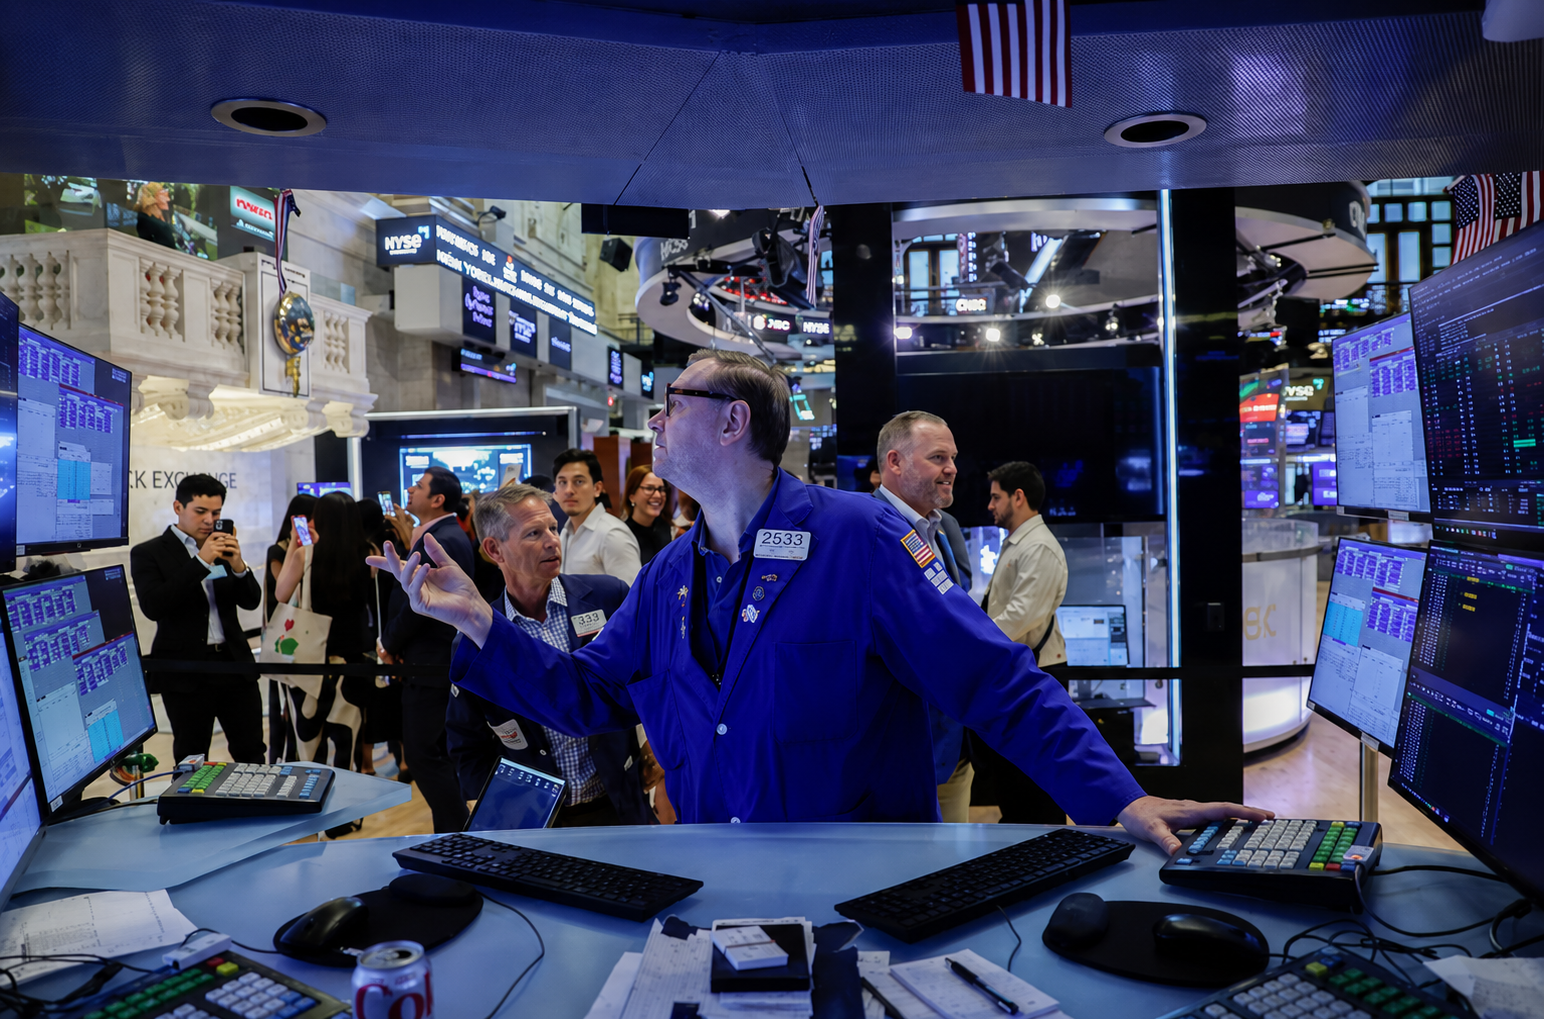
Wall Street’s hottest trade has gone ice cold.
For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron Technology, Nvidia, Advanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.
The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.
Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.
“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.
Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.
Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.
Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.
“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.
Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.
“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”
Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.
Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”
The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.
The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.
These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.
Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.
The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.
Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.
Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.
And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.
“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”

French luxury-goods giant’s results are a sign that shoppers weren’t splurging on its collections of high-end garments in the run-up to the holiday season.
Australia’s market is on the move again, and not always where you’d expect. We’ve found the surprise suburbs where prices are climbing fastest.