Alcohol consumption is dropping in Australia but there’s one market that’s booming nationwide
As Australians develop a taste for craft distilleries — and their products — the local industry is meeting the growing demand with exceptionally good drops
 6 min

From the Winter issue of Kanebridge Quarterly magazine, on sale now.
It never used to be this complicated to order a drink. Less than 10 years ago, requesting a whisky, a gin and tonic or even a vodka martini was a fairly straightforward affair with a choice of international brands, from Glenfiddich single malt whisky to Absolut vodka and Bombay Sapphire gin.
Now, the drinking landscape is somewhat more complicated — and that’s good news for locals who like a dram of whisky or a cocktail or two.
The Australian distillery industry has gone through rapid growth in recent years, from 30 distilleries nationally less than 10 years ago to more than 600 now. And that’s despite the overall levels of alcohol consumption falling over time across Australia.
CEO of the Australian Distillers Association, Paul McLeay, has a simple explanation.
“Australians are drinking less, but better — and patterns are changing,” he says. “Cask wine sales are down. They’re drinking less boring beer and more interesting products.”
While the distillery industry was already growing, McLeay points to COVID as the impetus for the increasing appetite for flavourful spirits.
“Tastes changed after COVID,” he says. “That home cocktail culture took off as people realised they could make interesting drinks at home — and post photos of them on Instagram.
“That notion of drinking less but better, the idea of fewer drinks on fewer occasions made it feel more special.”
While the Australian wine industry was valued at $5.7b last year, the distillery market is making headway, coming in at $2.5b. However, McLeay says it differs from the wine market, especially in terms of production profiles. For starters, without the need for vineyards, he says the distilleries are equally split between city and regional areas. This is a key advantage for small craft distilleries looking to connect with their local market.
“If you live in Marrickville (in Sydney), you’ll be proud to be drinking a local gin,” he says. “When someone comes to visit, you want to give them something to take home. Spirits allow you to give them a taste of the locality — you can buy it in a bottle.
“For travellers, if people remember the Hellfire Bluff Gin they had on a night out in Hobart, that’s a positive association with the area as well.”
At the moment, he says there are about 500 gin and vodka distilleries around the country, about 100 whisky producers and 50 making rum. With each product having its own flavour profile influenced by local conditions, from the region’s botanicals to its barley, the quality of its rainwater and even the way it is aged, it is good news for consumers seeking variety. McLeay says most distilleries are making multiple spirits to increase commercial opportunity and get product to market quickly.
“The ‘brown’ spirits have had more time,” he says. “Whisky looks clear like gin and vodka initially but over three or four years of maturation, it turns brown. It only takes about a month to make gin, which is why a bottle of gin is generally less expensive than whisky.”
While it might seem as though the homegrown whisky, gin and vodka market has appeared out of nowhere, credit for the modern distillery industry in Australia largely falls to Bill and Lyn Lark from Tasmania who lobbied their local MP in 1990 to change antiquated federal laws that outlawed distilleries that were smaller than 2,700L.
Following the change, LARK Distillery opened in Tasmania in 1992, capitalising on the state’s reputation for growing high quality barley, its clean water, as well as providing the perfect climate for ageing single malt whisky. Support for the Larks’ efforts also followed from government, as well as mentorship from John Grant from Scottish label Glenfarclas, with their first whisky sent to market in 1998.
Bill Lark says while he knew it was a delicious drop, it wasn’t until the early 2000s that the business kicked up a gear.
“The early 2000s was a period where we and the few other distilleries had to prove their credibility to the market,” he says. “When LARK first won a major award in the World Whisky Awards in 2009 I think it gave the confidence in others to get involved. From day one, inspired by such greats as John Grant from Scotland, I encouraged as many new distillers as possible to become a family of distillers where hopefully we would all be producing a world class product in sufficient numbers for eventually Tasmania and Australia to be recognised as a significant whisky producing region.”
In March this year, LARK was recognised by the World Whiskies Awards in London for crafting Australia’s Best Single Malt and Best Blended Malt.

In the intervening years, Australian distillers far and wide have heeded the Larks’ call to create their own spirits, from small family operations focusing on a single product to larger businesses with their eyes firmly set on the world stage.
Fellow Tasmanians Suzy and Cam Brett from Spring Bay Distillery share a passion for whisky and were inspired by their travels and the Larks’ example to start their own business.
“We remember very clearly being told by Bill Lark to make sure you make bloody good whisky!” says Cam. “I think there has definitely been a change in consumer habits.
“People are more engaged with what they are drinking, how it is made, where it comes from and that has increased the popularity of all spirits.”
Suzy says she first experienced whisky while working in Edinburgh in the 1980s. She’s been a fan ever since.
“Whisky is the king of drinks because of the complexity, the ageing and the romance,” says Suzy. “The time it takes the whisky to mature is influenced by barrel size, bond store, location and climate. The larger the barrel, the longer the maturation.
“Some of our large barrels may take 10 years or more to mature and it is a case of ‘it’s ready when it’s ready’ and won’t be rushed.”

Jake and Tess Eagleton started their Wagga Wagga label, Riverina Gin, in February 2023, after years of discussions, as well as travelling around gin distilleries in the Scottish Highlands, where Jake grew up.
“There are lots of gin distilleries popping up in the Scottish Highlands — I was surprised to see so many,” Jake says. “We started visiting them and often they were on people’s farms and you’d get the chance to meet the maker.”
The couple, who now have three children, were inspired by the notion of a family-run business and, with the help of local winery, Borambola Wines, who offered them a shed, focused on a one-shot distillation method. They have a simple philosophy of making one product really well.
“We try to stand out by not standing out too much — we use fresh organic oranges from the local region so the flavour is citrus forward,” says Jake.
They have also called on connections in their local community, partnering with Paper Pear Gallery in Wagga Wagga to host the Riverina Gin Club events. Expansion will be slow but steady.
“We made sure people knew we were a family-forward business,” says Jake. “We have seen a lot of peaks and troughs with the economy and we have been adaptable because we do a lot of the work ourselves. We have one gin that has been well received.”
Brand director and co-founder of Never Never Distilling Co Sean Baxter has bigger ideas for the business he started with friends George and Tim, with plans to further its expansion into Asia and Europe. Unlike other distilleries that sell via bottle shops as well as online, Never Never is focusing on the hospitality industry to reach bars and hotels. It’s not a surprising strategy given Sean’s former life at Diageo, the peak company for brands such as Johnnie Walker, Tanqueray, Guinness and more.
“I worked as a contractor for Sweet&Chilli as a national brand ambassador for Johnny Walker,” Sean says.
“That gave me access to so many amazing venues and bars and I met a lot of people. I was standing in front of so many people telling incredible brand stories and it sunk in — I wanted to do my own.”
The Adelaide-based business now offers more than a dozen gins and sees the relationships with bartenders and hospitality providers as key to their success.

“We collaborate with international bartenders to promote the brand in Hong Kong and Singapore, and over the past 12 months we have moved into France,” he says. “That’s been a real eye opener, taking our oyster shell gin to the French — it’s an exciting push.”
The ultimate goal is to create a global brand.
“We didn’t build Never Never Distilling to be small.”

From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
International AI strategist Justin Kabbani will headline the Kanebridge Property Summit in Sydney on June 18, with tickets selling fast.
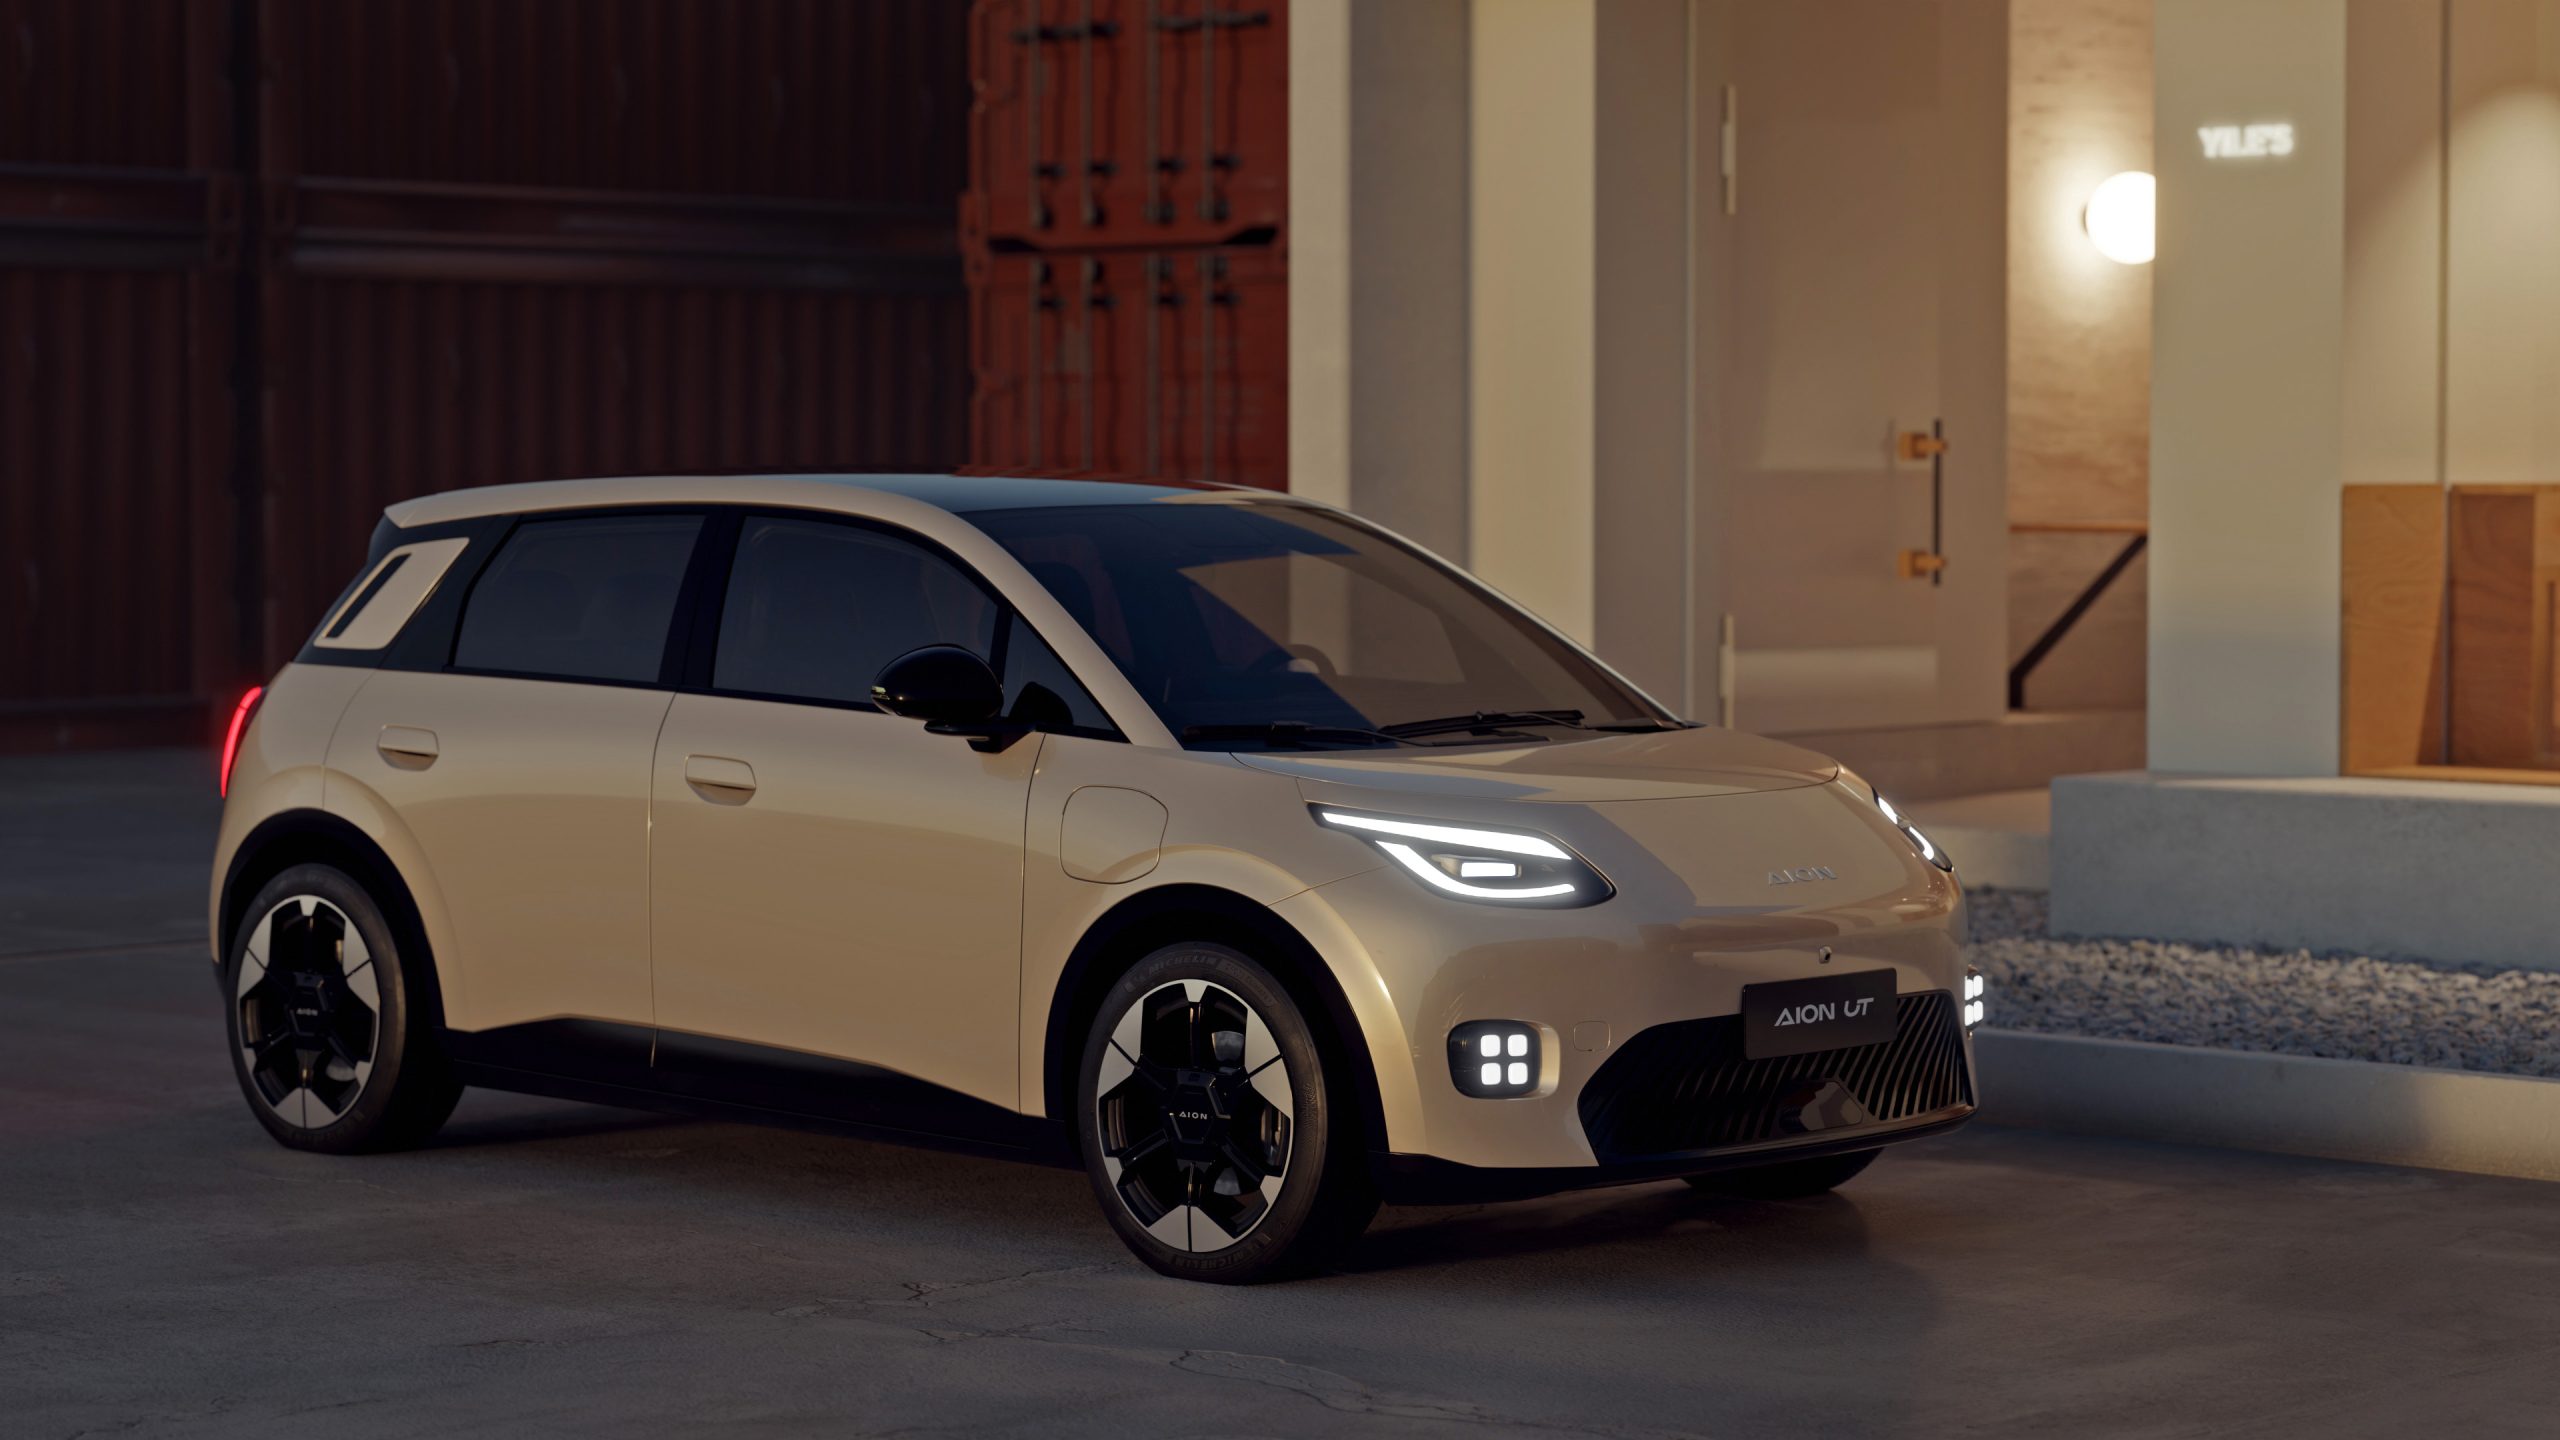
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.