America’s Billionaires Love Japanese Stocks. Why Don’t the Japanese?
Japan’s government wants cash-hoarding households to invest more

 3 min

TOKYO—Japan’s government is on a mission to make buying stocks hot again.
Many of America’s biggest investors are bullish on Japan. Warren Buffett shared that he increased his investments in Japanese companies during an April visit to the country. Ken Griffin is preparing to reopen an office in Tokyo for his hedge fund, Citadel, and investment banks Goldman Sachs and Morgan Stanley have issued optimistic outlooks for Japan’s stock market.
Japan’s problem is this: There are few signs its estimated 125 million residents share in the excitement.
Burned by dismal returns since the bursting of Japan’s asset bubble in the late 1980s and early 1990s, generations of families here have stashed most of their money in low-yielding savings accounts rather than trying to increase their wealth through the stock market.
Japanese households put an average of just 11% of their savings into stocks and 54% in cash and bank deposits, according to Bank of Japan data released last month. That trails well behind the U.S., where households have about 39% of their money tied up in the market and only 13% in cash and bank deposits, according to Federal Reserve data.
Haruyo Arai, a 62-year-old office worker, began investing in the stock market just last month.
“I was brought up by parents who would say, ‘Don’t dabble in stocks,’ ” she said.
Japanese Prime Minister Fumio Kishida has pledged to double households’ asset incomes, in part by encouraging people to invest in risky assets like stocks. The government is raising caps for Japan’s tax-exempt investment system for small investors, the Nippon Individual Savings Account, with changes set to take effect in January. The Tokyo Stock Exchange has been urging companies to boost their valuations and increase shareholder returns.
Arai cited the upcoming expansion to NISA, along with a desire to save more money for the future, as some of the reasons she decided to begin taking investing more seriously. She has been taking weekend classes at Tokyo-based Financial Academy to learn more about stocks and waking up early every morning to watch a TV news program focused on the economy.
Some believe investors like Arai will prove to be the exception, not the rule. Stocks here haven’t hit a record in decades. There isn’t much buzz among ordinary people about investing in Japanese markets.
“I’ve got the impression that Japanese people don’t really think positively about the desire to make money,” said Takashi Kawaguchi, a 48-year-old office worker who, like Arai, has been learning about investing at Financial Academy.
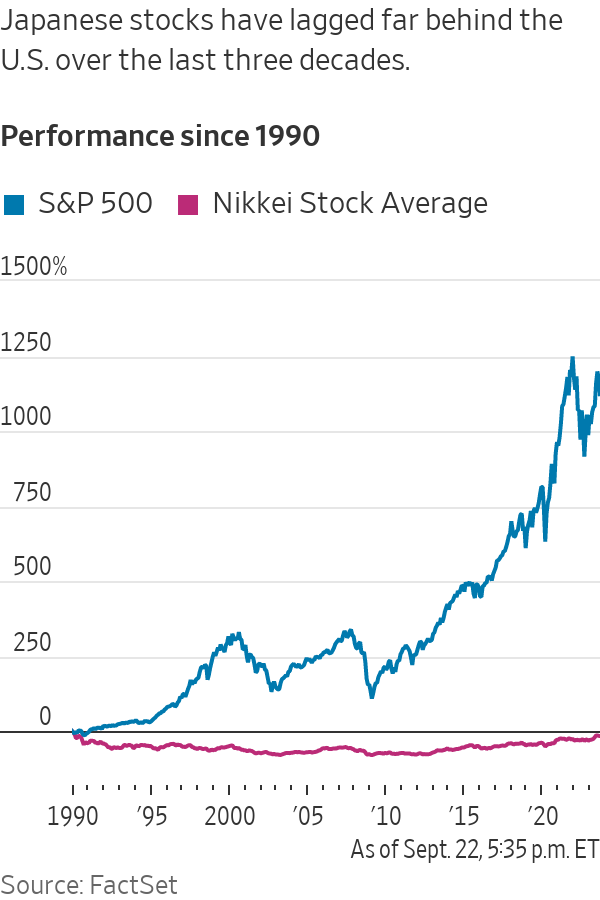
While the 2023 rally has helped lift Japanese stock indexes to 33-year highs, long-term returns pale in comparison to what an investor would have gotten by investing in U.S. stocks. The Nikkei closed at 32,402 on Friday, still 17% below its record hit in 1989. The S&P 500 has grown more than twelvefold over that time. That has made many investors here turn to foreign markets instead of focusing their bets within Japan.
“The Nikkei might hit 40,000, god knows when,” said Heihachiro “Hutch” Okamoto, foreign equity consultant at retail brokerage Monex. “But most of our investors prefer U.S. stocks.”
To Okamoto’s point, the most popular names traded on Monex daily aren’t Japanese stock indexes like the Topix or Nikkei, brand-name companies like Sony or even the “sogo shosha”—the trading houses that Buffett has invested in. Instead, they are all American names: companies like Nvidia, Tesla, Apple and Amazon.com, as well as funds tracking the S&P 500 and the Nasdaq-100.
And that is just among those interested in investing in the first place. While in past years, everyday investors in Japan made a name for themselves with their forays into the foreign exchange market, the overall trading culture here has been one of hesitation.
“Most people here think investing is very risky,” said Hidekazu Ishida, a special adviser at FinCity.Tokyo, which works with the government and the financial industry to try to boost investment in Tokyo. Being into finance comes off as “kakkowarui,” he added, referencing a word for uncool.
Even some heads of companies are lukewarm about the idea of encouraging more individual investors to buy Japanese stocks.
“I’m neutral about that,” said Takeshi Niinami, chief executive officer of whisky and beverage giant Suntory, when asked if he thought it would be a good idea for more Japanese people to invest in the market. Stock investing is risky, he said. And many Japanese people remain wary of participating in the market, because of the severity of prior downturns.
“I think perhaps increasing interest rates is better for people,” he said.
—Chieko Tsuneoka and Alastair Gale contributed to this article
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”
 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
As housing drives wealth and policy debate, the real risk is an economy hooked on growth without productivity to sustain it.
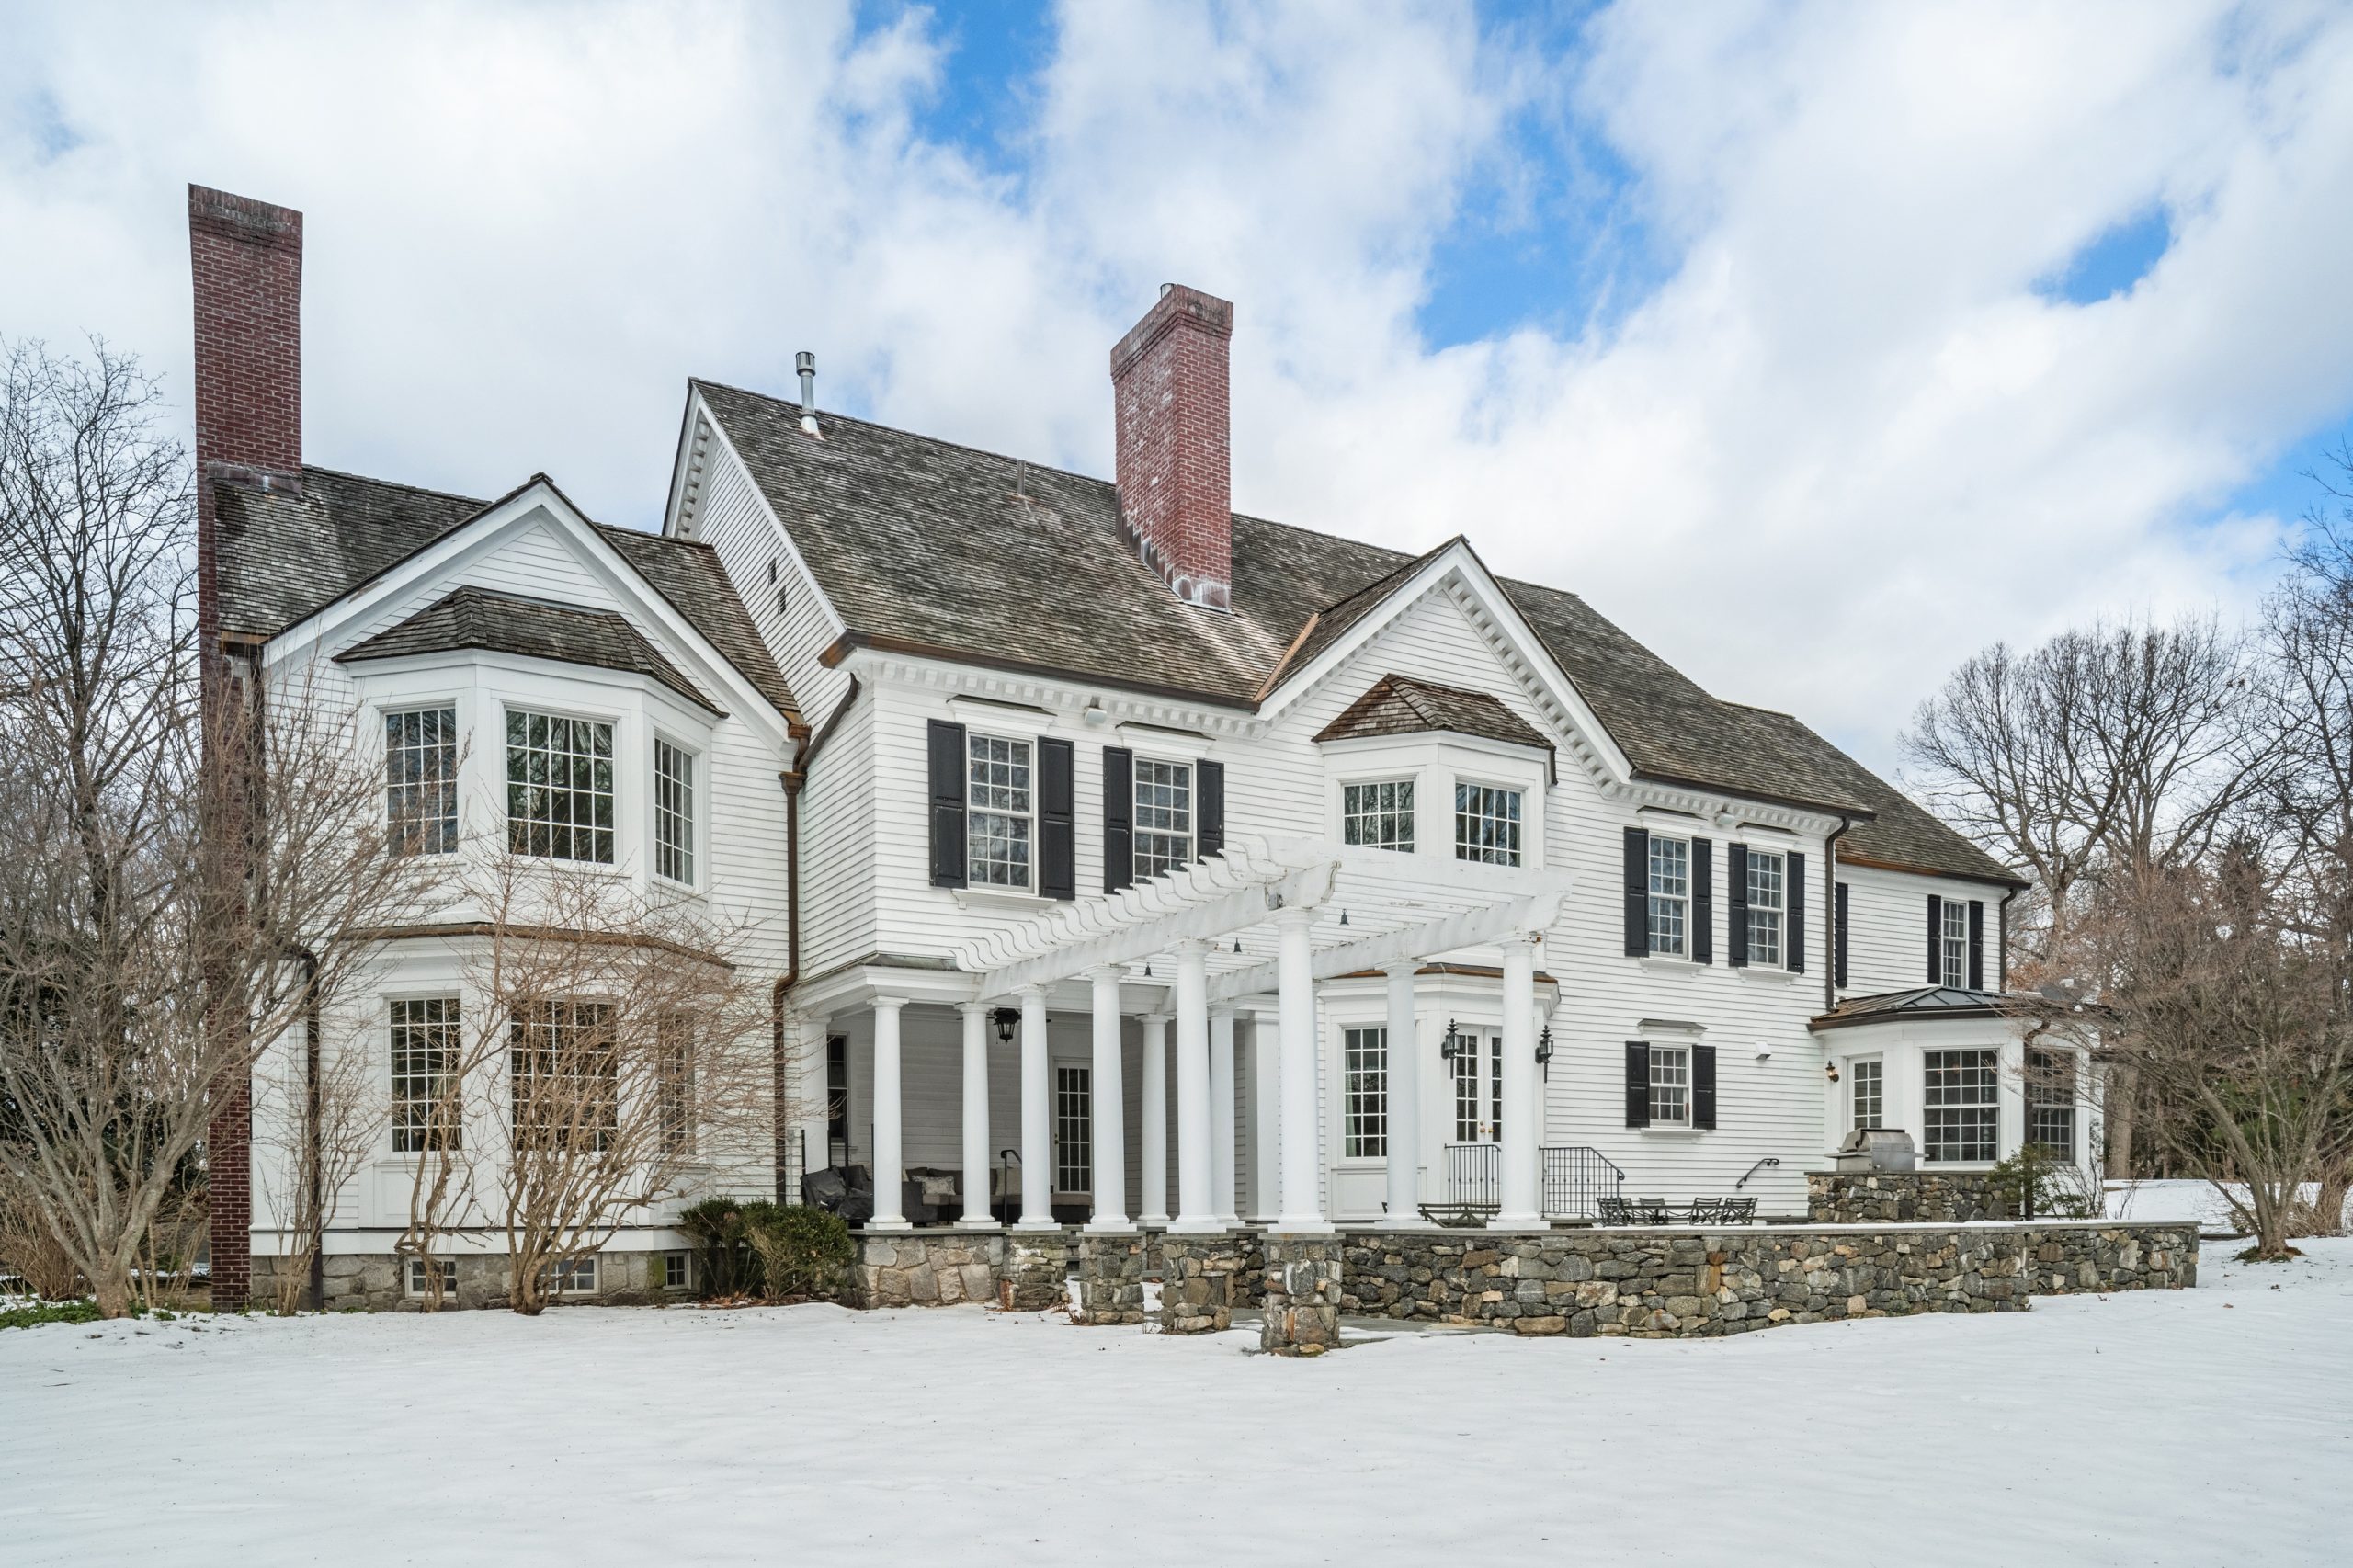
A haven for hedge-fund titans and Hollywood grandees, Greenwich is one of the world’s most expensive residential enclaves, where eye-watering prices meet unapologetic grandeur.