Apple Aims to Make a Quarter of the World’s iPhones in India
Supplier Foxconn plans to build more factories and give India a production role once limited mostly to China

 4 min
Apple and its suppliers aim to build more than 50 million iPhones in India annually within the next two to three years, with additional tens of millions of units planned after that, according to people involved.
If the plans are achieved, India would account for a quarter of global iPhone production and take further share toward the end of the decade. China will remain the largest iPhone producer.
Apple has gradually boosted its reliance on India in recent years despite challenges including rickety infrastructure and restrictive labor rules that often make doing business harder than in China. Among other issues, labor unions retain clout even in business-friendly states and are pushing back on an effort by companies to get permission for 12-hour work days, which Apple suppliers find helpful during crunch periods.
Apple and its suppliers, led by Taiwan-based Foxconn Technology Group, generally believe the initial push into India has gone well and are laying the groundwork for a bigger expansion, say people involved in the supply chain.
Apple is emblematic of a move among companies worried about over dependence on China to move parts of their supply chains elsewhere, most often to Southeast Asia and South Asia. Diplomatic efforts by the U.S. and its allies to block Beijing’s access to advanced technology and strengthen ties with New Delhi have accelerated the trend.
The first phase of a Foxconn plant under construction in the southern state of Karnataka is expected to start operating in April, and the plant aims to make 20 million mobile handsets annually, mainly iPhones, within the next two to three years, said people with direct knowledge of the construction plans.
A further iPhone-producing mega plant is on Foxconn’s drawing board with capacity similar to the one in Karnataka, although the plans are still in a nascent stage, the people said.
Apple has also chosen India as its site for a manufacturing stage for lower-end iPhones to be sold in 2025. In this stage, known as new product introduction, Apple’s teams work with contractors in translating product blueprints and prototypes into a detailed manufacturing plan. Until now, that work was done only in China.
Combined with plans for expanded production at an existing Foxconn plant near Chennai and at another existing plant recently bought by Indian conglomerate Tata, these developments signify that Apple intends to have the capacity to make at least 50 million to 60 million iPhones in India annually within two to three years, said people involved in the planning.
Annual capacity could grow by tens of millions of units after that.
Foxconn indicated its commitment to India by announcing on Nov. 27 that it was investing the equivalent of more than $1.5 billion in the country, money that people familiar with the matter said would include production for Apple. The announcement didn’t mention the iPhone or name specific locations.
Global iPhone shipments last year totalled more than 220 million, according to research firm Counterpoint, a number that has remained steady in recent years. Because almost all iPhones are made in either China or India, China will continue to account for well over half of iPhone output.
Apple has faced challenges in China this year beyond trade tensions with the U.S., including the Chinese government instructing some officials not to use iPhones at work.
“India’s trust factor is very high,” said Ashwini Vaishnaw, India’s information technology minister.
This year, for the first time, India-made iPhones were introduced on the first day of global sales of the latest model, eliminating the lag with China-made phones.
Supply-chain executives say hourly wages are now significantly lower in India than in China, but other costs such as transport remain higher, and labor unions sometimes resist rule changes sought by manufacturers.
In May, the chief minister of Tamil Nadu state, where Foxconn’s flagship Chennai plant is located, said he would withdraw regulations allowing a 12-hour workday, weeks after the state passed an amendment authorising the longer hours. The chief minister, M.K. Stalin, attributed the decision to opposition from labor activists.
Karnataka state has stood by a decision earlier this year to extend the workday to 12 hours, up from a previous limit of nine hours, though companies must seek approval to do so. A state labor official, G. Manjunath, said new rules also allow companies to employ women on overnight shifts without seeking government approval.
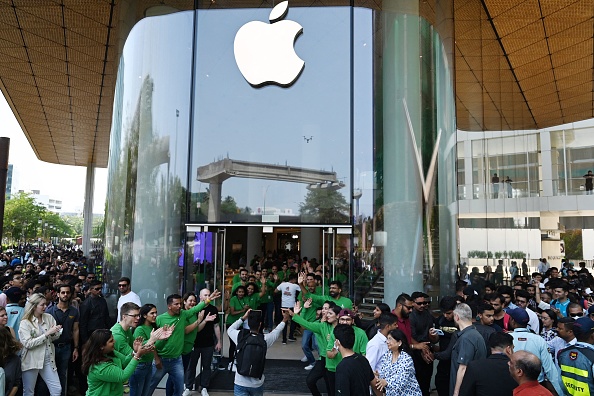
After years of battling local-content rules and other red tape, Apple this year opened its first retail stores in India. Abhilash Kumar, an India-based analyst at TechInsights, said the top-of-the-line iPhone 15 Pro Max was selling well in the country, though it costs about $700 more than in the U.S.
Apple is also making progress in India toward building a network of core suppliers, long a strength of Chinese manufacturing. Officials said this week that Japanese battery maker TDK would build a new factory in India’s Haryana state to manufacture battery cells to power Indian-made iPhones. A TDK spokesman declined to comment.
The moves don’t mean Apple and its suppliers are leaving China. Apple Chief Executive Tim Cook has traveled to China twice this year, stressing the country’s importance as a production hub and consumer market. He visited Luxshare, a China-based assembler that is taking a bigger role in the China portion of iPhone assembly.
On social media, Apple has assured Chinese consumers that iPhones selling in authorised channels are made in China. At an industry event in Beijing that Chinese premier Li Qiang attended in late November, Apple’s booth stressed the company’s business with Chinese suppliers.
Foxconn Chairman Young Liu said in November that China would continue to account for the largest share of Foxconn’s capital investment next year.
Liu has visited India at least three times in the past year and a half, meeting Prime Minister Narendra Modi and other officials. People involved in the planning said Modi’s home state of Gujarat in the west was one possible site of a future Foxconn plant. Meanwhile, the company has other projects in the works in the southern half of the country for electronic components and a plant likely to focus on making AirPods for Apple.
The plant in Karnataka state is under construction on 300 acres of land near the airport in Bengaluru, a southern city that is considered India’s tech hub. Officials involved in the planning said Foxconn has secured approval to invest nearly $1 billion in the plant and is seeking the go-ahead to put in an additional $600 million or so.
Combined with other projects, Foxconn’s investments in the state are likely to reach around $2.7 billion, they said.
Some iPhones are also made at a plant near Bengaluru that India’s Tata Electronics agreed in October to buy from Taiwan’s Wistron. Tata Group is the first local company to take on manufacturing iPhones.
“Apple has created an additional spoke in its India strategy by roping in the country’s largest business group—Tata—to be a part of its manufacturing system in addition to Foxconn,” said India’s junior information-technology minister, Rajeev Chandrasekhar.
—Shan Li in New Delhi and Selina Cheng in Hong Kong contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Powerhouse real estate couple Avi Khan and Kaylea Sayer welcome their daughter while balancing record-breaking careers, proving success and family can grow side by side.
Odd Culture Group brings a new kind of after-dark energy to the CBD, where daiquiris, disco and design collide beneath the city streets.