China Finally Has a Rival as the World’s Factory Floor
Companies look to find a backup for manufacturing and India is making its case

 7 min
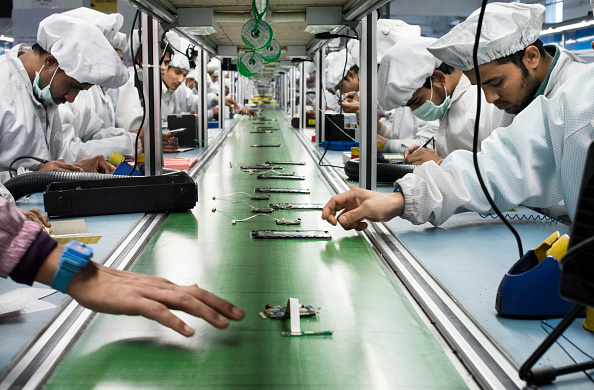
Western companies are desperately looking for a backup to China as the world’s factory floor, a strategy widely termed “China plus one.”
India is making a concerted push to be the plus one.
Only India has a labor force and an internal market comparable in size to China’s; India’s population may be the world’s largest, according to the United Nations. Western governments see democratic India as a natural partner, and the Indian government has pushed to make the business environment more friendly than in the past.
It scored a coup with the decision by Apple to significantly expand iPhone production in India, including expediting the manufacturing of its most advanced model.
Signs that India is changing are visible at the sprawling industrial parks in Sriperumbudur, a city in the southern state of Tamil Nadu. Foreign manufacturers here have long churned out cars and appliances for the Indian market. They’re now being joined by multinational corporations making goods from solar panels and wind turbines to toys and footwear, all looking for an alternative to China.
In 2021 Denmark’s Vestas, one of the world’s largest wind-turbine manufacturers, built two new factories in Sriperumbudur. Its six assembly lines now assemble hub cells, power trains and other components, stacked high in a storage yard to be shipped across the world.
Forecasts that India would soon become the second-largest market for turbines sparked Vestas’s expansion. But it was also a conscious effort to diversify away from China, which hosted the bulk of its regional production, especially after repeated lockdowns under Beijing’s zero-Covid policy, said Charles McCall, who oversaw the expansion as senior director of Vestas Assembly India. “We don’t want all our eggs in one basket in China.”
Some of Vestas’s suppliers have joined it. American contract manufacturer TPI Composites moulds 260-foot-long turbine blades that regularly draw attention as they are shuttled along surrounding highways. It has expanded significantly in India even as it reduces operations in China. Eventually, 85% of Vestas’s suppliers will be in India, said Mr. McCall, who recently left the company.
China still towers over every other country in global manufacturing, a position it cemented when multinationals flooded in after it joined the World Trade Organization in 2001. But a growing list of factors has prompted companies to search for a backup. First, there were rising labor costs in China and pressure from the Chinese government to transfer technology to Chinese competitors. Then there were President Donald Trump’s tariffs on Chinese imports in 2018, Covid lockdowns from 2020 through last year, and now a push by Western governments to decouple their economies from China.
Many countries are competing to be the “plus one,” with Vietnam, Mexico, Thailand and Malaysia in particular contention.
India must still overcome entrenched problems that have kept it a bit player in global supply chains. Its labor force remains mostly poor and unskilled, infrastructure is underdeveloped and the business climate, including regulations, can be burdensome. Manufacturing remains small relative to the size of India’s economy.
Nonetheless, after decades of disappointment, it is making progress. Its manufactured exports were barely a tenth of China’s in 2021, but they exceeded all other emerging markets except Mexico’s and Vietnam’s, according to World Bank data.
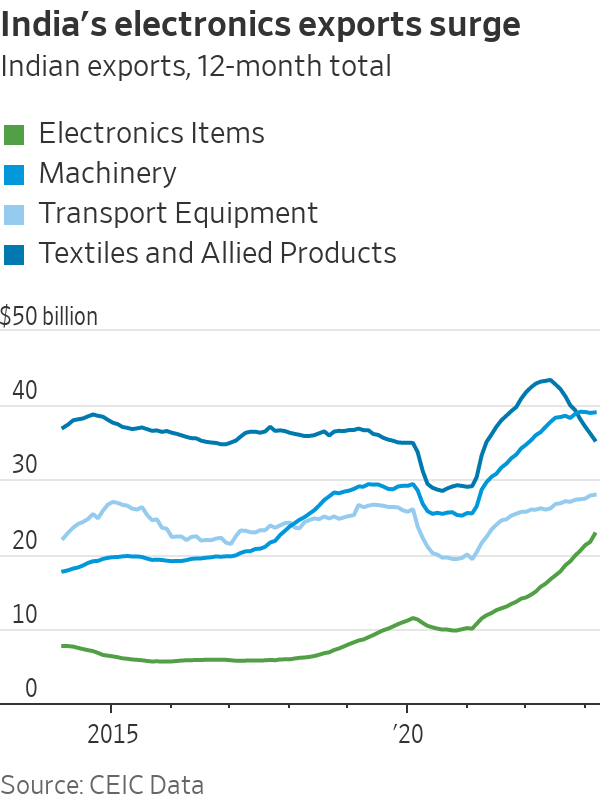
The biggest gains have been in electronics, where exports have tripled since 2018 to $23 billion in the year through March. India has gone from making 9% of the world’s smartphone handsets in 2016 to a projected 19% this year, according to Counterpoint Technology Market Research.
Foreign direct investment into India averaged $42 billion annually from 2020 to 2022, a doubling in under a decade, according to central-bank figures.
Since China declared a “no limits” friendship with Russia on the eve of the invasion of Ukraine last year, the U.S. and its allies have stepped up efforts to reduce dependence on China. Through “friendshoring,” the U.S. is “strengthening integration with our many trusted trading partners–including India,” Treasury Secretary Janet Yellen said on a visit there in February.
No company better embodies the bet on India as the next China than Apple. Over the past 15 years, the company built up a state-of-the-art supply chain almost entirely in China to make its laptops, iPhones and accessories. Its presence helped the entire manufacturing sector in China.
The California-based company has assembled lower-end iPhone models in India since 2017 and began making its newest, flagship iPhone 14 here within weeks of its launch last year. J.P. Morgan estimates a quarter of all Apple iPhones will be made in India by 2025.
Indian officials hope Apple’s presence will spur others to come. “Very often you have anchor companies who set the trend,” commerce and industry minister Piyush Goyal said in an interview. “We believe that this will send a strong signal…to other companies in Europe, America and Japan.”
Apple has been pushing suppliers to diversify beyond China after many faced production disruptions during Covid lockdowns. Meanwhile, geopolitical tensions have been growing between the U.S. and China, as well as between Beijing and Taiwan, where Foxconn Technology Group, Apple’s main manufacturer, is based.
Foxconn is set to expand production of iPhones at its existing plant near the Indian city of Chennai. It aims to boost iPhone production to around 20 million units annually by 2024 and roughly triple the number of workers to as many as 100,000, according to people familiar with the matter, The Wall Street Journal has reported.
An Apple spokesman declined to comment.
India has made progress overcoming some barriers to business. In 2014 Indian Prime Minister Narendra Modi unveiled “Make in India,” an effort to boost manufacturing. India has digitised many government services and accelerated construction of railroads, airports, container shipping ports, and electricity generation.
Mr. Goyal pointed to India’s rise on the World Bank’s ease of doing business rankings and the World Intellectual Property Organization’s global innovation index and a growing number of free trade pacts as evidence “we have now taken…integrating ourselves with other countries far more seriously.”
India introduced tax and customs rebates for exports in 2015 and overhauled them in 2021. The customs rebates were “the trigger point for the entire electronic industry,” said Sasikumar Gendham, managing director of Finland’s Salcomp, the world’s largest maker of smartphone chargers and supplier to Apple.
Since 2014, Salcomp’s Indian workforce has increased sixfold to 12,000 and it aims to hire 25,000 people in the next two years.
With 200 buses to transport workers and plans to build dormitories for 15,000 people, the company’s campus is massive by Indian standards, though not yet by Chinese standards. The facility churns out about 100 million units every year, compared with its China facility which produces about 180 million units.
For all this progress, it isn’t clear it’s enough to set India apart. Jules Shih, a Chennai-based director of Taiwan’s trade promotion agency, TAITRA, said India has become an easier place to do business, but in many respects still lags behind other countries.
It can take longer to get land and approvals to set up a factory in India and getting visas for expatriate technicians, managers and engineers is time consuming, Mr. Shih said. “We feel they don’t have a united goal integrated across agencies to make Make in India happen faster,” he said.
In March 2020, India introduced “production-linked incentives” that directly subsidise targeted products, starting with mobile phones and components, pharmaceuticals and medical devices.
Some companies have found the process to claim the production-linked incentives to be burdensome. South Korean technology giant Samsung Electronics has been in discussions with authorities over the amount of the rebate. A Samsung India spokesman said the company is committed to being a partner of India and working to make the plan a success.
Labor shortages are emerging in India’s manufacturing hubs, local officials and businesses say. That’s because, unlike in China, many workers are reluctant to relocate long distances in search of work. Trade unions are stronger in India than China.
China encouraged foreign companies to locate supply chains in special economic zones with reduced tariffs on imported components and machinery. By contrast, “Make in India” sought to replace imports with domestically manufactured products by raising import tariffs.
Those tariffs discourage industries that import many components. “India is protectionist in precisely those sectors, goods manufacturing, where the China+1 opportunity arises,” Viral Acharya, an economist at New York University and former deputy governor of India’s central bank, wrote in a report for the Brookings Institution released in March.
In its annual review of India’s economy last December, the International Monetary Fund said its integration into global value chains has stalled.
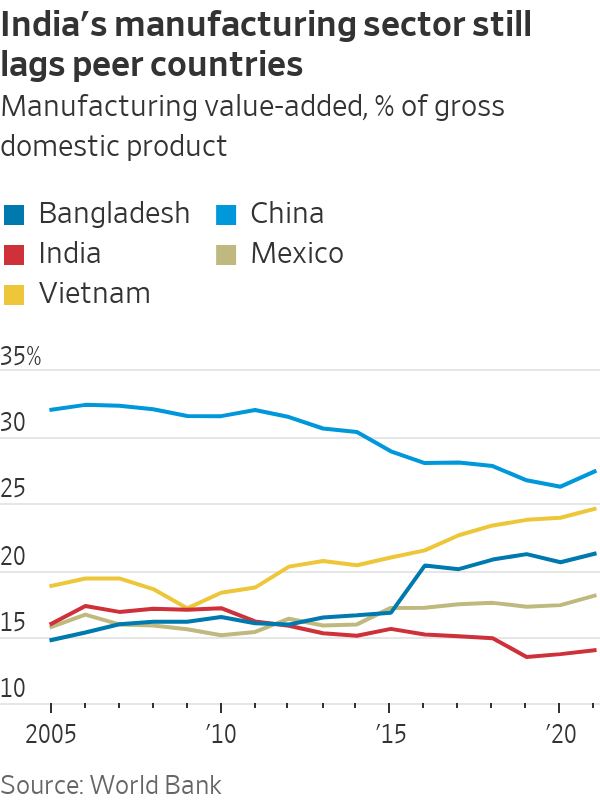
Manufacturing’s share of Indian economic output has actually shrunk since Make in India was launched, to 14% in 2021-–far below that of Mexico, Vietnam and Bangladesh.
Arvind Subramanian, who was Mr. Modi’s chief economic adviser from 2014 to 2018, said for every company such as Apple that has embraced India, several report bad experiences. Even Apple’s investment “wouldn’t have happened without the push from China,” he said.
Amazon.com closed some of its Indian ventures last fall. “We continue to develop and grow the local e-commerce ecosystem,” Amazon said in a statement.
China’s experience suggests creating lots of moderately paid jobs for less-educated rural workers, especially women, requires manufacturing.
In Tamil Nadu, a homegrown unicorn, Ola Electric, embodies those hopes. India is the world’s largest market for two-wheeled motorcycles and scooters, and Ola has made a splash with its brightly painted scooters catering to demand for electric vehicles.
New registrations for electric two-wheelers have grown more than tenfold over the past two years to 684,273 in the latest financial year ended March 31, according to the Council on Energy, Environment and Water, a New Delhi-based think tank.
Ola is making half a million electric scooters a year from its new plant. It plans to quadruple factory floor space, including two acres reserved for an indoor forest. The company says it will start making electric cars from early 2024.
The airy plant has an almost all-female workforce, from security guards to workers wielding spray guns of paint, to those who test-ride the final product.
“Initially, their parents were hesitant to let them work in factories,” said Jayaraman G., Ola’s associate director of corporate affairs. “No more. In the last one year, they saw how the situation changed financially–from paying for the education of their siblings to helping build two- or three-room apartments. It’s a proud moment for their families.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

New research suggests that bonuses make employees feel more like a mere cog in a wheel.
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.