China Unleashes Crackdown on ‘Pig Butchering.’ (It Isn’t What You Think.)
Beijing is going after scam mills that operate out of secretive, dystopian compounds and swindle people worldwide

 4 min
It’s called “pig butchering.”
Armies of scammers operating from lawless corners of Southeast Asia—often controlled by Chinese crime bosses—connect with people all over the world through online messages. They foster elaborate, sometimes romantic, relationships, and then coax their targets into making bogus investments. Over time, they make it appear that the investments are growing to get victims to send more money. Then, they disappear.
In recent months, China has unleashed its most aggressive effort to crack down on the proliferation of the scam mills, reaching beyond its territory and netting thousands of people in mass arrests. Its main target is a notorious stretch of its border with Myanmar controlled by narcotics traffickers and warlords.
For decades, frontier fiefdoms such as those in Myanmar have been havens for gambling and trafficking of everything from drugs to wildlife to people. Now, they are dens for pig-butchering operations.
The scammers operate out of secretive, dystopian compounds, many of which are run by Chinese fugitives who fled their country to places where it was easier to flout the law. They cheat Chinese citizens out of billions of dollars each year, as well as victims across the globe. The U.S. Treasury Department in September warned Americans about the scams.
In addition to remote hillside towns in Myanmar, these heavily guarded enclaves are also found in gambling hubs such as Cambodia’s Sihanoukville and Poipet. Cambodian authorities have carried out sporadic raids with China’s help, but the problem has persisted.
For Beijing, it is a significant source of embarrassment that Chinese criminals are at the centre of scams ensnaring people the world over, said Jason Tower, Myanmar country director for the United States Institute of Peace, an independent research organisation founded by the U.S. Congress that specialises in conflict mitigation.
China is “quite sensitive to the narratives that could potentially emerge,” he said. “These are largely Chinese crime groups which China, for years, did very little to check.”
The operations flourished during the Covid-19 pandemic when border trade stopped and internet use surged. They have also fuelled a human-trafficking crisis.
Many of the scammers entrapping people are themselves victims of human trafficking, lured abroad by fake job ads and held captive by withholding pay and passports. The United Nations human-rights office says more than 120,000 people may be forced to work as scammers in Myanmar, with another 100,000 in Cambodia.
One Malaysian trafficking victim told The Wall Street Journal that he was trained to spend weeks or months “fattening” his victims by gaining their trust before “butchering” them. His story was similar to those told by others lured into working in the scam mills. After responding to an ad on a job-recruitment website, he said he accepted an offer for a customer-service role in Cambodia. Once there, he was driven to a prison-like complex in Sihanoukville and forced to work as a scammer under threats of violence.
He said he had a handler who trained him, supplying him with a smartphone preloaded with fake social-media accounts, a “victim list” containing contact information of potential targets and various scripts designed to break the ice and build their trust. After several weeks, he said he convinced a driver who brought people and supplies to the compound to help him escape.
Regional migration researchers have documented trafficking from dozens of countries. Many victims come from Southeast Asia but some from as far as Brazil and Kenya.
“China is starting to signal that enough is enough,” said Inshik Sim, a Bangkok-based lead analyst for the U.N. Office on Drugs and Crime’s regional operations.
In August, China launched a “special joint operation” with three nearby countries and increased pressure on armed groups that oversee remote parts of Myanmar, convincing them to hunt down, round up and repatriate almost 5,000 Chinese nationals suspected of illicit activity.
Chinese authorities have zeroed in on several border areas that are part of Myanmar but are fully controlled by armed groups. These places have often drawn large investments from Chinese nationals—both legal and illicit. Many Chinese people, including notorious fugitives, live in these enclaves, where the Mandarin language and Chinese currency are commonplace.
The Wa Self-Administered Division, located along China’s southwestern border, is of particular interest to China, in part because Beijing has so much leverage over it. The area is home to the ethnic minority Wa people, who claim the territory as their ancestral home. China has been the group’s main benefactor for decades; historians say they helped the Chinese Communist Party flush out enemies who fled across the border in the 1950s and ’60s. The area later became a major economic gateway to resource-rich Myanmar.
Independent researchers say its de facto leadership, the United Wa State Army, commands a force of more than 20,000 people armed with modern Chinese equipment such as portable surface-to-air missiles and armoured vehicles.
The area has been a major source of opium for almost two centuries, and in recent decades has become a leading producer of synthetic drugs such as methamphetamine. The U.S. Treasury blacklisted the UWSA in 2003 under the Kingpin Act, and has sanctioned dozens of people and businesses linked to the group, calling it “the largest and most powerful drug trafficking organisation in Southeast Asia.”
The UWSA and other criminal networks have increasingly turned to scamming in addition to the drug trade.
According to a 2022 report in Chinese state media, authorities blocked 2.1 million fraudulent websites and some $51.6 billion in suspicious transactions over the previous year. Beijing has warned citizens to look out for dubious rebate offers, investment schemes and unsolicited contact from anyone claiming to represent a company or law enforcement.
The first sign of a serious cleanup came in early September, when China worked with the UWSA to orchestrate two days of raids that ended with more than 1,000 suspects being marched across the border into Chinese custody. Then China upped the ante, taking aim at the group’s leadership.
On Oct. 12, China’s Ministry of Public Security said arrest warrants had been issued for two senior Wa officials accused of leading scam networks: the state’s construction minister Chen Yanban and a mayor named Xiao Yankui. Four days later, the UWSA said both had been stripped of their roles. Their whereabouts is unknown.
The same day, Chinese authorities said they had transferred 2,349 “telecommunication fraud” suspects from Myanmar two days prior—the single largest such handover. China says 4,666 suspects have been repatriated from Myanmar since the crackdown began earlier this year.
“This is by any measure a major operation, which speaks to the impact on China and Chinese citizens, and the seriousness with which Beijing is approaching this,” said Richard Horsey, senior adviser on Myanmar for the International Crisis Group, a Brussels-based think tank specializing in conflict prevention.
While China may be turning up the heat on cybercriminals along its border, experts say scamming is so lucrative that the ringleaders are likely to simply look for more fertile ground—areas in weak states where law enforcement is lax.
“These groups are not going to go away easily,” said Tower, of the U.S. Institute of Peace. “They’re sitting on a massive source of capital and there are many fragile places in the world that they’ll be able to exploit.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.
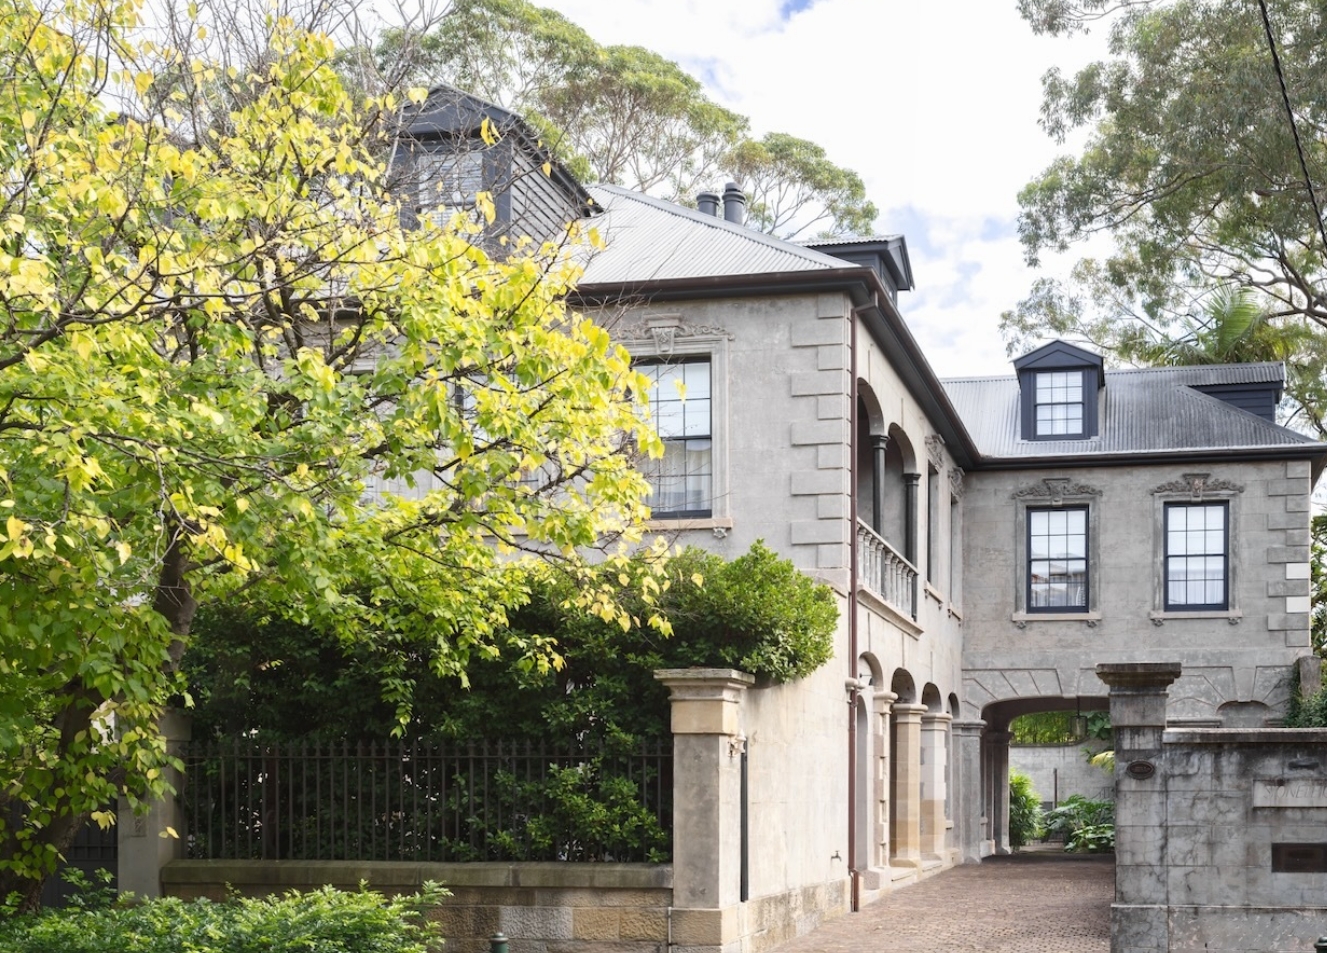
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …