Corporate Layoffs Spread Beyond High-Growth Tech Giants
Dow, IBM and SAP say they will lay off thousands of workers as belt-tightening becomes the new business priority

 4 min
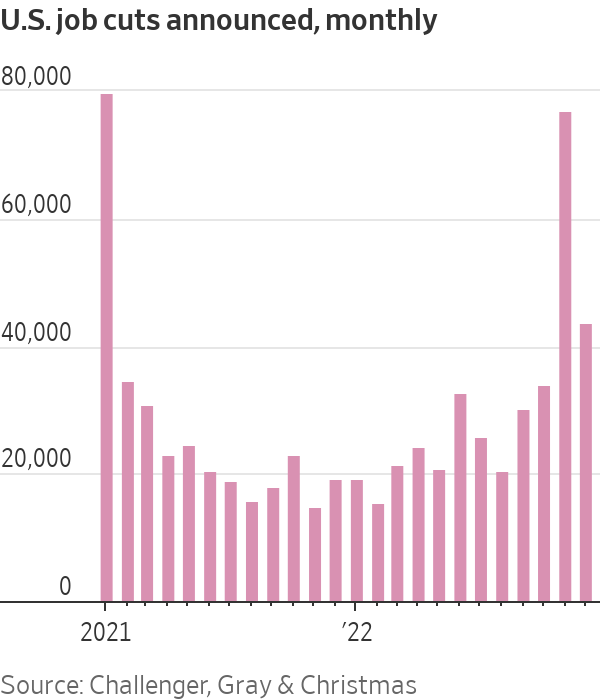
Dow Inc., International Business Machines Corp. and SAP SE announced plans to cut thousands of jobs to prepare for a darkening economic outlook, as the current wave of corporate layoffs spreads beyond high-growth technology companies.
Together with layoffs announced by manufacturer 3M Co. this week, these companies are trimming more than 10,000 jobs, just a fraction of their total workforces. Still, the decisions mark a shift in sentiment inside executive suites, where many leaders have been holding on to workers after struggling to hire and retain them in recent years when the pandemic disrupted workplaces.
Unlike Microsoft Corp. and Google parent Alphabet Inc., which announced larger layoffs this month, these companies haven’t expanded their workforces dramatically during the pandemic. Instead, the leaders of these global giants said they were shrinking to adjust to slowing growth, or responding to weaker demand for their products.
“We are taking these actions to further optimise our cost structure,” Jim Fitterling, Dow chief executive, said in announcing the cuts, noting the company was navigating “macro uncertainties and challenging energy markets, particularly in Europe.”
The U.S. job market remains historically tight, with unemployment in December at 3.5% matching multi decade lows. The number of job openings still far outpaces the number of people looking for work. The Federal Reserve has been raising interest rates to tame growth and combat high inflation. But CEOs say many companies are beginning to scrutinise hiring more closely.
Slower hiring has already lengthened the time it takes Americans to land a new job. In December, 826,000 unemployed workers had been out of a job for about 3½ to 6 months, up from 526,000 in April 2022, according to the Labor Department.
“Employers are hovering with their feet above the brake. They’re more cautious. They’re more precise in their hiring,” said Jonas Prising, chief executive of ManpowerGroup Inc., a provider of temporary workers. “But they’ve not stopped hiring.”
Additional signs of a cooling economy emerged on Thursday when the Commerce Department said U.S. gross domestic product growth slowed to a 2.9% annual rate in the fourth quarter, down from a 3.2% annual rate in the third quarter.
Not all companies are in layoff mode. Walmart Inc., the country’s biggest private employer, said this week it was raising its starting wages for hourly U.S. workers to $14 from $12, amid a still tight job market for front line workers. Chipotle Mexican Grill Inc. said Thursday it plans to hire 15,000 new employees to work in its restaurants, while plane maker Airbus SE said it is recruiting over 13,000 new staffers this year. Airbus said 9,000 of the new jobs would be based in Europe with the rest spread among the U.S., China and elsewhere.
General Electric Co., which slashed thousands of aerospace workers in 2020 and is currently laying off 2,000 workers from its wind turbine business, is hiring in other areas. “If you know any welders or machinists, send them my way,” Chief Executive Larry Culp said this week.
Annette Clayton, CEO of North American operations at Schneider Electric SE, a Europe-headquartered energy-management and automation company, said the U.S. needs far more electricians to install electric-vehicle chargers and perform other tasks. “The shortage of electricians is very, very important for us,” she said.
Railroad CSX Corp. told investors on Wednesday that after sustained effort, it had reached its goal of about 7,000 train and engine employees around the beginning of the year, but plans to hire several hundred more people in those roles to serve as a cushion and to accommodate attrition that remains higher than the company would like.
Freeport-McMoRan Inc. executives said Wednesday they expect U.S. labor shortages to continue to crimp production at the mining giant. The company has about 1,300 job openings in a U.S. workforce of about 10,000 to 12,000, and many of its domestic workers are new and need training and experience to match prior expertise, President Kathleen Quirk told analysts.
“We could have in 2022 produced more if we were fully staffed, and I believe that is the case again this year,” Ms. Quirk said.
The latest layoffs are modest relative to the size of these companies. For example, IBM’s plan to eliminate about 3,900 roles would amount to a 1.4% reduction in its head count of 280,000, according to its latest annual report.
The planned 3,000 job cuts at SAP affect about 2.5% of the business-software maker’s global workforce. Finance chief Luka Mucic said the job cuts would be spread across the company’s geographic footprint, with most of them happening outside its home base in Germany. “The purpose is to further focus on strategic growth areas,” Mr. Mucic said. The company employed around 111,015 people on average last year.
Chemicals giant Dow said on Thursday it was trimming about 2,000 employees. The Midland, Mich., company said it currently employs about 37,800 people. Executives said they were targeting $1 billion in cost cuts this year and shutting down some assets to align spending with the macroeconomic environment.
3M, which had about 95,000 employees at the end of 2021, cited weakening consumer demand for its plans to eliminate 2,500 manufacturing jobs. The maker of Scotch tape, Post-it Notes and thousands of other industrial and consumer products said it expects lower sales and profit in 2023.
“We’re looking at everything that we do as we manage through the challenges that we’re facing in the end markets,” 3M Chief Executive Mike Roman said during an earnings conference call. “We expect the demand trends we saw in December to extend through the first half of 2023.”
Some companies still hiring now say the job cuts across the economy are making it easier to find qualified candidates. “We’ve got the pick of the litter,” said Bill McDermott, CEO of business-software provider ServiceNow Inc. “We have so many applicants.”
At Honeywell International Inc., CEO Darius Adamczyk said the job market remains competitive. With the layoffs in technology, though, Mr. Adamczyk said he anticipated that the labor market would likely soften, potentially also expanding the applicants Honeywell could attract.
“We’re probably going to be even more selective than we were before because we’re going to have a broader pool to draw from,” he said.
Across the corporate sphere, many of the layoffs happening now are still small relative to the size of the organisations, said Denis Machuel, CEO of global staffing firm Adecco Group AG.
“I would qualify it more as a recalibration of the workforce than deep cuts,” Mr. Machuel said. “They are adjusting, but they are not cutting the muscle.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

With two waterfronts, bushland surrounds and a $35 million price tag, this Belongil Beach retreat could become Byron’s most expensive home ever.
Rising rates, construction inflation and shrinking investor confidence are pushing Australia deeper into a dangerous housing spiral that monetary policy alone cannot fix.