DeepSeek Deep Sixes the Stock Market. How Far the S&P 500 Could Fall

 3 min

DeepSeek just might derail the stock market’s rally.
The S&P 500 hasn’t had a correction , a 10% pullback from a high, since October 2023. Investors kept buying throughout 2024 despite angst surrounding the Federal Reserve and interest rates, not to mention numerous international concerns.
But now, worries about cheaper artificial intelligence models from the Chinese-developed app named DeepSeek may be the excuse that investors were waiting for to finally sell shares in earnest. Stocks plunged Monday .
The declines were biggest in ing tech companies, such as Nvidia , Broadcom and Microsoft . But other sectors, namely manufacturing and the utility or energy stocks that have big ties to the AI theme, were hit hard as well
The S&P 500 and Nasdaq Composite tumbled 1.5% and more than 3% respectively. The Dow Jones Industrial Average , which is less exposed to tech, gained nearly 300 points, or 0.7% .
The market is now closer to correction territory than it has been since August , when worries about a surge in the value of the Japanese yen versus the dollar spooked investors and led to a spike in volatility. But the major stock indexes still have a way to go before the declines from their peaks reach 10%.
The S&P 500 ended Monday at around 6012 , putting it just 2% below its record high. The blue-chip index would need to fall another 8% to just above 5500 to reach correction status. The Nasdaq is closer: It has fallen more than 4% from its peak and is 6% above the correction- territory level of 18,156.50.
But even before Monday’s DeepSeek bombshell, there were growing concerns that stocks may head into a correction. Barry Bannister, chief equity strategist at Stifel, recently reiterated a July call for the S&P 500 to fall 10% from its peak. He thinks it will drop to about 5500 later this year.
Bannister has been fairly bearish for the better part of a year. He said in a report Sunday that there is too much optimism about fiscal stimulus from President Donald Trump; the notion of American exceptionalism, or that stocks here have better prospects because the U.S. economy is more innovative and entrepreneurial; and hype about the Magnificent Seven of tech.
Bannister worries that core inflation and longer-term bond yields will remain higher for longer, creating a “a mild case of stagflation”—the dreaded combination of stagnant growth and persistent inflation. That may mean fewer Fed rate interest-rate cuts until the economy actually weakens, “which itself is not bullish,” Bannister wrote.
Trump’s threat of tariffs and stricter immigration policies, which would boost the cost of imported goods and potentially drive wages higher by curtailing the supply of labor, may also stoke fear of more persistent inflation.
So what should investors do now?
Bannister argues that “defensive value” stocks, such as healthcare and consumer staples companies, should outperform. Investors seem to agree: Both the Health Care Select Sector SPDR and the Consumer Staples Select Sector SPDR exchange-traded funds were up more than 2% as the broader market fell on Monday.
Bannister likes utilities too, but that sector is trickier. The group as a whole sank Monday, led lower by significant drops in Vistra and Constellation Energy , the two utilities that have gotten the biggest boost from AI’s demand for energy. But shares of classic, less exciting, regulated utilities, such as Duke Energy, Dominion Energy, and Xcel Energy , rallied. All three stocks have big dividend yields.
Dividend payers across all sectors could hold up better in a suddenly more volatile market. Simeon Hyman, global investment strategist with ProShares , told Barron’s that companies that pay dividends tend to be more stable. Companies may pull back on plans to buy back more stock or invest in their future if conditions change, but with rare exceptions “once you commit to dividend growth, you stick with it,” he said.
The SPDR S&P Dividend ETF and ProShares S&P 500 Dividend Aristocrats ETF , which recently added FactSet Research System , Erie Indemnity , and Eversource Energy to the fund, were both up nearly 2% Monday.
Still, even investors in dividend stocks need to be wary. There could be more downside ahead for the broader market. Simply put, stocks are arguably long overdue for a correction.
“The last time the market entered an official correction was 309 trading days ago, spanning well beyond the average number of 173 trading days without a correction since 1928,” Adam Turnquist, chief technical strategist for LPL Financial , said in a report last week.
There is a case to be made that there was too much optimism on the part of investors. Katie Stockton, founder and managing partner of Fairlead Strategies, noted that the Cboe Volatility Index, known as Wall Street’s fear gauge, recently fell to levels in the midteens from a three-month high of nearly 28 in mid-December. She thinks a VIX reading that low was reflecting complacency. The VIX surged to just under 20 Monday.
Stockton now thinks that Monday’s market pullback could lead to more downside for the next few weeks. She said investors should keep an eye on two key technical support levels for the S&P 500: the closing level of about 5783 that it traded at on Election Day, and if stocks dip below that, the 200-day moving average of 5608.
Remember, the level that would bring the market into correction territory is just above 5500, in flirting distance from the 200-day average.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
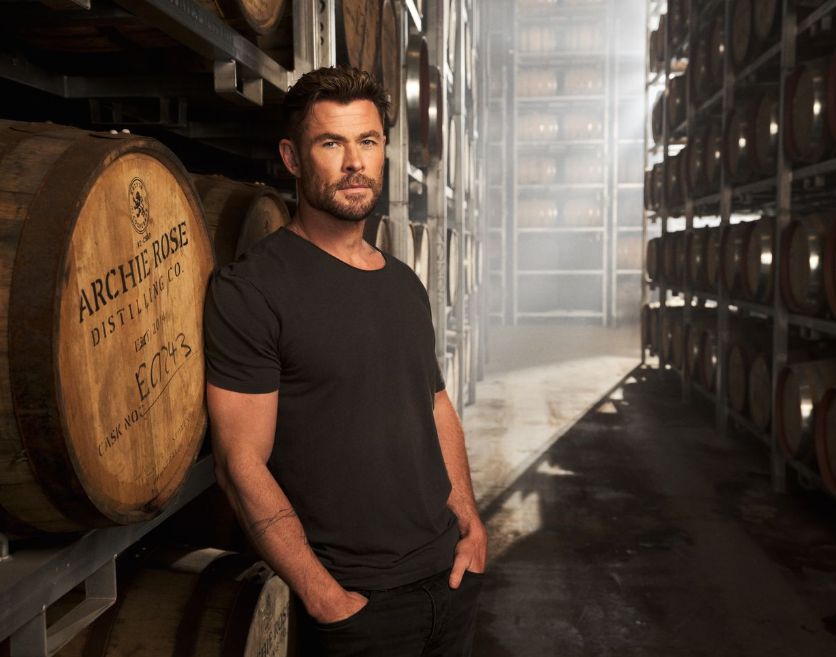
Australian actor Chris Hemsworth has joined Archie Rose Distilling Co. as co-owner and strategic business partner as the Sydney spirits company prepares to enter the United States. The partnership brings Hemsworth together with Archie Rose founder Will Edwards, with the pair aiming to build greater international recognition for Australian whisky. Founded in Sydney in 2014, …
Continue reading “Chris Hemsworth Joins Archie Rose as Co-Owner Ahead of Global Expansion”