





Go Woke, Go Broke? Not a Chance, Say Ben and Jerry
Still best friends, Ben & Jerry’s founders speak about mixing politics with business, the ice cream brand’s future and why Ozempic doesn’t worry them

 5 min

Ben Cohen and Jerry Greenfield are about as well known for their progressive politics as they are for quirky ice cream flavors like Chunky Monkey and Phish Food.
Their experiment in melding business with social justice for years seemed like a model that many in the corporate world were warming up to. And then attitudes cooled.
Some businesses have started to put less emphasis on the kinds of social and political issues that Ben & Jerry’s has championed. Certain investors have urged corporations to stick with what they know best.
For their part, the lifelong friends, both now 73 years old, say their style of corporate activism isn’t bad for business—just the opposite.
Most companies aren’t comfortable engaging with social issues because “they don’t want to potentially alienate customers,” says Greenfield. “The irony is for Ben & Jerry’s, that is what makes the company successful.”
Cohen and Greenfield say the brand is now at a crossroads after parent company Unilever said in March that it would spin off or sell its ice cream division , a move interpreted by some as the culmination of a failed experiment in mixing progressive politics with big business.
While Ben & Jerry’s has for decades worn its heart on its sleeve, some of the brand’s political pronouncements in recent years have angered certain consumers and investors. Cohen believes this is at least partly the reason for its owner’s decision to part ways. For Unilever, “Ben & Jerry’s creates a lot of problems,” he says.
Cohen and Greenfield, who still count as Unilever employees, say the upset is worth it.
The founders shared internal sales data with The Wall Street Journal that showed the brand had logged stronger sales growth than its parent’s broader ice cream business in three of the past five years. Neither side disclosed profit figures.
Unilever’s ice cream head, Peter ter Kulve , says that, “whilst we don’t always agree” with Ben & Jerry’s, the combination of the company’s leadership, the brand’s board and founders’ involvement has been successful.
Do Cohen and Greenfield think the brand could be better off with a new owner? “To have a values-aligned owner of Ben & Jerry’s would be a beautiful thing,” says Cohen.
Of all the multinationals that could have bought Ben & Jerry’s, Unilever—given its historic focus on sustainability—was seen as perhaps the best fit. But in recent years a marketing strategy aimed at imbuing all of Unilever’s brands with a social or environmental purpose fell flat . Unilever has since narrowed the strategy to a few big brands.
Both men earned millions from Unilever’s $326 million purchase of their ice cream brand and say the deal hasn’t been all bad. Unilever helped Ben & Jerry’s expand internationally—it is now sold in 43 countries—and figure out the nuts and bolts of building new factories. It also gave the brand a bigger platform to push its social mission, albeit less aggressively than the founders would have liked.
In recent years a handful of prominent brands have been hit by consumer boycotts after wading into the culture wars. Companies are also being presented with more investor proposals against environmental and social initiatives while some activists are taking companies to court over their diversity and inclusion pledges. The upshot is that companies, particularly in the U.S., are talking less about their ESG efforts.
Cohen and Greenfield say they understand the pressure public companies—including Unilever—are under to avoid thorny issues but think this limits their growth prospects. Consumers, particularly younger ones, expect brands to speak out about issues like war, racism and climate change, they say.
Frosty relations
Ben & Jerry’s began in 1978, when Cohen and Greenfield started selling ice cream out of a gas station in Burlington, Vt. They threw chunks of candy and nuts into partially frozen smooth ice cream largely because the heavily textured result appealed to Cohen, whose poor sense of smell impedes his ability to taste.
Alongside whimsically named flavours, social activism became a part of the brand’s identity early on. In 1988, Cohen and Greenfield launched Peace Pops, a chocolate-covered ice cream on a stick that advocated for cuts to U.S. military spending.
By the 90s, the brand had become one of America’s most recognisable brands, later that decade attracting takeover interest. Cohen and Greenfield say they didn’t want to sell but, as a public company, had to put Unilever’s offer to shareholders.
To keep the founders happy, Unilever agreed to let Ben & Jerry’s retain an independent board that would dictate the company’s social mission.
Despite this, “the first few years were rough,” remembers Cohen.
Unilever cut costs, making pints with less butterfat and using smaller, cheaper chunks. A proposed new flavor intended to celebrate Vermont’s law legalising civil unions for same-sex couples was scrapped.
Over the years, “the social mission rose or fell based on who the CEO was,” says Cohen. “If the CEO was into it, it prospered and if the CEO wasn’t it didn’t.”
Unilever preferred to attach its brands to more neutral causes , like reducing food waste or improving sanitation. Ben & Jerry’s, by contrast, publicly opposed what it described as Donald Trump’s “regressive agenda” by launching a flavour called Pecan Resist. It accused President Biden on social media of fanning the flames of war by sending troops to Europe after Russia’s invasion of Ukraine.
Tensions between the brand and its parent burst into public view soon after Ben & Jerry’s said it would halt sales in Jewish settlements in the Israeli-occupied West Bank and contested East Jerusalem in July 2021. It said selling in those settlements, considered illegal by much of the international community , was inconsistent with its values.
The move prompted some consumers to boycott Unilever’s brands, and U.S. pension funds to sell shares in the company.
Unilever tried to quell the furor by selling Ben & Jerry’s business in Israel without its permission. The brand then sued its parent , saying it had violated the acquisition agreement. The two sides eventually settled, but tensions persist.
“There is no other entity like Ben & Jerry’s at Unilever,” says Cohen. “They don’t understand it, they don’t really know how to deal with it and they want to run it like any other brand that they own.”
In January, Unilever prevented Ben & Jerry’s from calling for a cease-fire in Gaza, the founders say. The brand circumvented its parent by issuing a statement via its independent board.
How involved Cohen and Greenfield remain depends on to what extent any new owner permits the brand’s board to continue to pursue its social mission.
If bought by a finance-focused entity, Ben & Jerry’s will suffer, Cohen says. “They don’t realize the intangibles that are behind the numbers.”
Still eating ice cream
Born four days apart, Cohen and Greenfield have been best friends since seventh grade.
They live 2 miles from each other near Ben & Jerry’s headquarters in Vermont, and hang out regularly. “It’s more fun to do things together,” says Greenfield.
The pair have dabbled in various construction projects together, building a gazebo, cabin and bench in their free time. “It’s much more beautiful than your usual park bench,” qualifies Cohen. “We didn’t buy any lumber, we just cut down trees.”
They also get together to do physical therapy exercises to help their bad backs but dislike the dead bug, which involves lying on your back and raising and lowering opposite arms and legs.
Both men have remained involved with Ben & Jerry’s and get a salary from Unilever although they have no managerial or operational role at the company. They show up to franchisee meetings, scoop-shop openings and employee training sessions to shake hands and offer encouragement.
They see their main role as bringing visibility to causes the Ben & Jerry’s brand supports. They are currently lobbying to end qualified immunity , the controversial doctrine that says police officers and other officials can’t be sued for misconduct unless they have violated “clearly established” rights.
Recently, Unilever’s new chief executive, Hein Schumacher , visited Vermont, where he met the founders. Cohen describes him as a “nice guy” but says they didn’t spend a lot of time together. “I assume he’s a very good executive,” he says. “Business executive.”
The pair’s favourite flavours—Coconut Almond Fudge Chip for Greenfield and Mocha Walnut for Cohen—have long since hit “the flavour graveyard.” The coconut flavour wasn’t selling well enough while the mocha one drew lots of consumer complaints. “Half of them would say it had too much chocolate in it and the other half would say it had too much coffee,” says Cohen.
How worried are the founders that in an era of weight-loss drugs people could eat less ice cream?
Not at all, they say. Greenfield says people’s relationship with ice cream is about enjoyment or celebration, not nutrition. Still, people should eat ice cream in moderation. “You’re not supposed to eat a whole tub at once,” he says primly.
“I think you can eat a whole tub at once,” interjects Cohen. “You’re just not supposed to do it every day.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
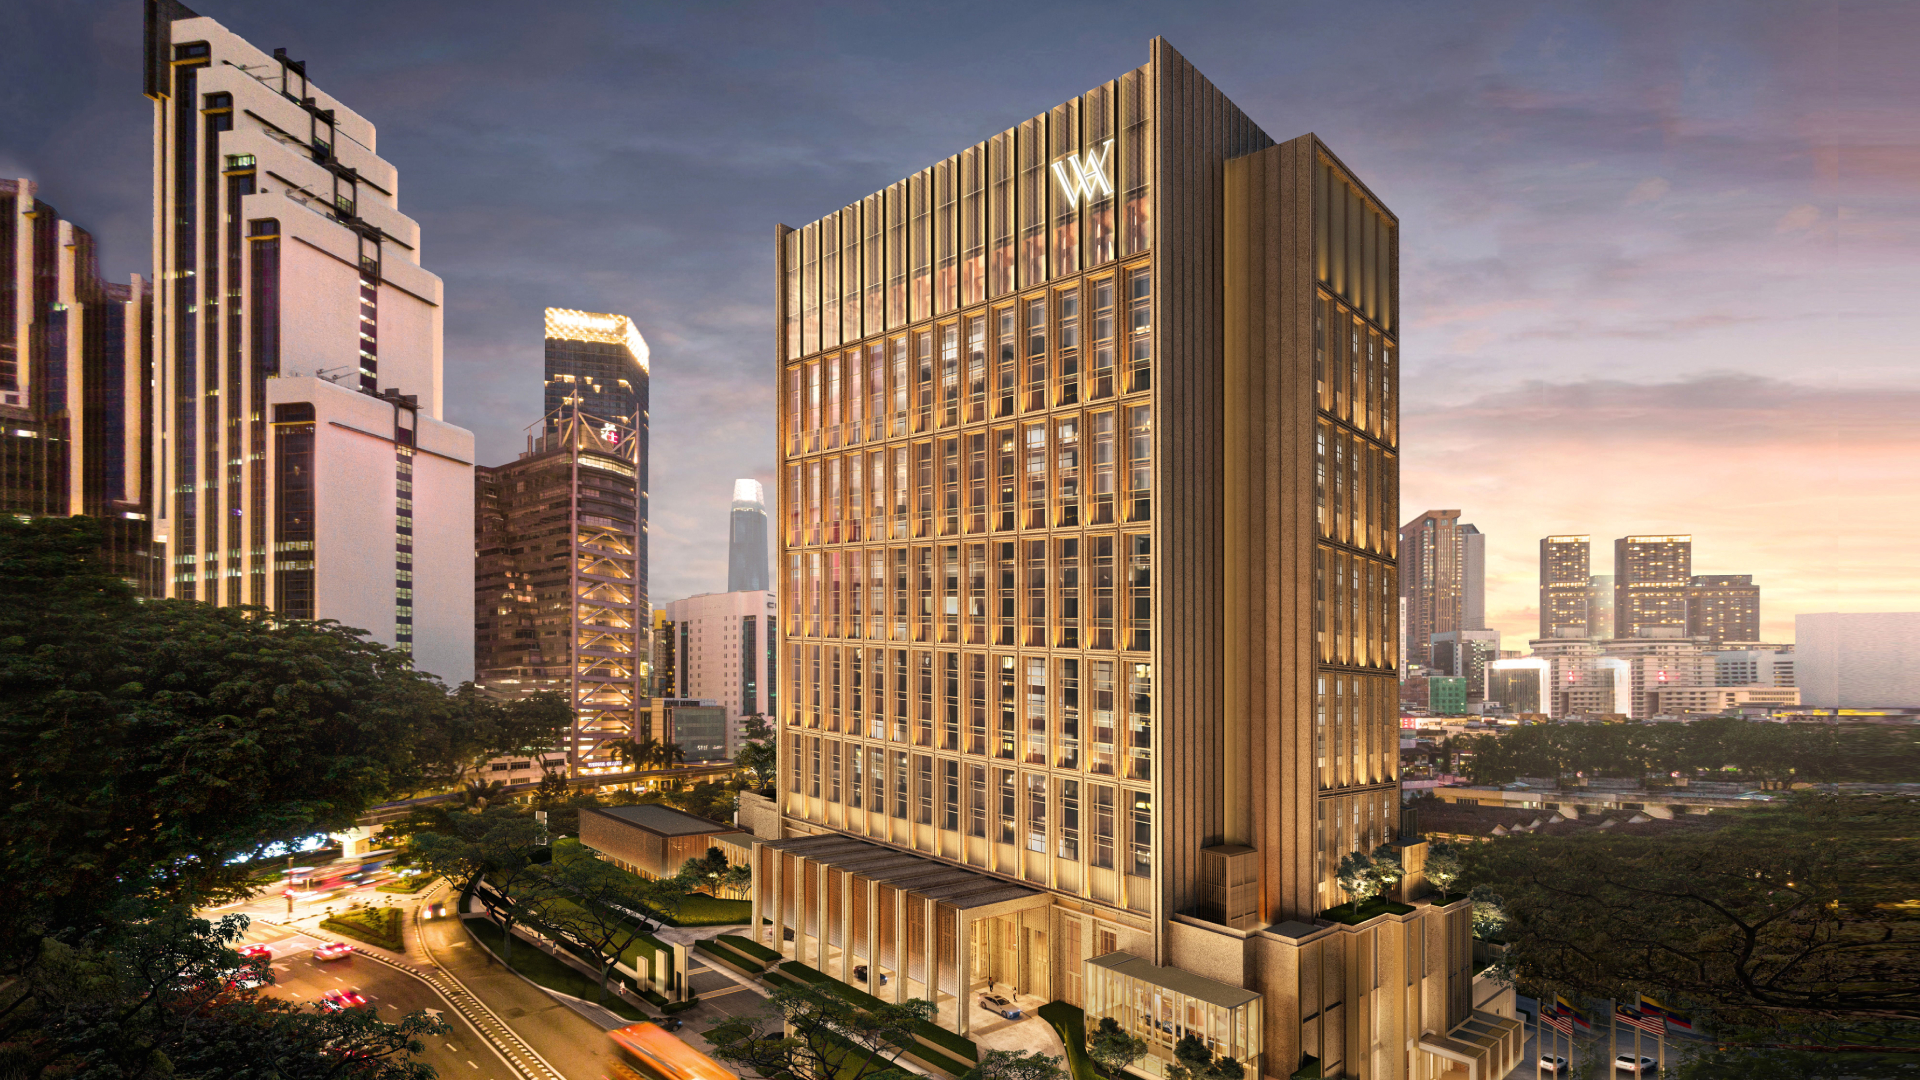
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.
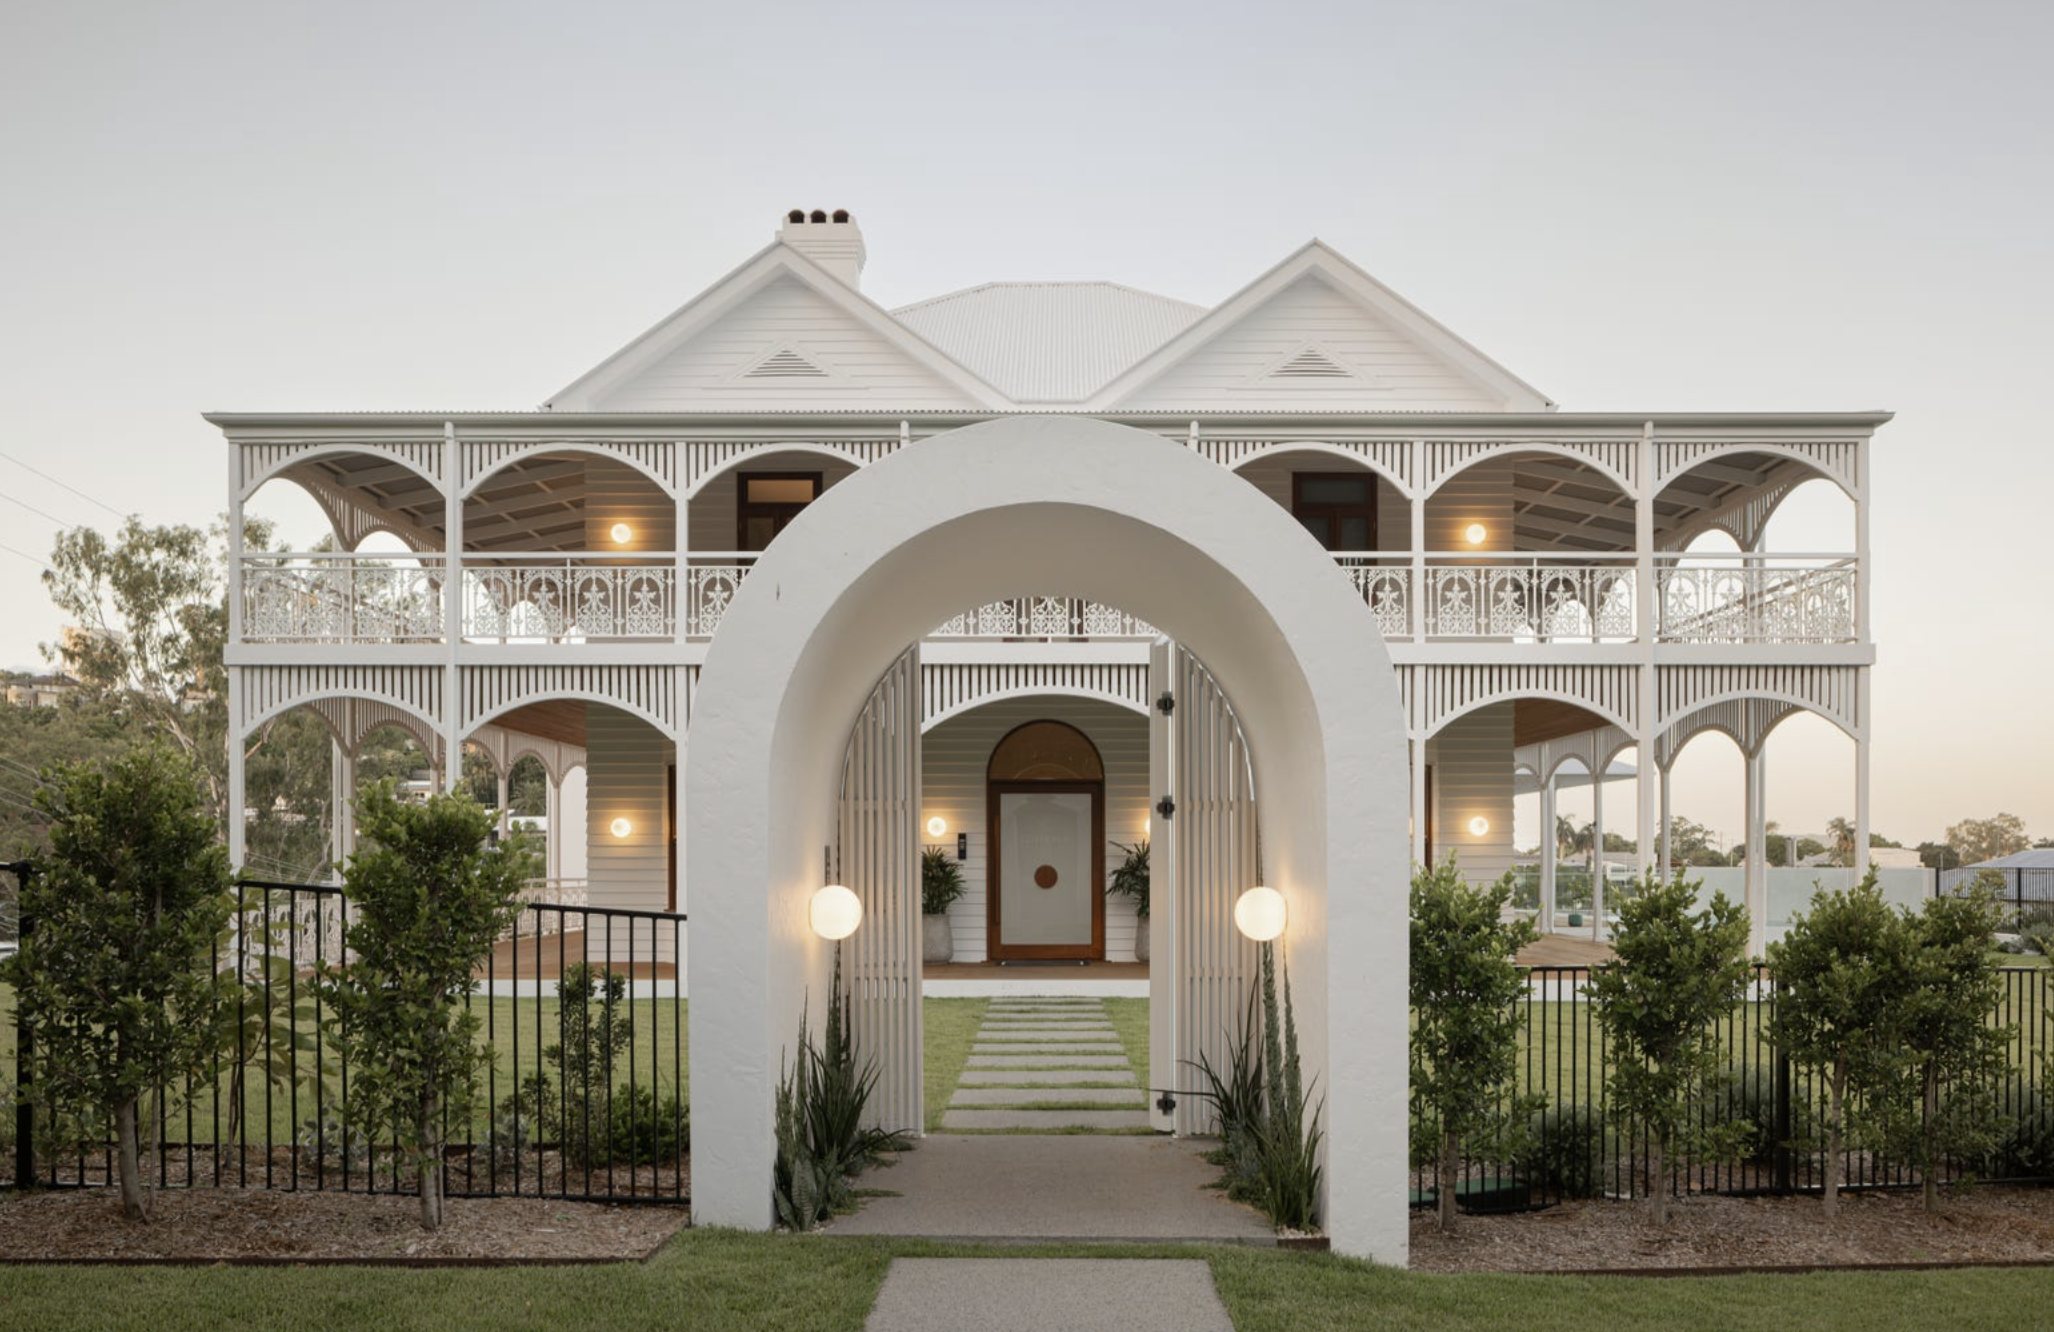
A restored 1860s Brisbane residence transformed by GRAYA has smashed Paddington’s house price record, selling for more than $12 million.


