How TikTok Is Wiring Gen Z’s Money Brain
Endless videos about the economy and consumerism are giving 20-somethings a case of ‘money dysmorphia’

 5 min
Americans under 30 get much of their news on TikTok. They hear about money there, too, and that’s shaping the way they save, spend and view their financial prospects, young adults and economists say.
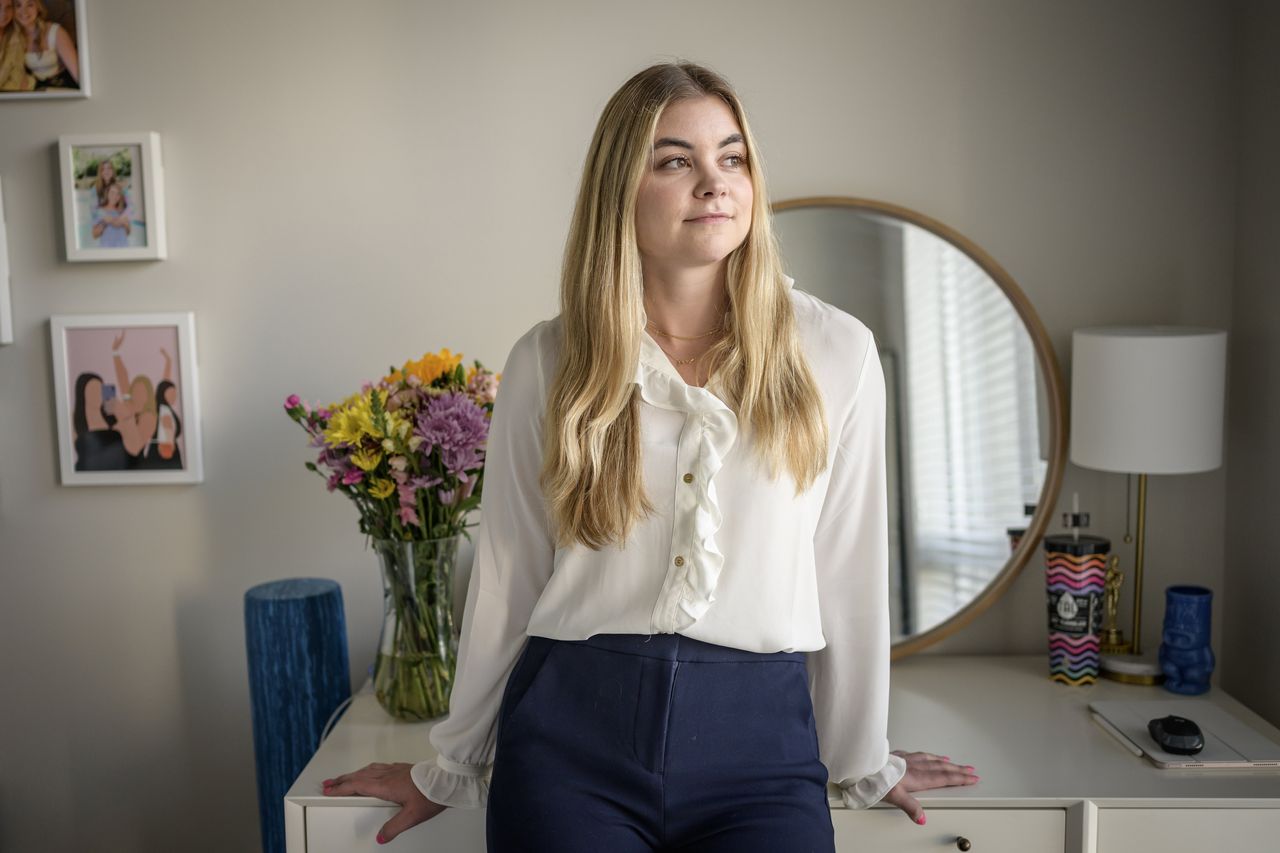
Caitlyn Sprinkle, 27 years old, describes her TikTok feed as a mix of economic gloom and consumerism gone wild. There are Dave Ramsey TikToks that warn of the evils of debt , followed by influencers showing off their shopping hauls of skin-care products and handbags.
Sprinkle, a financial analyst at an asset-management firm in Nashville, Tenn., uses a budgeting app and has been cooking at home lately to save money—and to be able to afford the things she feels she has to buy, like Lululemon leggings. “Between TikTok and having your friends around you, you’re pressured to buy the things because you want to fit in,” she says. “That’s always been the case, but with TikTok it’s more prominent.”
Rallying stocks, rising wages and a tight labor market suggest the economy is stronger than it has been in years. The youngest, lowest-earning professionals don’t feel that way—partly because a large share are carrying consumer debt, and partly because of what they’re seeing on TikTok.
Even as the platform faces a potential ban in the U.S. , it remains a massive cultural force that shapes young adults’ decisions and views. More than half of all U.S. adults ages 18 to 34 use it, according to Pew Research Center, while about a third of those 29 and under say they regularly get news on TikTok , up from less than 10% in 2020.
So, what happens when your main source of news tells you that no one in your generation will be able to buy a house , food prices are spinning out of control and credit-card debt is unavoidable—but also that $2,500 Louis Vuitton bags and $70 moisturisers are, as many videos say, “a must”?
Interviews with finance experts and more than a dozen young adults suggest that the result is confusion, with a side of gloom. Under-30s are taking on debt as they embrace an old idea: If the outlook is bad, why not enjoy life now?
Their own money behaviour
TikTok is creating a disconnect between how well off young adults actually are and how they think they’re doing, according to economists and 20-somethings themselves. That disconnect has given rise to a term financial advisers use to describe young adults’ distorted view of their financial well-being: “money dysmorphia.”
Evelyn Hidalgo, 29, makes her living as a full-time content creator after being laid off from a social-strategist job about a year ago. While she posts about being a mum on a budget, her TikTok feed often shows her trendy items she wishes she had, or a life that seems impossibly far from her own, such as owning a large, beautiful home.
“It doesn’t feel like the norm is your normal,” says Hidalgo, who lives in Nashville with her husband and 20-month-old son. As she looks at the economy on TikTok and other social media, her feed feels “split in half,” between those living an enviable life and those who are struggling.
Gen Z’s mixed economic feelings could have an effect on the outcome of the elections this fall, but the greater impact could be on their long-term financial health, economists say. Feeling financially uncertain can lead to poor choices, such as credit-card debt that eats into retirement funds and necessities such as food and housing, says Jacob Channel, senior economist at LendingTree, an online lending marketplace.
Over the past two years, members of Gen Z—those born between 1997 and 2012—effectively doubled their non mortgage debt, taking on roughly an additional $11,000 on average, according to LendingTree.
Still, younger American adults—those born in the 1990s—saw their median wealth more than quadruple to more than $40,000 between 2019 and 2022, according to the Federal Reserve Bank of St. Louis. That has outpaced the growth rates for previous generations at a similar age, says Lowell Ricketts, a data scientist there.
While many markers of adulthood such as homeownership feel out of reach, young adults are reaping the benefits from the current economic climate, says Monique Morrissey , senior economist at the Economic Policy Institute, a nonprofit economic-research and policy organisation.
“Gen Z and younger millennials are experiencing tailwinds and may not realise that they’re benefiting from a tight labor market that has led to an unusually rapid increase in real wages for younger and lower-wage workers,” she says.
Adding to the confusion is the economy itself. After a string of data showed strength in the labor market, growth is beginning to slow. U.S. employers added a seasonally adjusted 175,000 jobs in April, less than March and below the 240,000 economists anticipated, and unemployment rose to 3.9%, according to the Labor Department.
Keeping up with the Joneses
Many TikTok users say their feeds have become a loop of get-ready-with-me posts, ads, influencer partnerships and videos that encourage them to buy stuff from TikTok’s virtual shop . Some 91% of Gen Zers say they have purchased something they saw on social media, according to a survey from Citizens Pay, a buy-now-pay-later service from Citizens.
BreAunna Rodriguez, a 23-year-old mom of two in Houston, likes to buy TikTok-popular baby clothes and other small things for herself, including eyelash extensions, coconut-oil mouthwash and a pumice stone that influencers said reduces stretch marks.
“It’s hard not to buy things if they say it’s good for me,” she says.
TikTok has influenced bigger decisions, too, she says. Her For You page is filled with young entrepreneurs who snub the idea of a 9-to-5 job. This inspired her to quit her job as an assistant property manager in late 2022 and take a remote, commission-based job for an internet-and-cable company.
“You see a 19-year-old trader on TikTok who only has to work two hours a day, and I was like, ‘How do I do that?’”
Rodriguez says she makes more money now, contributes to a 401(k), pays off her credit card bills each month and puts her annual tax refund into a savings account to help with expenses throughout the year. Her biggest monthly expense is the $2,000 she pays for daycare for her two kids.
The constant videos of consumption—whether it’s a Stanley cup , a Jellycat plush or makeup —are hard to resist. TikTok last year created its own e-commerce engine , TikTok Shop, to compete with online retailers.
About six months ago, Sprinkle bought a Stanley tumbler. “I held out as long as I could,” she says, adding that she had bought several other water bottles that were trending on TikTok.
“There’s an internal pressure among my age range to constantly have these experiences and share them,” says Evan Naar, a 28-year-old lawyer in New York who posts TikToks about Broadway shows he’s seen and a Taylor Swift concert he attended.
Naar, who has several thousand dollars in student debt, says at some point he wants to save more money and buy a house. “A lot of my paycheck goes toward living expenses, travel and Broadway shows,” he says.
OK, doomer
Encountering post after post about the downsides of the economy contributes to “doomerism”—an overwhelming feeling of despair. This has made some young adults thrifty.
“I’m not going to spend my last dollar to keep up with the Joneses,” says Tanayah Thomas, a 23-year-old clothing designer and licensed financial adviser in Staten Island, N.Y. “We have to prepare for what’s to come.”
She’s currently living with her mom to save money.
Tommy Chanthavong, a 27-year-old in Houston who manages social-media accounts for small, local businesses, also moved back home. He says it’s hard to parse the information shown on TikTok: One minute he sees videos saying the U.S. is on the brink of a recession and the next he sees that inflation is easing.
In The Wall Street Journal’s latest quarterly survey of business and academic economists , respondents lowered the chances of a recession within the next year to 29% from 39% in January—the lowest probability since April 2022.
Sprinkle, who shares an apartment with a roommate, says she’d love to own a house one day, but it feels like a distant dream.
“You have to have a level of happiness, and being able to do the things you want and buy the things you want is part of it,” she says. “Do I save all of my money for the future? No. I try to live more in the moment.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Studio apartments have almost disappeared from new Australian developments. Lura is bringing them back to Burleigh Heads from $495,000.

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.