

How to Retire Better, From Retirees Who Learned the Hard Way
Lessons from retirees on the biggest regrets of their postwork lives

 4 min

Thousands of Americans retire every day short on cash, friendships and plans.
Many retirees say they realised too late how they could have prepared for a more financially secure and rewarding postwork life. They would have focused on saving more money to cover the higher cost of living. Or they would have put more time into building relationships, taking better care of their health or cultivating new pursuits.
One reason retirement is so hard to prepare for is we often lack models of postwork life to emulate, retirees and financial advisers say. Though our culture is awash with images of professional success, we are a little hazier on what retirement success looks like and what it takes to achieve.
To sharpen that picture, we asked retirees about what they would do differently if given a second chance. Their regrets offer insights that can help people think and plan better at every life stage.
“Regret makes us feel bad, but it can help us do better,” said Daniel Pink, who researched people’s relationships to regret across a range of areas for his book “The Power of Regret.”
Here are three lessons retirees say they wish they had known sooner.
Investing for retirement means more than money
Jim Pilzner, a retired entrepreneur, regrets not setting goals for himself when he retired about four years ago. Now 78, he found there is only so much golf to play and only so many lunches to go to.
“I would counsel my younger self, and any other active, achieving person to recognise what drives them and what success really means,” said Pilzner.
He eventually figured out that the two things that motivated him most during his career—taking action and learning new things—were the same recipe he needed for retirement.
So this spring he enrolled at University of Nevada, Reno with two classes (earning a 4.0) and will be full-time in the fall. He is studying for a degree in political science and history.
Retirees frequently don’t realise how much their career provided a sense of identity and self-worth. Many fail to grasp the need to plan for a different source of purpose in retirement, said Betty Wang, a financial adviser in Denver.
People carefully plan how they will spend money in retirement but often give far less thought to how to spend their time.
Jay Holt, 74, regrets not retiring sooner. He planned to spend his postwork years playing polo. But in 2015, he fell while playing and had to give up the sport.
The resident of Cincinnatus, N.Y., who retired in 2013 at age 64, now wishes he had had a few more years in which to enjoy this activity.
Relationships are the key to retirement
The best predictor of longevity, health and happiness in later life is the quality of your relationships. That is the finding of the Harvard Study of Adult Development, which has followed families for decades.
Dan Roberts, 72, in Idyllwild, Calif., wishes he had kept up with former colleagues for personal and professional reasons.
Roberts retired about 18 months ago. Soon after, his son and his family, who were living just two hours away, moved to New Zealand.
Roberts and his wife, Robin Roberts, said only two visits a year are doable on their budget. He said he would have been able to afford more-frequent trips had he kept the door open to contract work by maintaining both his relationships with former colleagues and a project-management certification.
“We miss our grandchildren terribly,” his wife said.
David Edmisten, an adviser in Prescott, Ariz., said clients sometimes regret delaying retirement for this reason. The extra years working come at the cost of missing time with family and friends and postponing trips, he said.
“Some even had people close to them pass away and regret not being able to spend more time with their loved ones while they still could,” Edmisten said.
Retirement is longer than you think
Arthur Parmentier, 69, regrets retiring at 65, rather than working a few more years, partly because he missed out on a few more years of contributions to his retirement account.
The Providence, R.I., resident claimed Social Security at 65, accepting a lower monthly benefit than he would have received by waiting.
“Had I waited two more years or maybe three, I would have been quite comfortable, but right now, I’m living on Social Security and trying not to touch my IRA,” said Parmentier. “I think now that I may live well into my 80s, so I have to be prepared for that and make sure my IRA will last me throughout those years.”
The life expectancy for a 65-year-old is 84 for men and nearly 87 for women, according to projections by the Society of Actuaries based on 2019 data. Surveys suggest many Americans vastly underestimate those numbers. Of 1,500 adults ages 45 to 80 polled by the Society of Actuaries in 2015, 41% of pre retirees and 37% of retirees underestimated their life expectancy by five or more years, while 14% of pre retirees and 18% of retirees underestimated it by two to four years.
Social Security allows people to start their retirement benefits any time between ages 62 and 70, and increases the payment for every month of delay.
For many, the math favours starting at 70, when monthly benefits before cost-of-living adjustments are 76% higher than at 62, according to Laurence Kotlikoff, a Boston University economist.
A person who postpones benefits until age 70 instead of 62 would have to live to at least 80 to come out ahead, said Kotlikoff, founder of MaximizeMySocialSecurity.com, which advises people on claiming decisions.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices
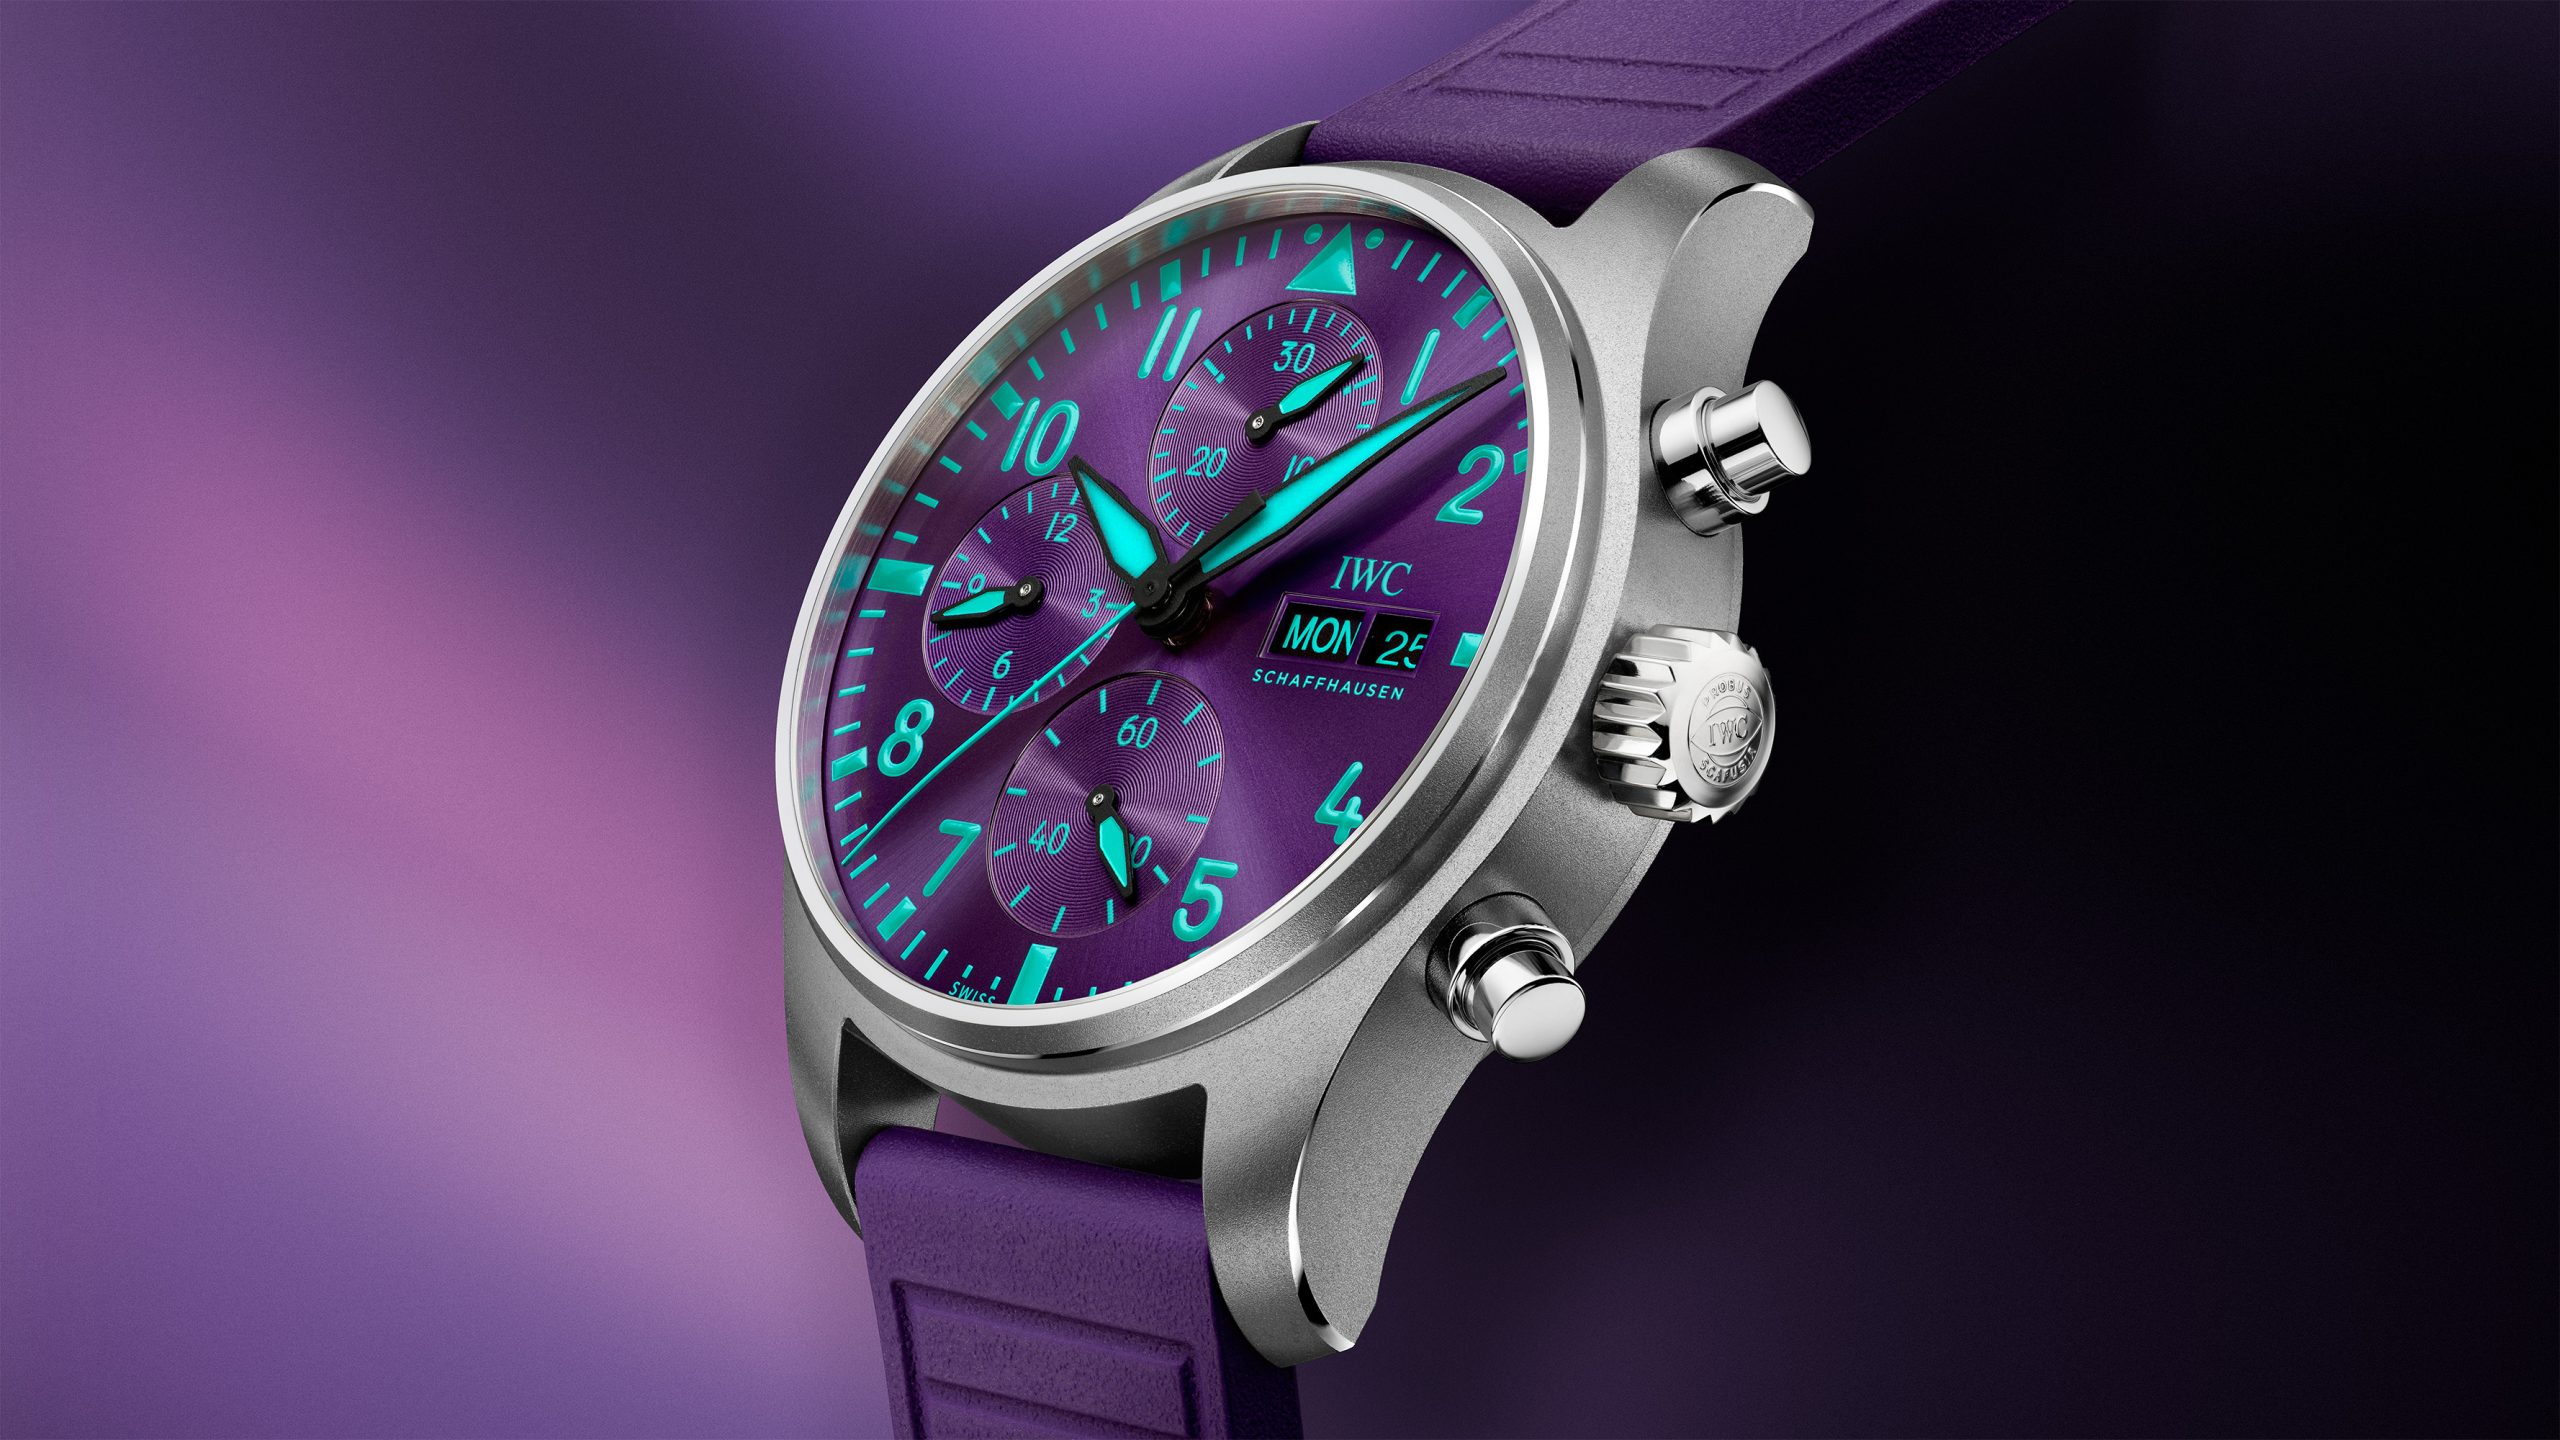
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”
Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.
3 min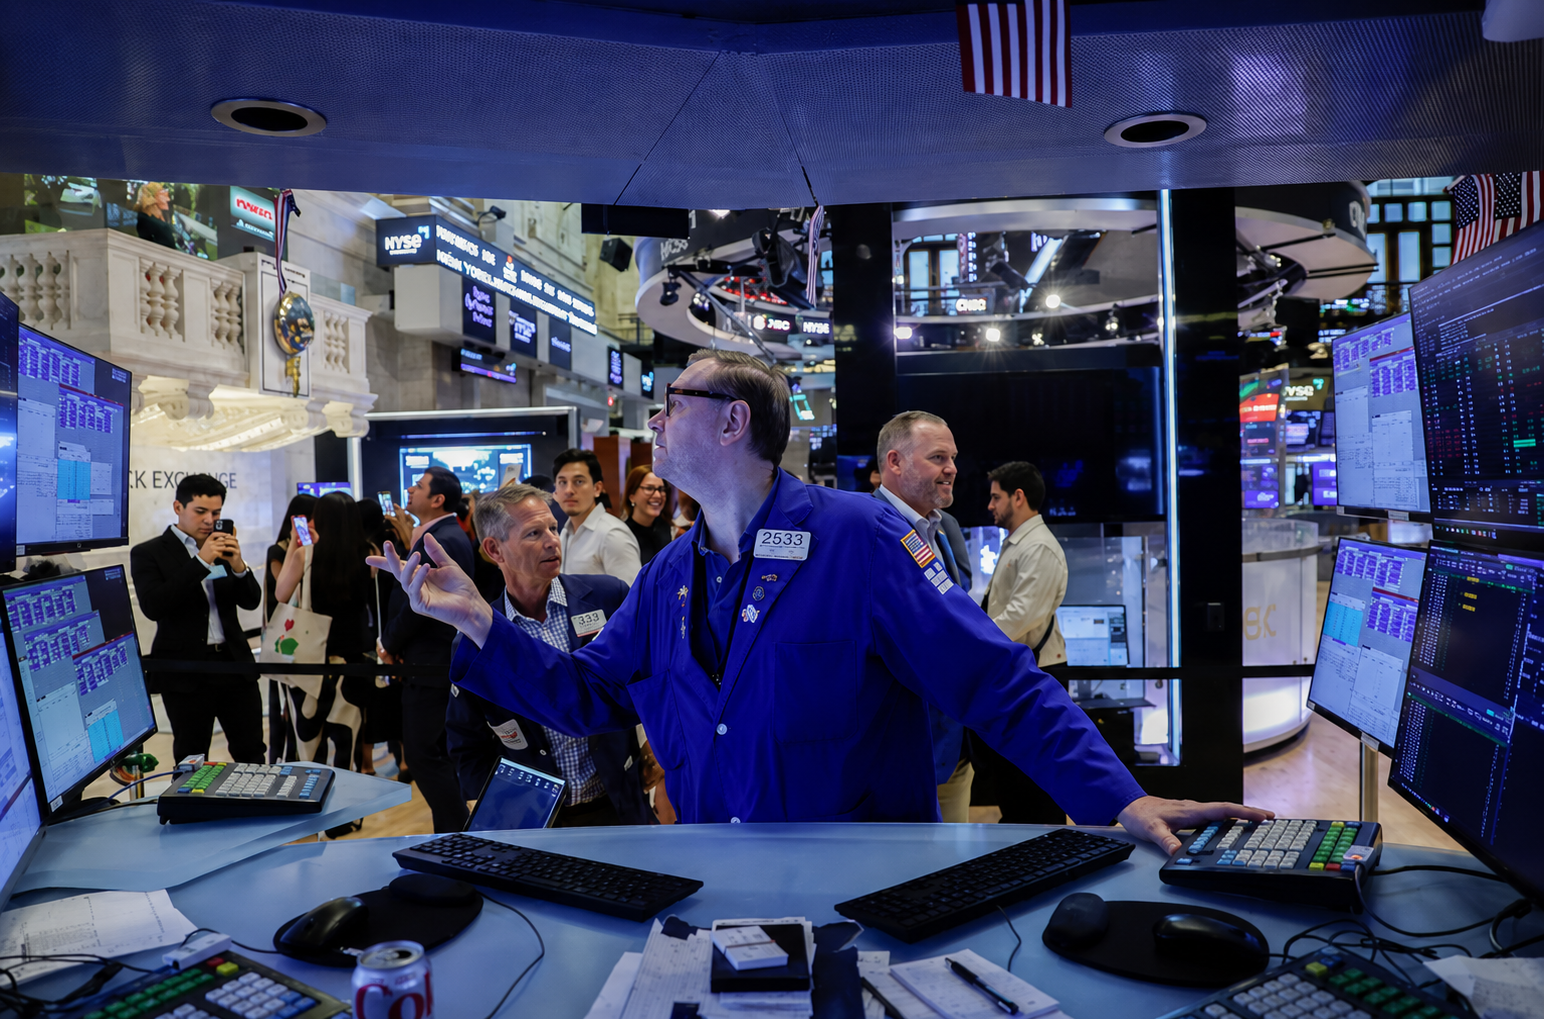
Wall Street’s hottest trade has gone ice cold.
For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron Technology, Nvidia, Advanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.
The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.
Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.
“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.
Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.
Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.
Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.
“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.
Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.
“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”
Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.
Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”
The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.
The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.
These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.
Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.
The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.
Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.
Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.
And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.
“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”
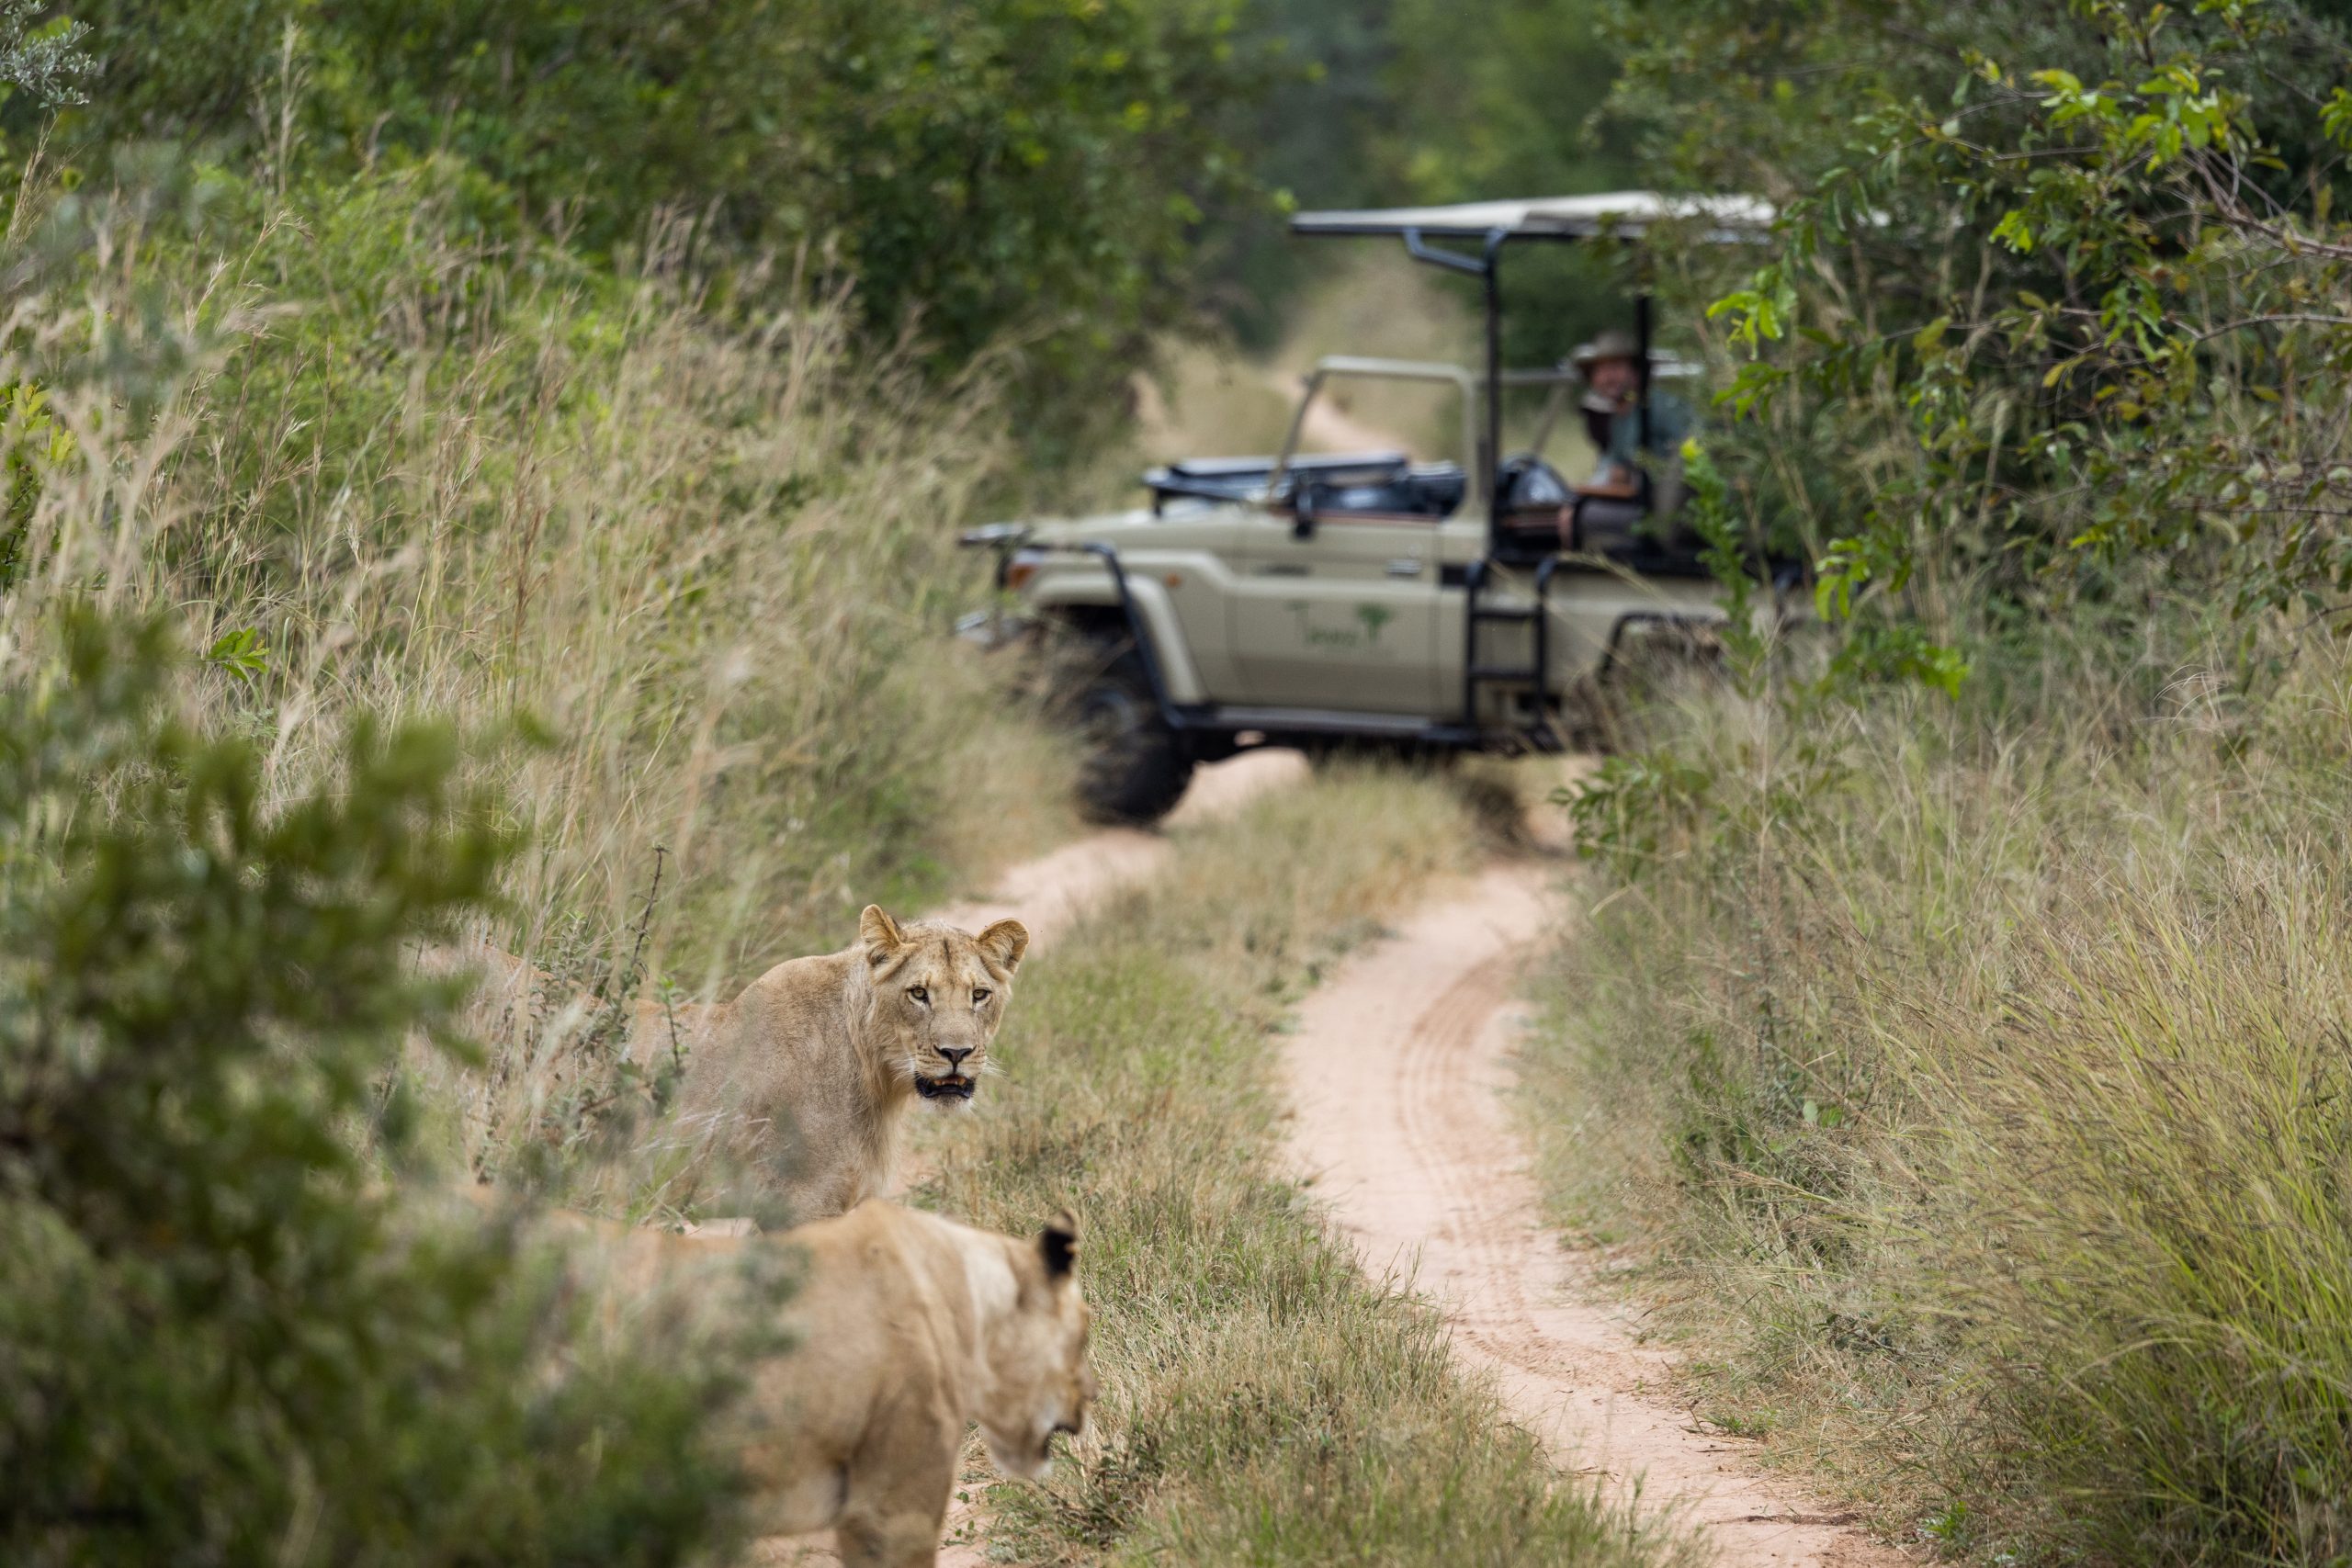
Exclusive eco-conscious lodges are attracting wealthy travellers seeking immersive experiences that prioritise conservation, community and restraint over excess.
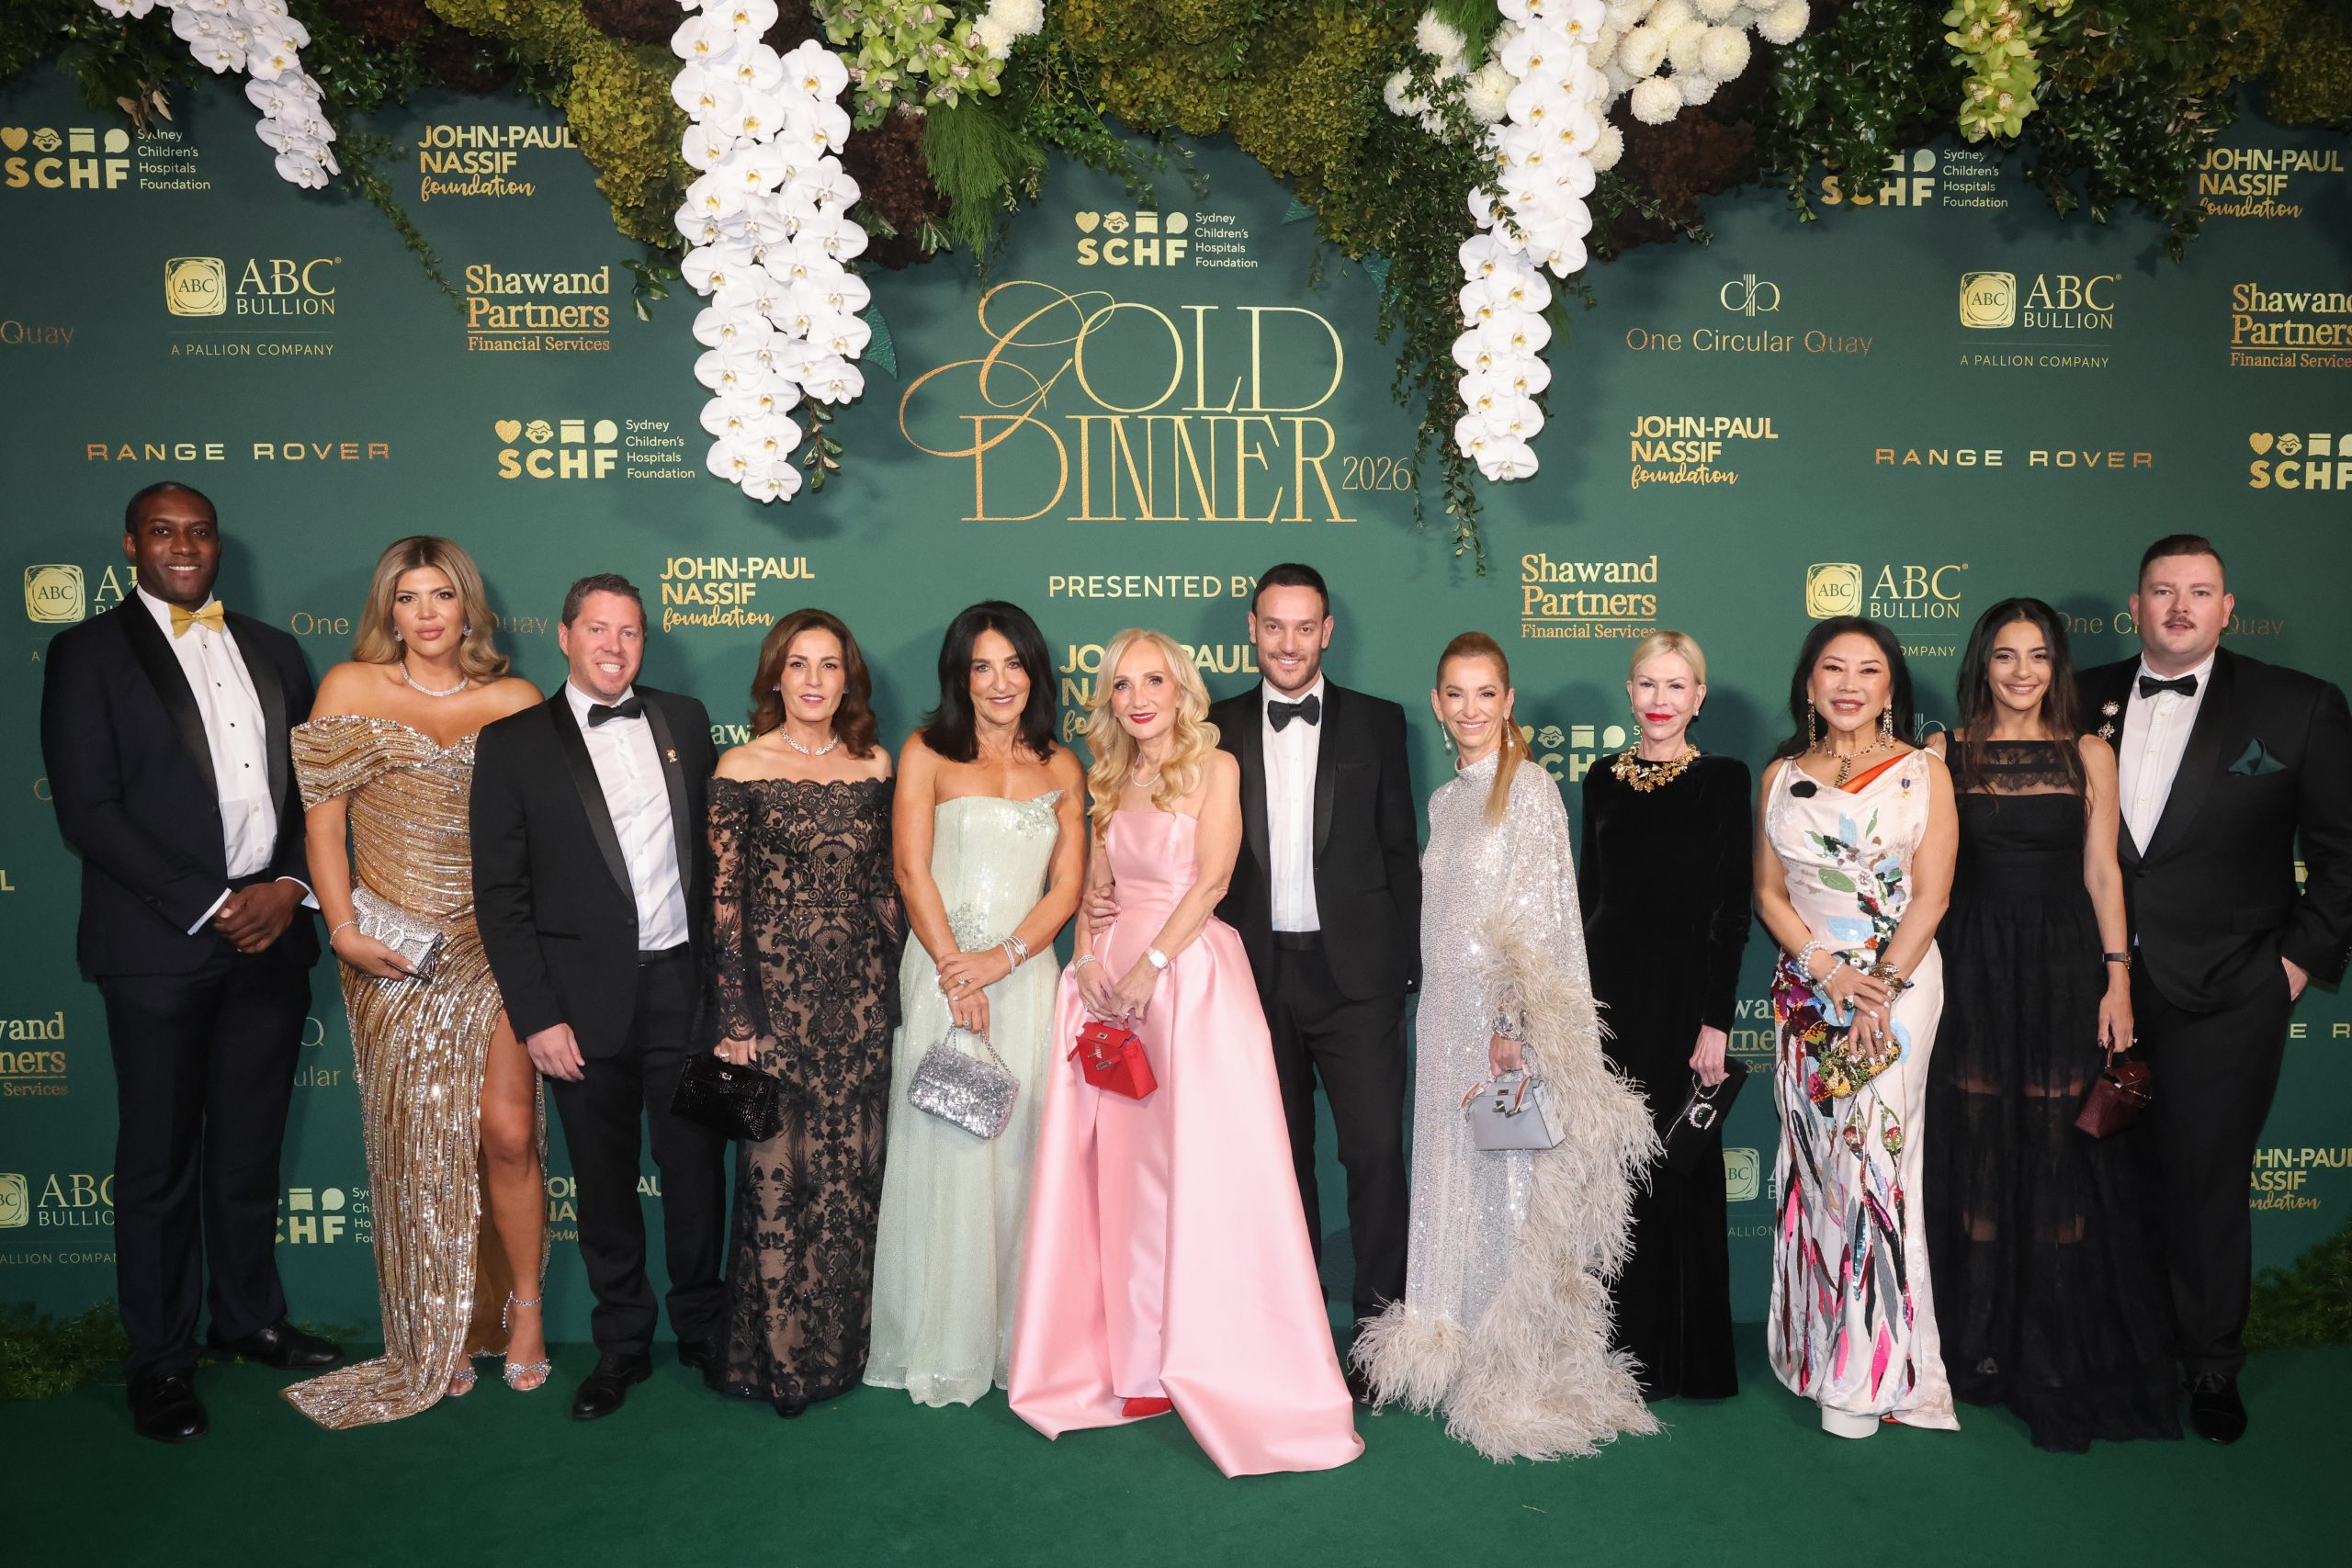
Sydney Children’s Hospitals Foundation CEO Kristina Keneally says Australia’s culture of large-scale philanthropy is becoming more sophisticated as Gold Dinner raises $75.5 million for children’s health, research and innovation.