Mass Layoffs or Hiring Boom? What’s Actually Happening in the Jobs Market
Restaurants, hotels and hospitals are finally staffing up, more than making up for losses in tech and other sectors

 7 min
Interest rates are rising, inflation is elevated and recession fears linger. Despite all that, employers keep hiring.
The U.S. added 1.1 million jobs over the past three months and ramped up hiring in January. That appears puzzling, given last year’s economic cool down, signs that consumers are pulling back on spending as their savings dwindle, and a stream of corporate layoff announcements, particularly in technology.
Driving the jobs boom are large but often overlooked sectors of the economy. Restaurants, hospitals, nursing homes and child-care centres are finally staffing up as they enter the last stage of the pandemic recovery. Those new jobs are more than offsetting cuts announced by huge employers such as Amazon.com Inc. and Microsoft Corp.
Employers in healthcare, education, leisure and hospitality and other services such as dry cleaning and automotive repair account for about 36% of all private-sector payrolls. Together, those service industries added 1.19 million jobs over the past six months, accounting for 63% of all private-sector job gains during that time, up from 47% in the preceding year and a half.
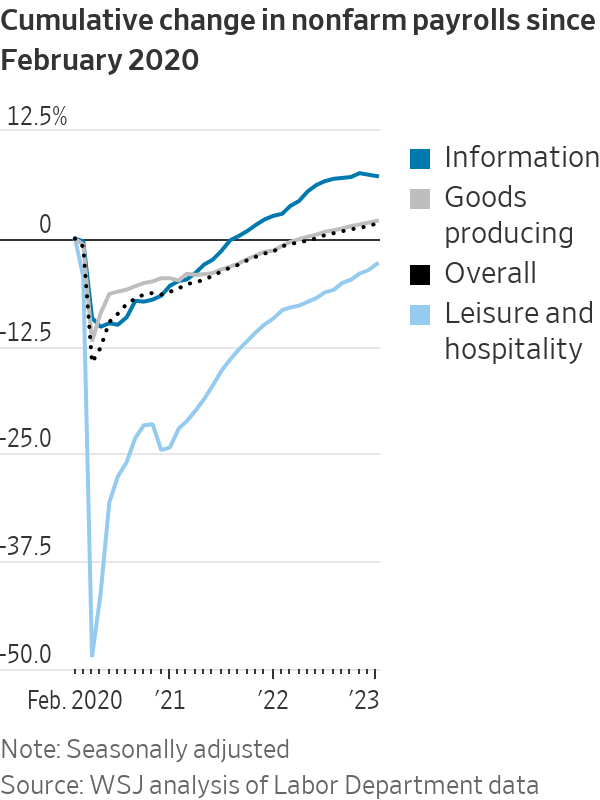
By comparison, the tech-heavy information sector, which shed jobs for two straight months, makes up 2% of all private-sector jobs.
The hiring spree in everyday services shows that the sectors hardest hit in the pandemic’s first months, when 22 million jobs were lost, are continuing to recover. Those gains may prop up the broader economy enough to avoid a recession.
The sectors driving job growth include hotels, hospitals and restaurants, which laid off workers amid pandemic shutdowns and social distancing in 2020. After demand surged during re openings, they started hiring again. But they struggled to land enough new employees and retain existing ones.
Burned out workers quit, finding ample opportunities elsewhere. Job seekers chose other positions that were less physically demanding or allowed them to work from home. Many Americans remained out of the labor force, some worried about illness, some supported by federal benefits and others opting to retire early.
Now, with the effects of the pandemic diminishing, many executives and business owners in services industries say they are finding it easier to recruit and fill jobs.
Eliot McDonald, director of operations at Layne’s Chicken Fingers, said the Texas-based restaurant chain’s four company-owned locations each received about one job application every two weeks between early 2021 and mid-2022. Many employees worked for just a month before quitting. Without enough hourly workers, Mr. McDonald himself would often run the drive-through, prepare chicken fingers and plate food.
In the second half of last year, he said, more job candidates started applying, which he attributed in part to the lure of higher wages. The company’s average hourly wages have risen to $15, from $11 two years ago. Now, all company-owned stores are fully staffed, and Mr. McDonald no longer is helping with hourly worker shifts.
“Knock on wood, things are running like they were before the pandemic,” he said.
In January alone, restaurants and bars added a seasonally adjusted 99,000 jobs. The healthcare industry grew by 58,000, and retailers added 30,000 jobs as fewer holiday-season workers were let go than in past years.
The recovery from pandemic-driven job losses likely will continue to drive employment growth this year, said Robert Frick, corporate economist with Navy Federal Credit Union in Vienna, Va., pointing to healthcare employers, nursing homes and child-care centres. “These industries absolutely have to hire, and they will keep scouring the labor force, raising wages and using different programs to get people back,” he said.
January’s jobs report showed employers added 517,000 jobs—nearly triple what economists had estimated—and the unemployment rate fell to 3.4%, the lowest in more than 53 years. The stronger-than-expected report prompted some forecasters to re-evaluate their views. Goldman Sachs economists reduced the likelihood that the U.S. will enter a recession in the next 12 months to 25%, from 35%, citing the strength of the labour market.
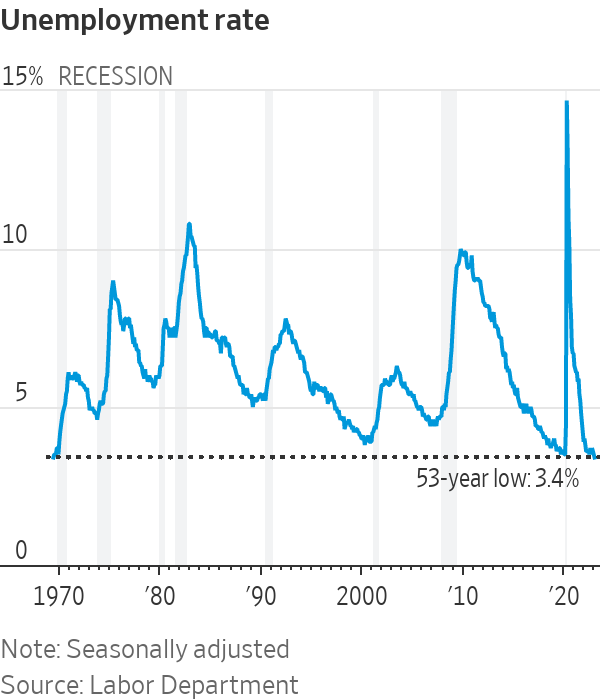
The jobs report was “certainly strong—stronger than anyone I know expected,” Federal Reserve Chair Jerome Powell said Tuesday. “It kind of shows you why we think [reducing inflation] will be a process that takes a significant period of time.”
Heading into 2023, forecasters expected the economy to slow and the labor market to deteriorate in the face of higher interest rates stemming from the Fed’s campaign to control inflation. The central bank raised its benchmark interest rate by a quarter percentage point earlier this month, to a range of 4.5% to 4.75%, a level last reached in 2007.
In December, Fed officials projected that the unemployment rate would rise to 4.6% by the end of this year. Economists surveyed by The Wall Street Journal in January put the probability of a recession in the next 12 months at 61%. They expected U.S. payrolls to decline by 7,000 a month on average this year. It remains possible that a combination of rising interest rates, persistent inflation and slowing consumer spending could tip the U.S. into recession.
But the most recent labor data is consistent with a jobs market coming back into balance after pandemic disruptions, rather than one that is wobbling into a sharp downturn. Wage growth is strong, but slowing, with hourly wages in lower-paying service jobs advancing more rapidly than the private-sector average. Layoffs, outside of a few sectors, remain historically low.
Restaurant chain Chipotle Mexican Grill Inc. is now above pre pandemic staffing levels, with turnover rates down. National hospital company HCA Healthcare Inc., which struggled with nursing shortages during the pandemic, is increasing hiring. The nation’s largest private employer, Walmart Inc., is raising wages for U.S. workers to at least $14 an hour, from $12, closing the gap with rivals that pay more.
Business owners, executives and economists say there are several reasons more workers are searching for jobs: bigger pay checks and benefits, diminishing fear of getting sick, and financial worries amid high inflation. The result is that employers, including small-business owners, are finding it easier to fill jobs.
With Covid-19 cases down, fewer workers are concerned about getting or spreading Covid than in the previous two winters when the virus surged. That might be boosting searches for jobs that require close personal contact, such as restaurant server, cafeteria worker and hairdresser. Job seekers also are less likely to be sick with or caring for someone sick with Covid, according to the U.S. Census Bureau.
Hiring in the healthcare services sector, including by hospitals, outpatient centres and nursing homes, has provided a boost to overall jobs numbers because the sector accounts for 16% of all private-sector payrolls.
Healthcare payrolls have grown at a robust pace in recent months as more candidates step forward to meet demand. Job applications for healthcare positions on recruiting platform iCIMS rose 7% from January 2022 through December, while they declined in industries such as manufacturing, finance and technology.
The Houston Methodist hospital system, which employs about 30,000, is finding it easier to fill clinical jobs such as in nursing, said Chief Executive Marc L. Boom. “It is less challenging to hire than it was a year ago,” he said. “We had a significant shortage of staff, in particular registered nurses, radiology technicians and many other clinical, patient-facing roles. But fortunately it’s gotten better.” The hospital made 7,560 external hires in 2022, up from 7,096 in 2021.
As hiring gets easier, the hospital system has stepped back from offering signing bonuses, including $10,000 bonuses for emergency-room nurses who could do evening shifts and for certified respiratory care technicians. The company also is relying less on temporary-staffing agencies than it did in 2020 and 2021.
Still, the system has about 3,000 open jobs to fill, which Dr. Boom said is high.
Hospitals employ many doctors, nurses and specialised technicians, who often earn high salaries. Other corners of the healthcare industry, where pay is lower, are still searching for workers.
Nursing homes are starting to add workers, but have struggled to staff up after shedding employees earlier in the pandemic. Staffers have quit—and stayed away—because of the pay, burnout and fear of Covid. Enhanced unemployment benefits and competing job opportunities also played a role. Nursing homes aren’t expected to return to pre pandemic staffing levels until 2027, according to a January long-term-care jobs report produced by the American Health Care Association and the National Center for Assisted Living.
Covid-19 drove women out of the workforce at higher rates than men early in the pandemic. Factors including access to child care, virtual schooling, a lack of attractive jobs and health concerns impeded the recovery of female labor-force participation.
More women are flowing back into the labor force, which could help service-sector employers fill positions that traditionally have been held by women. Labor-force participation for women in their prime working years of 25 to 54 returned to pre pandemic levels in January.
Employment in leisure and hospitality, which fell sharply early in the pandemic when restaurants, bars and hotels shut down, also is bouncing back, although it hasn’t yet reached pre pandemic levels.
Since restaurants and hotels haven’t staffed up too much, they could avoid the fate of many tech companies that are laying off workers after over hiring earlier in the pandemic, said Betsey Stevenson, an economist at the University of Michigan who was an economic adviser to President Barack Obama.
Restaurateur Itai Ben Eli, chief executive of Sof Hospitality, which runs Doris Metropolitan steakhouses in Houston and New Orleans and Israeli restaurant Hamsa and Badolina Bakery & Cafe in Houston, said it has become much easier to hire in the past three to four months.
“It’s nothing compared to about 18 months or 24 months ago, when it was almost impossible to hire people,” he said. “We’re definitely seeing a renaissance in terms of people…coming back to the industry.”
He has noticed more applicants for positions such as manager, chef and sous chef, positions that once took him months to fill. Now he is filling them more quickly, without dangling signing bonuses of $1,000 to be paid out after three months.
One steakhouse recently aiming to hire a sous chef, Mr. Ben Eli said, had “too many great candidates, which is a situation that I don’t remember in the past five years happening.”
“We had a tough call deciding who’s going to get the position,” he said. “I wish I had more positions available.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
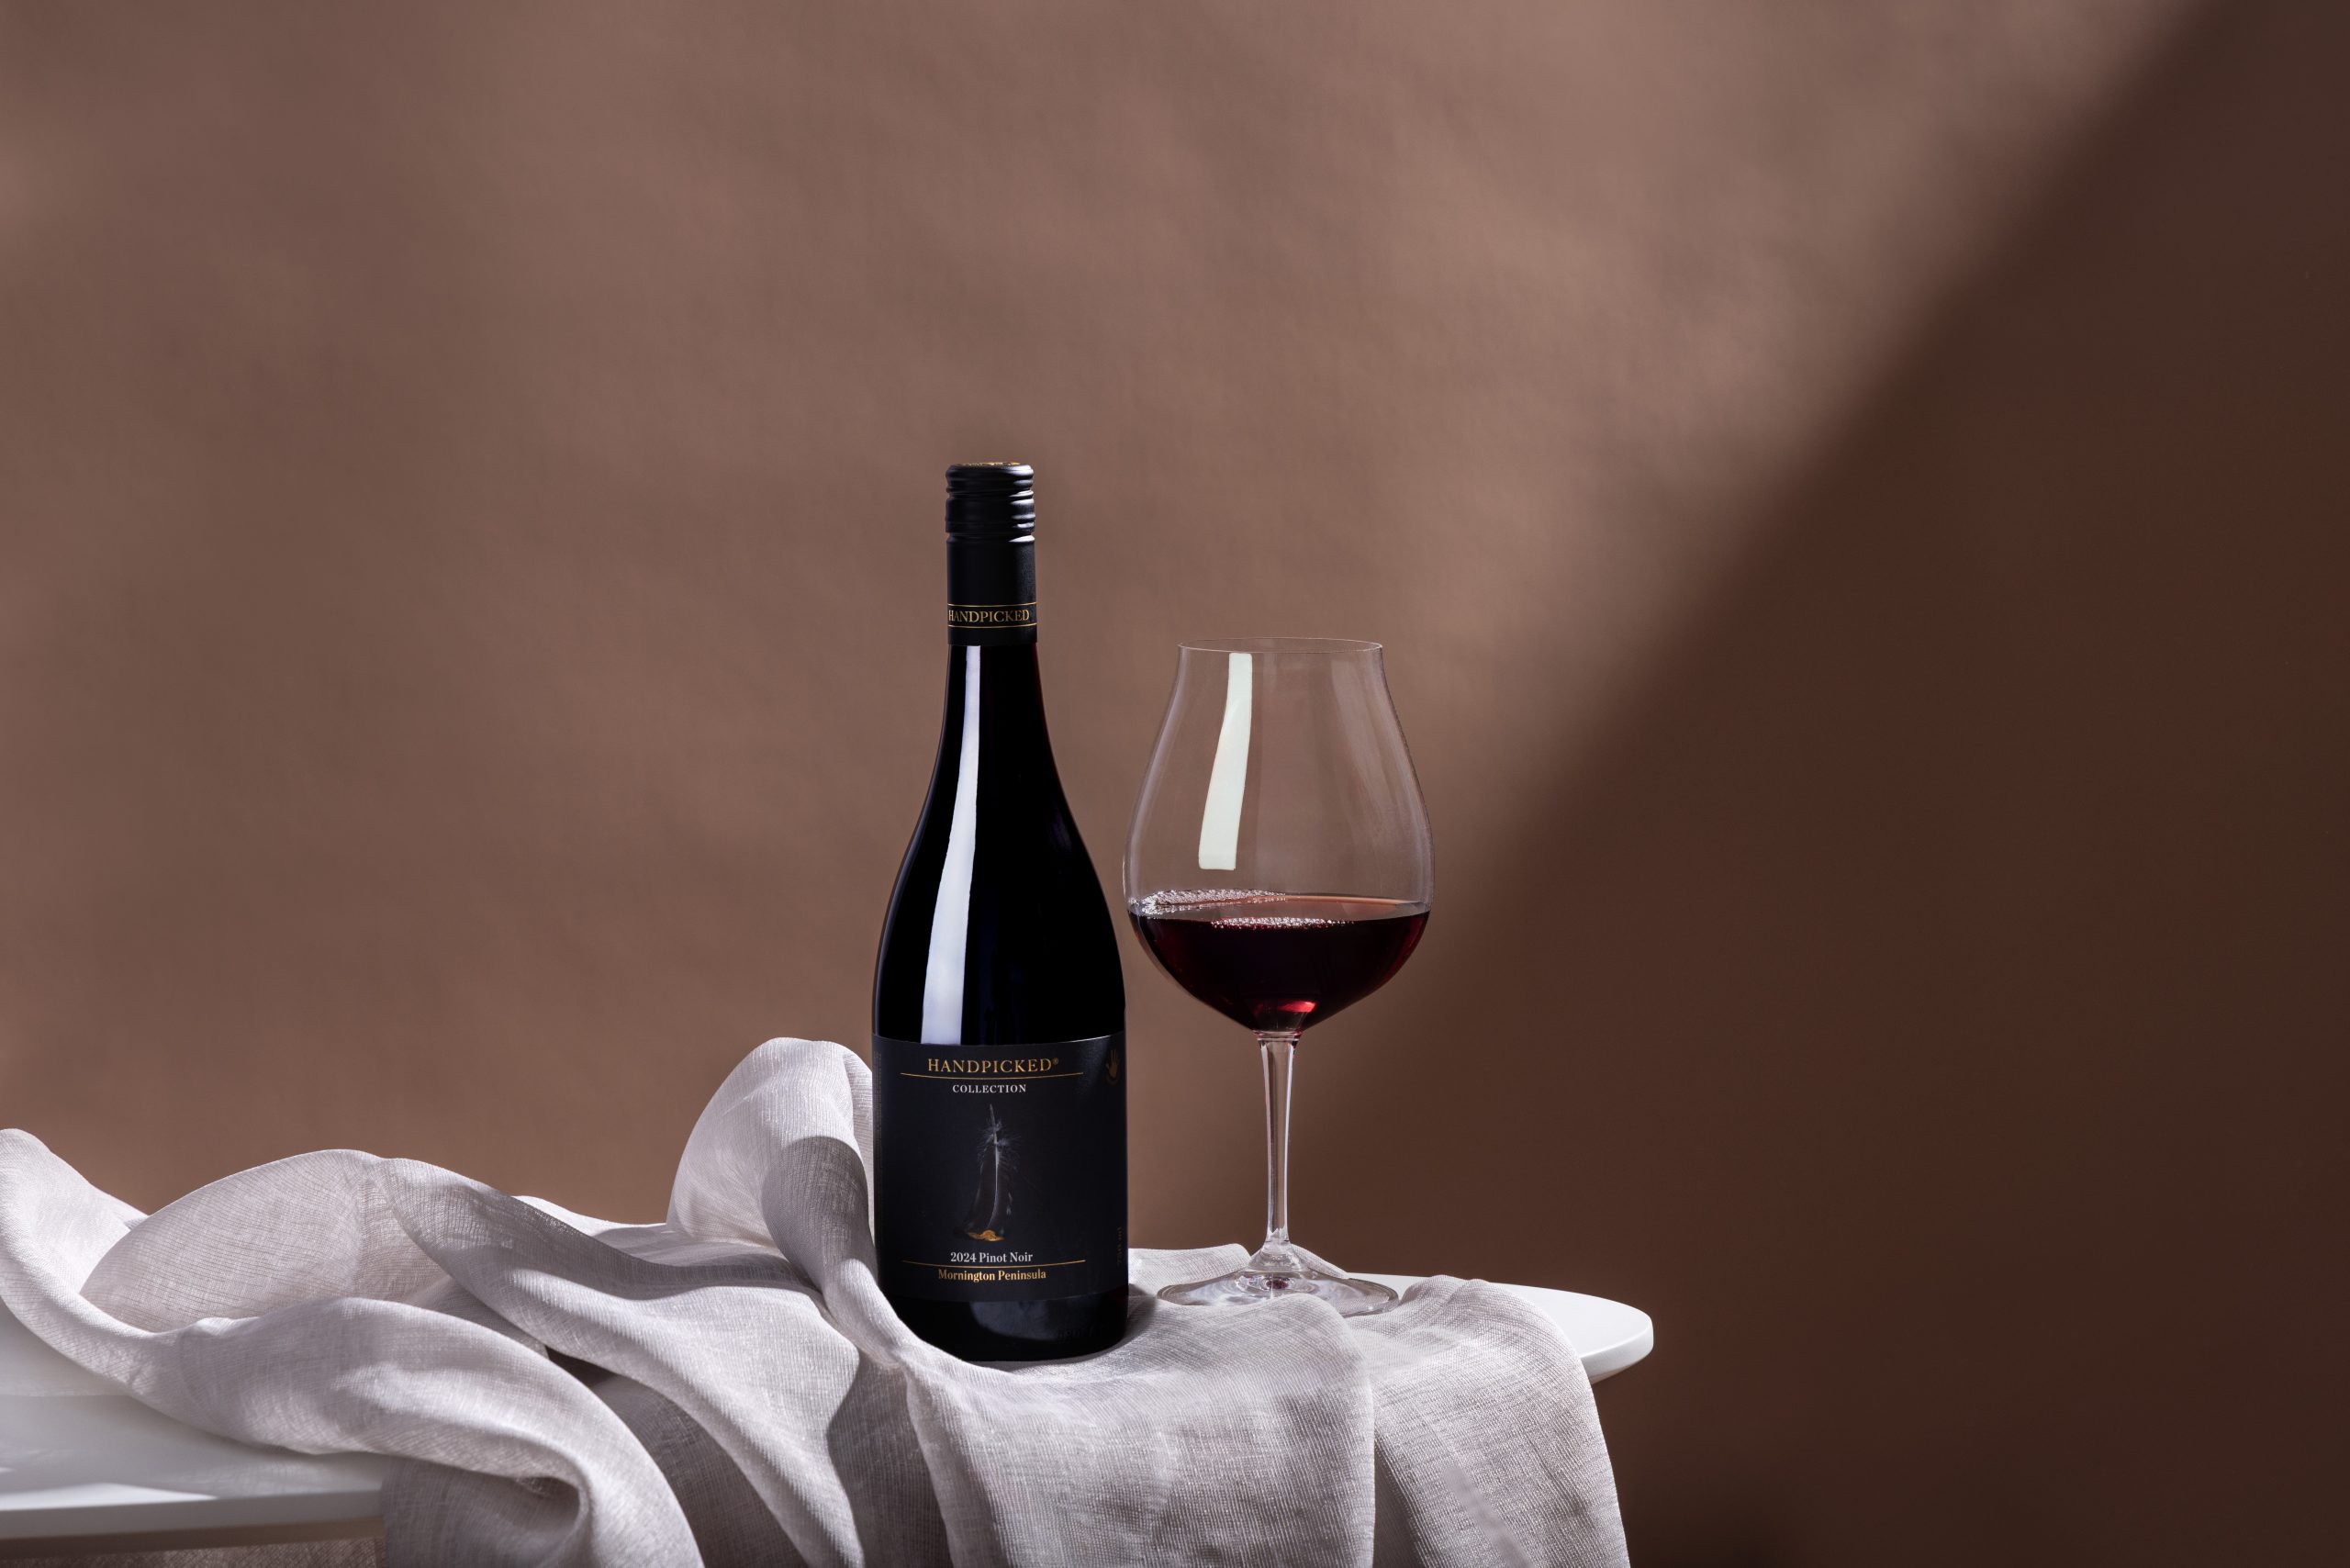
As the season turns, Handpicked Wines’ latest Pinot Noir and Chardonnay releases reveal how subtle shifts in place shape what ends up in the glass.
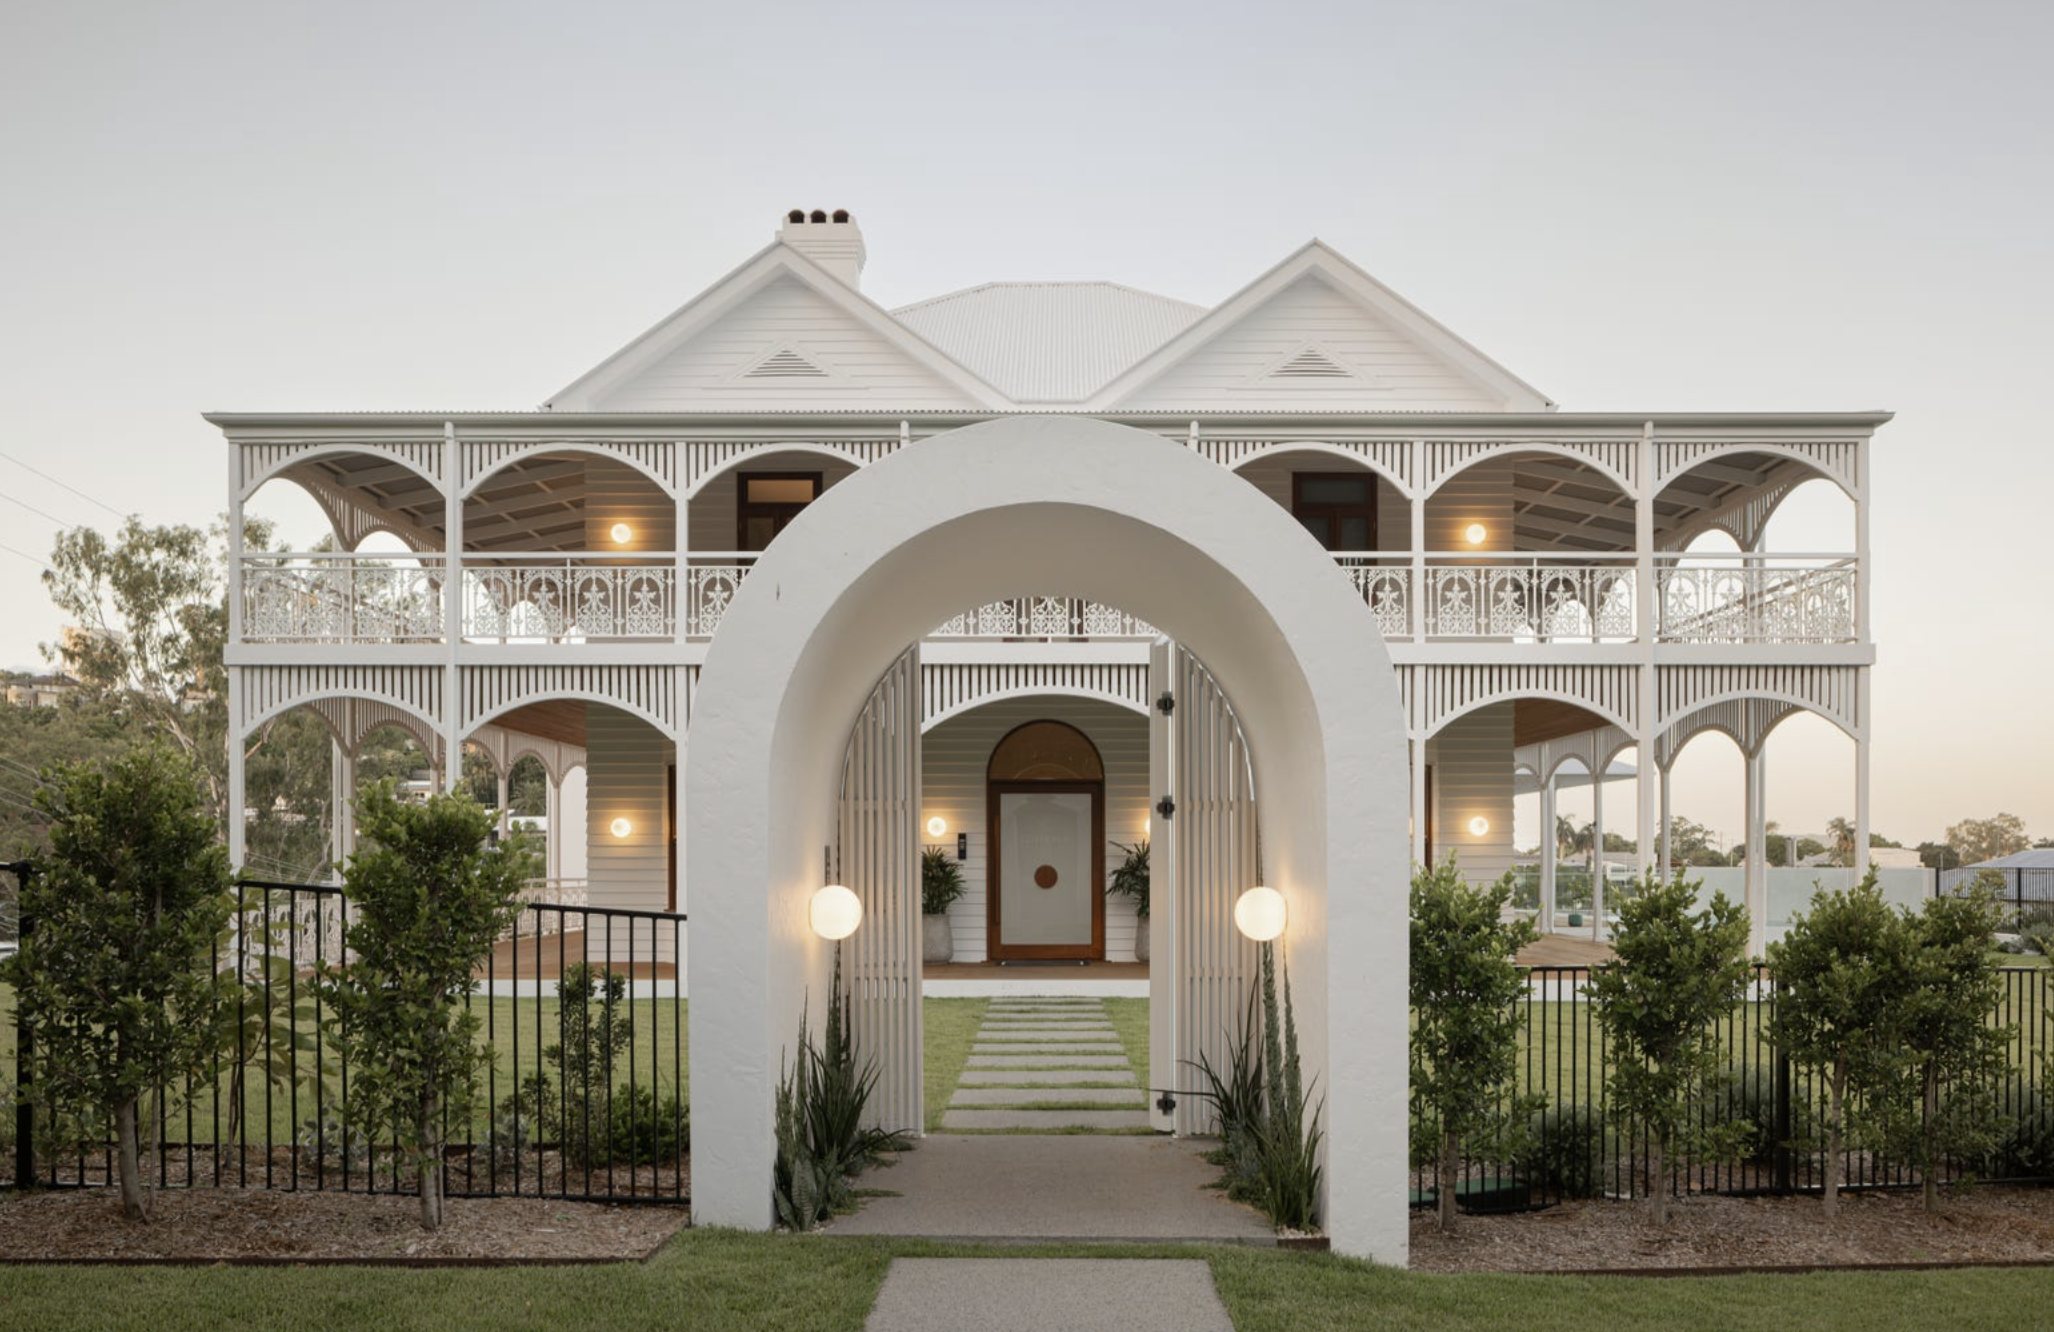
A restored 1860s Brisbane residence transformed by GRAYA has smashed Paddington’s house price record, selling for more than $12 million.