New Year’s Resolutions Financial Advisors Wish Clients Would Make

 5 min
Every financial advisor knows the feeling of having their good advice ignored. Clients splurge when they shouldn’t, play it safe in retirement when they can afford to spend more, and just won’t update those darned beneficiary designations. But what if advisors could create New Year’s resolutions for their clients? Granted resolutions and follow-through are two different matters, but for this week’s Barron’s Advisor Big Q, we invited five advisors to create resolutions for their clients. Here’s how they responded.
Craig Robson, founding principal, managing director, Regent Peak Wealth Advisors
Create or pursue your own stretch goals. Those could be financial, personal, or relational. We always bucket aspirational goals in our clients’ plans, and I will periodically remind them and ask, “What is preventing you from pursuing those goals?” Another way to say it is, “If not now, when?” Examples could be building your dream home, starting a business, going for that C-suite job opportunity.
The second resolution is to take chances. Make yourself available for some new opportunities. For me, the pandemic was a huge reminder of this. We started our firm eight months before the pandemic started. In the summer of 2020, I decided to negotiate a five-year contract for brand-new office space. When everybody was leaving and parking lots were empty, we were going back in. We negotiated fantastic financial terms and got great new fresh office space in Atlanta. Obviously, think it through and be educated, but there’s nothing wrong with taking some chances.
Emily Millsap, manager, financial planning, Avantax Wealth Management
Take thetime to learn your generational wealth story. So many of our beliefs about money and financial behaviours are tied to what we’ve learned and observed from our family and our culture and our community. And we always try to make money about math and logic, but there’s a lot of emotion tied into why we make the financial decisions we do. Understanding how our current behaviours and beliefs are connected to the stories of those who came before us, and then passing those stories to the next generation, is such a powerful and healing thing.
There are a few books out there that I really like on this topic. Loaded: Money, Psychology, and How to Get Ahead without Leaving Your Values Behind touches on some of that. Anything by Dr. Brad Klontz; Mind over Money: Overcoming the Money Disorders That Threaten Our Financial Health is a great one. Those are good places to start, and then talking to your parents, grandparents, aunts, uncles, about what they remember, what they learned, how they felt about money.
If you really want to do a deep dive, you can build a genogram, which is like a family tree, but you outline levels of education and career and how ancestors behaved with money and what they thought about money. Another resolution is that anyone who carries anxiety about their financial future will seek out experts who can help calm their fears and make a plan.
Dane Burkholder, private wealth advisor, Ameriprise Financial
New Year’s resolution No. 1 is to update your financial plan. People spend so much time focusing on markets and investments and rates of return. But the beginning of the year is a really great time to step back and say, “What are my financial goals, and am I on track for those financial goals?” No. 2 is doing a 401(k) audit. That could be as simple as rebalancing the assets inside of the 401(k) or setting the account to automatically rebalance throughout the year. If you were fortunate enough to get a raise, increase your contributions.
Resolution No. 3 is looking at your emergency fund. We have a unique opportunity to get a positive return on cash, with money-market accounts and CDs at 5%. People who are sitting on large cash balances have a tremendous opportunity to keep money liquid and available, but earning some interest. No. 4 is managing emotions: There are going to be points where the market pulls back or potentially corrects, but sometimes the best strategy is to take no action. When you use emotion to create action, generally the result isn’t beneficial. If you have a house that’s worth $800,000 and you go on Zillow the next day and it’s worth $700,000, you’re not going to sell your house.
Andrew Crowell, vice chairman, wealth management, D.A. Davidson & Co
The markets moved upward dramatically last year, and it’s very likely that clients’ target allocations are different than their current allocations. Somebody who owned a little Nvidia at the beginning of the year now has 220% more in terms of market weighting. So it’s important to rebalance annually, because you may inadvertently be carrying more risk than you need to or want to.
And if Santa makes a list and checks it twice, we have to do the same with all of our beneficiaries on every retirement account, with our trust documents, and so forth. Things change, relationships change. People die, people divorce, people marry, and the list that may have been valid 12 months ago may not be valid today. So make an annual checkup appointment and look at all the beneficiaries listed on your company 401(k), the IRA rollover from your first job out of college and whatever else.
It’s always helpful to set a budget and prioritise what you are going to be saving for this year and create spending guardrails. Banks and brokerage firms will soon allow you to download spending summaries from the prior year; pie charts breaking out spending by category. It can be eye opening to see, “Wow, I know we ate out a lot, but that restaurant line is a lot bigger than I thought.”
Nicholas Yeomans, president, Yeomans Consulting Group
Start with getting organised. Folks say they have that desire, but when it comes to actually getting organised and lining up all their affairs, to put together their tax documents, their estate-planning documents, their portfolios, their 401(k)s and IRAs, everything’s everywhere. I work with a lot of people who are retired, and as you get older, things unfortunately happen, from incapacity to death. Often, there is one spouse left holding the bag, and now they’re hunting and pecking and trying to find out where everything was. They’re already in a state of emotional distress, and now you’ve compounded that distress. Organising is a gift to the spouse who might end up having to take care of you or make those final decisions after you’re gone.
My second resolution is to communicate with family. Younger generations are more proactive in communicating with their kids, but unfortunately, a lot of folks in that 60- to 85-year-old group tend to do a much poorer job. We’re talking about the organisation of your finances and who is in charge of what. Who’s your trustee, who’s your power of attorney, what are your wishes with your healthcare directive? Is everything in a lockbox in your office? And what were you thinking when you put your will together? Why did Sandy get more than Charlie? [Explanatory] letters are a great idea. However, it’s even more meaningful to bring everyone together every two or three years and give them an update as to what you’re doing and why you’re doing it.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

French luxury-goods giant’s results are a sign that shoppers weren’t splurging on its collections of high-end garments in the run-up to the holiday season.
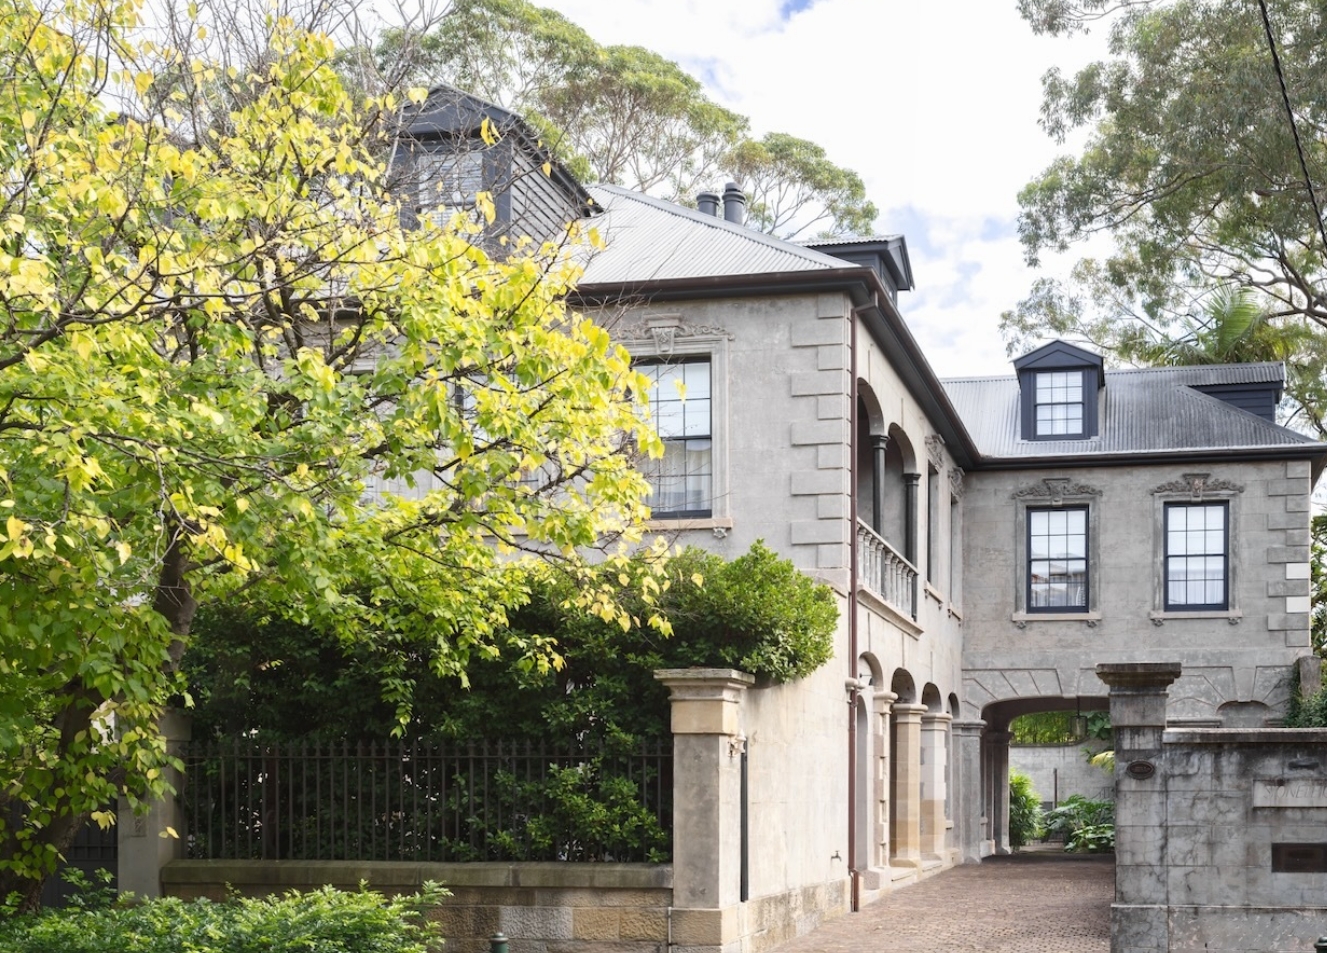
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …