Oktoberfest Now Has Its Culture War. It Isn’t About the Beer.
Traditionalists criticise moves to modernise the Munich celebration as ‘woke’

 4 min
MUNICH—Oktoberfest is usually all about the beer. This year, it is about chicken.
A decision by the Paulaner festival tent to serve all-organic hens at its marquee venue is stoking a debate between advocates of a sustainable Oktoberfest against traditionalists wary of a “Woke Wiesn”—a play on the short form of the name of the Bavarian celebration.
“It’s an experiment,” said Arabella Schörghuber, who runs the Paulaner Festzelt. “It’s more expensive, but the quality is higher. We want to make sure that the animal has a good life. We’ll see what happens.”
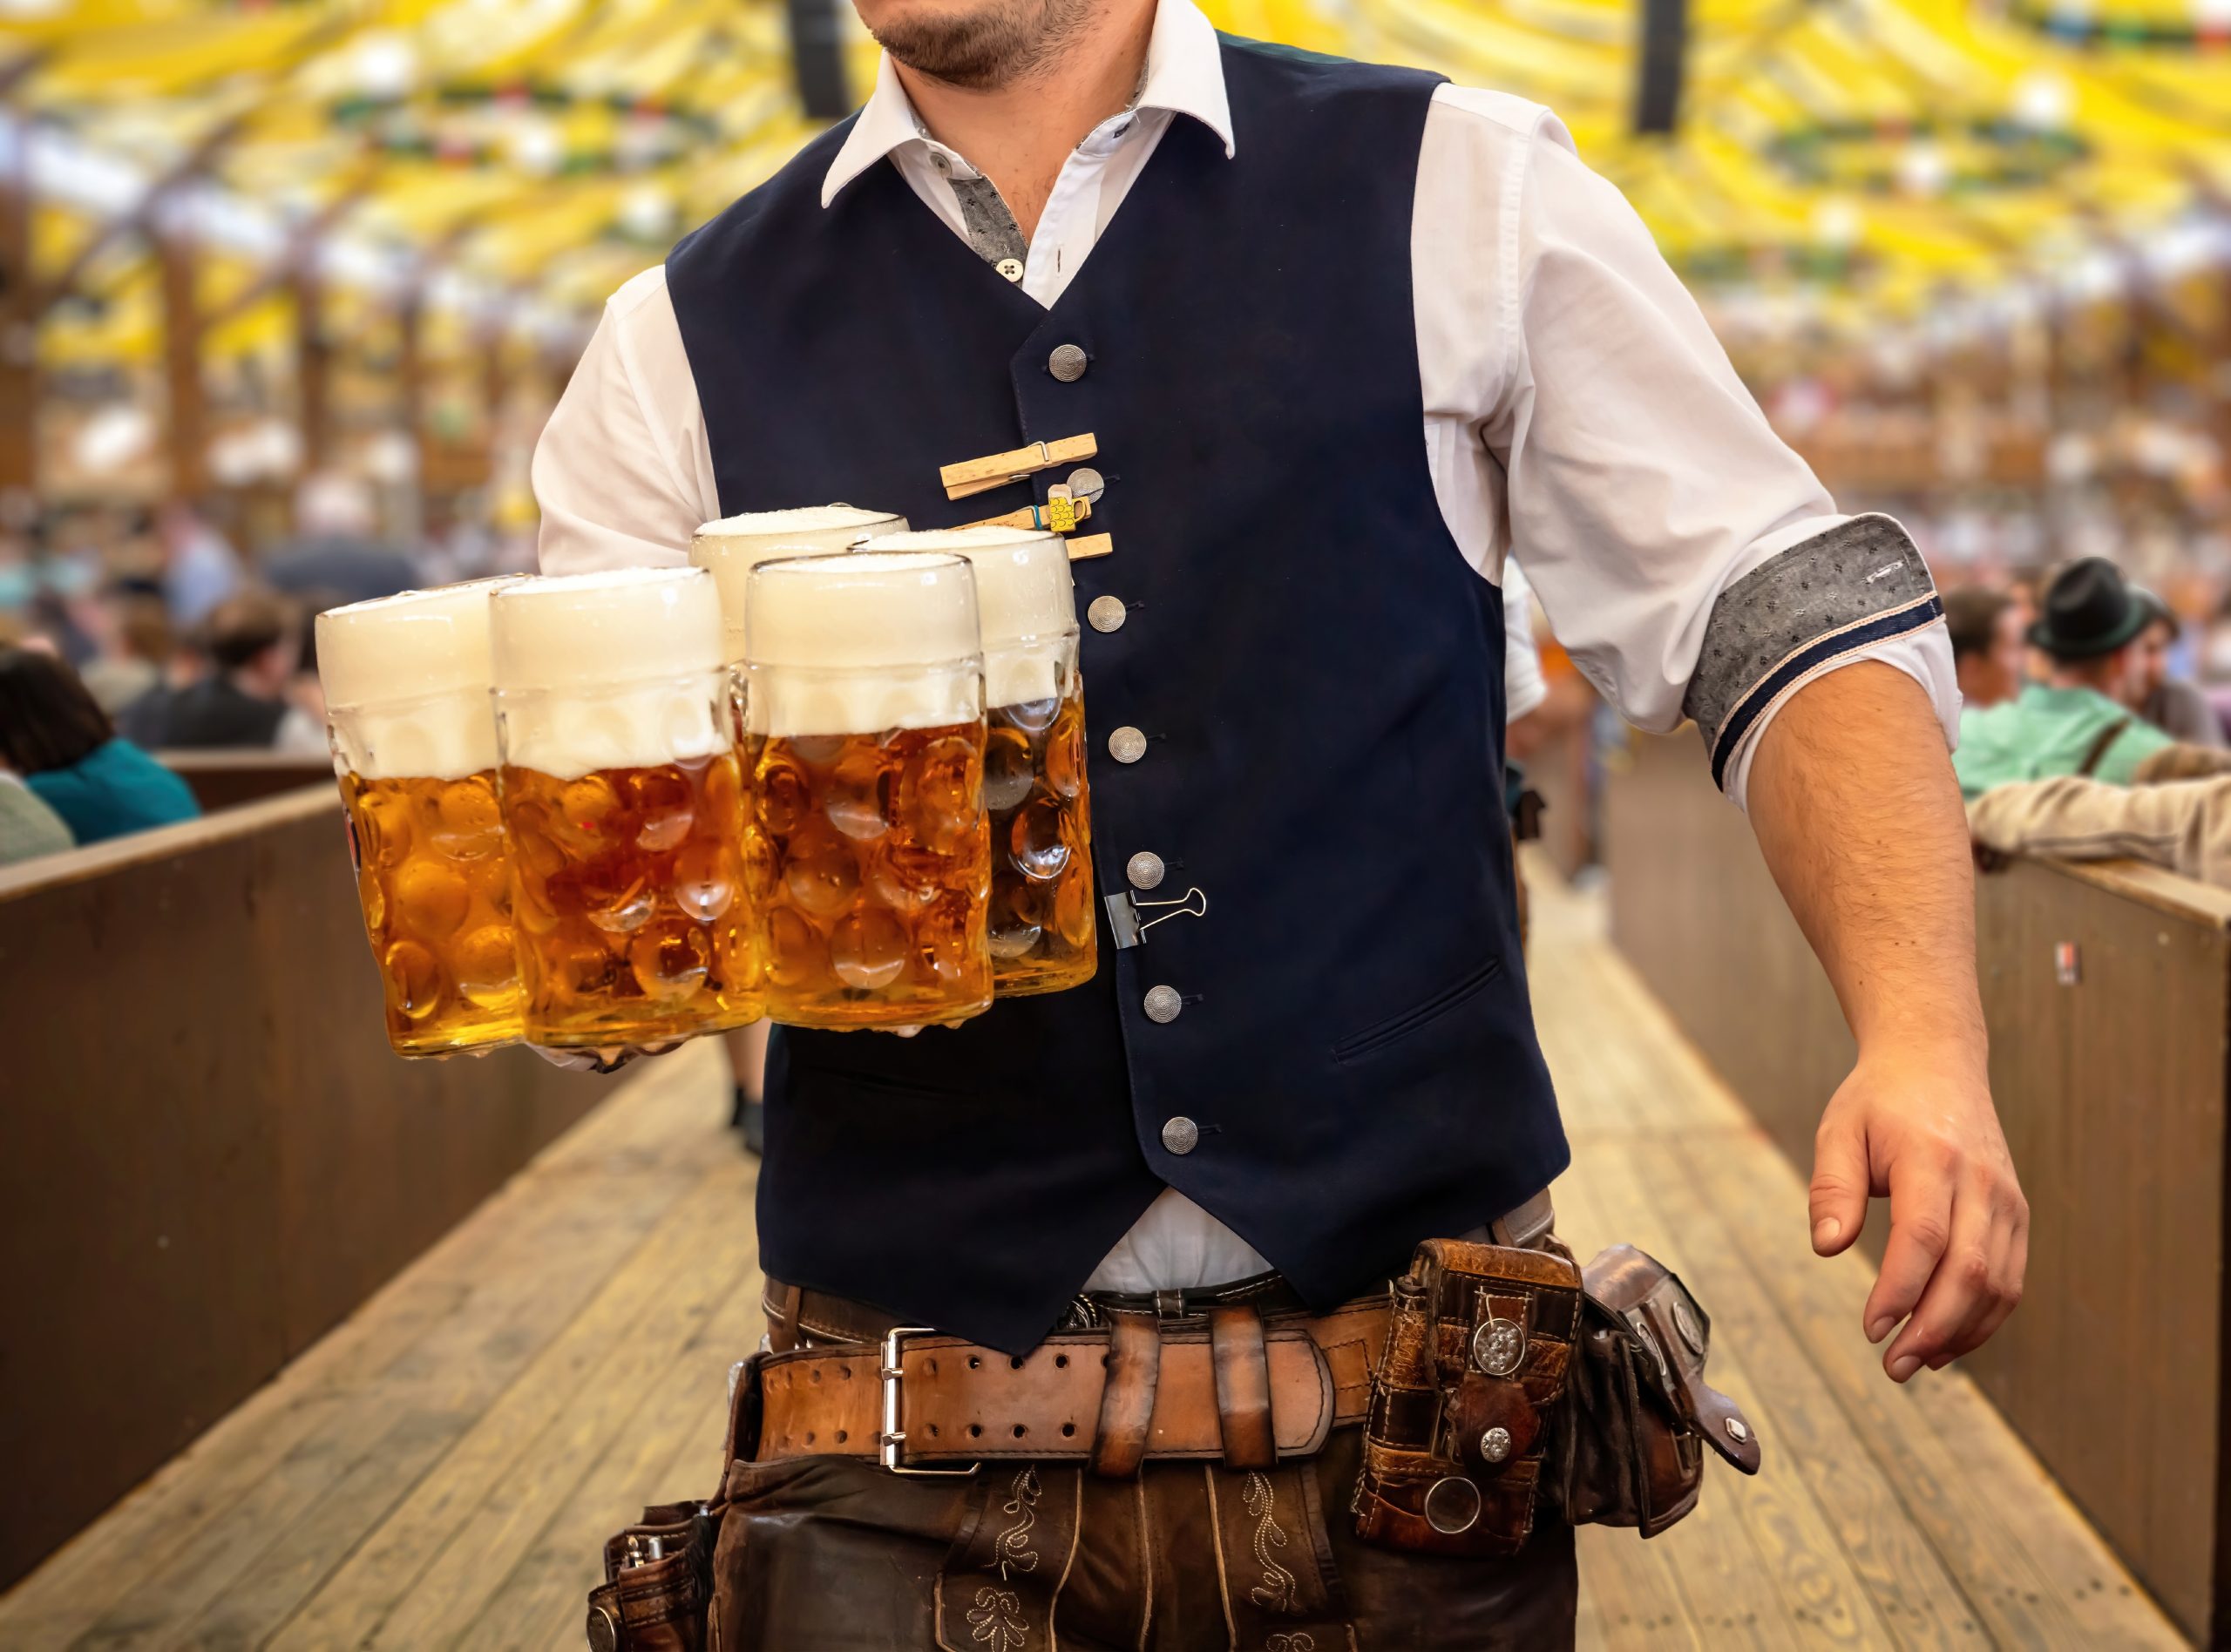
On Saturday, she helped hand out the first beers from the middle of the giant festival tent after thousands of people counted down to the tapping of the first keg. Waiters each toting a dozen glasses with a liter of beer wove through the crowds as huge rotisserie ovens cooked hens in a side kitchen, five on each spit.
Andrea Koerner, 56 years old, comes to Oktoberfest each year and usually orders the chicken, the most popular festival food. Not this time. When she saw that an organic half hen cost 20.50 euros, the equivalent of $22, about 50% more than the nonorganic hens, she opted for pretzels and a cheese spread instead.
“We don’t know the taste because it costs too much to try,” Koerner said.
Other guests said the chicken was good and worth the price. “I don’t care at all,” said Jake Williams, a 32-year-old guest. “I guess it is good if people care about the chickens.”
The price hike is among other inflation-related markups. The cost of a litre—or “mass”—of beer in most big tents increased this year by 6% to €14.50, according to a survey done by the city. That is after prices rose sharply last year following Russia’s invasion of Ukraine. Oktoberfest was canceled in 2020 and 2021 because of the Covid-19 pandemic.
The menu shift follows a pressure campaign by a coalition of groups, demanding that the Bavarian festival of hearty food and enormous beers should turn into a vehicle promoting organic farming.
The activists held a public exhibition in the city’s central square showing a carousel of imitation bloody chicken heads to denounce industrial slaughtering. The group secured a meeting between activists, officials and Oktoberfest tent owners in the spring.
“There’s already a lot going on. But my perspective is from an organic local farming business, and there’s not enough,” said Susanne Kiehl, a board member of the Munich Food Council.
She and Anja Berger, an Oktoberfest official and a Green Party member, said the changes are important to meet the city’s goal of becoming climate-neutral by 2035.
In other matters, Berger’s party this year also secured four free water fountains on the festival grounds.
During a tour of the grounds last week, Mayor Dieter Reiter admired the new taps and joked of what might come next. “A free beer fountain!” he said. “I just haven’t found anyone who will do it yet.”
Activists have sought gastronomic mandates at the festival, but the city has not imposed them. An association of Munich’s innkeepers have pushed back at such rules, saying people should be allowed to live—and eat—as they see fit. “I don’t think anyone really wants a planned economy in which a small group decides what is good for the people and what is not,” said Thomas Geppert, head of the Bavarian Hotel and Restaurant Association.
Schörghuber, who is a vegetarian, said she received a mixed reaction to her chicken initiative from the other tents, with some concerned that they would be pressured to follow suit.
For many visitors, locals and overseas tourists, Oktoberfest is a freewheeling carnival—a chance to let loose and drink (often to excess) beer served by waitresses clad in revealing Dirndl dresses. Many guests also don the traditional Bavarian outfits and tie the ribbon of their aprons on a different side to indicate whether they are single or taken.
“It must stay a traditional volksfest, because otherwise it wouldn’t be attractive,” said Clemens Baumgärtner, an official who oversees the festival and a member of the conservative CSU. “If you talk about being woke on the other 340 days a year, nobody really listens to that. But if you talk about being woke on the Oktoberfest, you get lots of media attention.”
The first Oktoberfest was celebrated in 1810 to commemorate a royal marriage and build support for the budding Bavarian monarchy. It was so popular that it became an annual tradition, adding agricultural displays, vaudeville shows and eventually thrill rides. Despite its name, the festival now mostly takes place in September. Around seven million people are expected to visit the Theresienwiese grounds in Munich during an 18-day run that started Saturday.
“Wiesn will have to change as it has changed always over the decades,” said Lukas Bulka, who started working at an Oktoberfest tent as a teenager and now runs the city’s Beer and Oktoberfest Museum.
The festival already uses electricity generated from renewable sources, Baumgärtner said, and single-use dishes and utensils are banned.
An association of the 15 largest festival tents—which have seats for about 100,000 people—committed to becoming climate-neutral by 2028, mostly through projects that offset their energy use. Four tents, including the Paulaner venue, already meet the targets and built systems to recycle some wastewater.
But when it comes to farming practices, it isn’t feasible to rely on only organic hops and barley for the roughly seven million liters of beer that will be consumed, Schörghuber said. Hofbräu, one of the six Oktoberfest breweries, estimated that the production and transportation of festival beer in 2019 created 66 metric tons of carbon dioxide. Munich has an organic brewery, Haderner, but it doesn’t have one of the coveted slots at the festival.
Schörghuber said she focused on chicken because it is so sought after—the city estimated that around 500,000 chickens were consumed at Oktoberfest in 2019—and a change was feasible. She found a farm in Austria that raised the organic birds for this year’s festival and spent a year speaking with her cooking staff about what changes were needed to grill what are larger than conventional hens.
Kiehl said that while her group was happy with the Paulaner tent’s chicken change, it would be more difficult to convince the public that the brewers should be forced to tweak their recipes.
“That’s not an easy point in Munich,” she said. “That’s almost like religion.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Here’s how they are looking at artificial intelligence, interest rates and economic pressures.
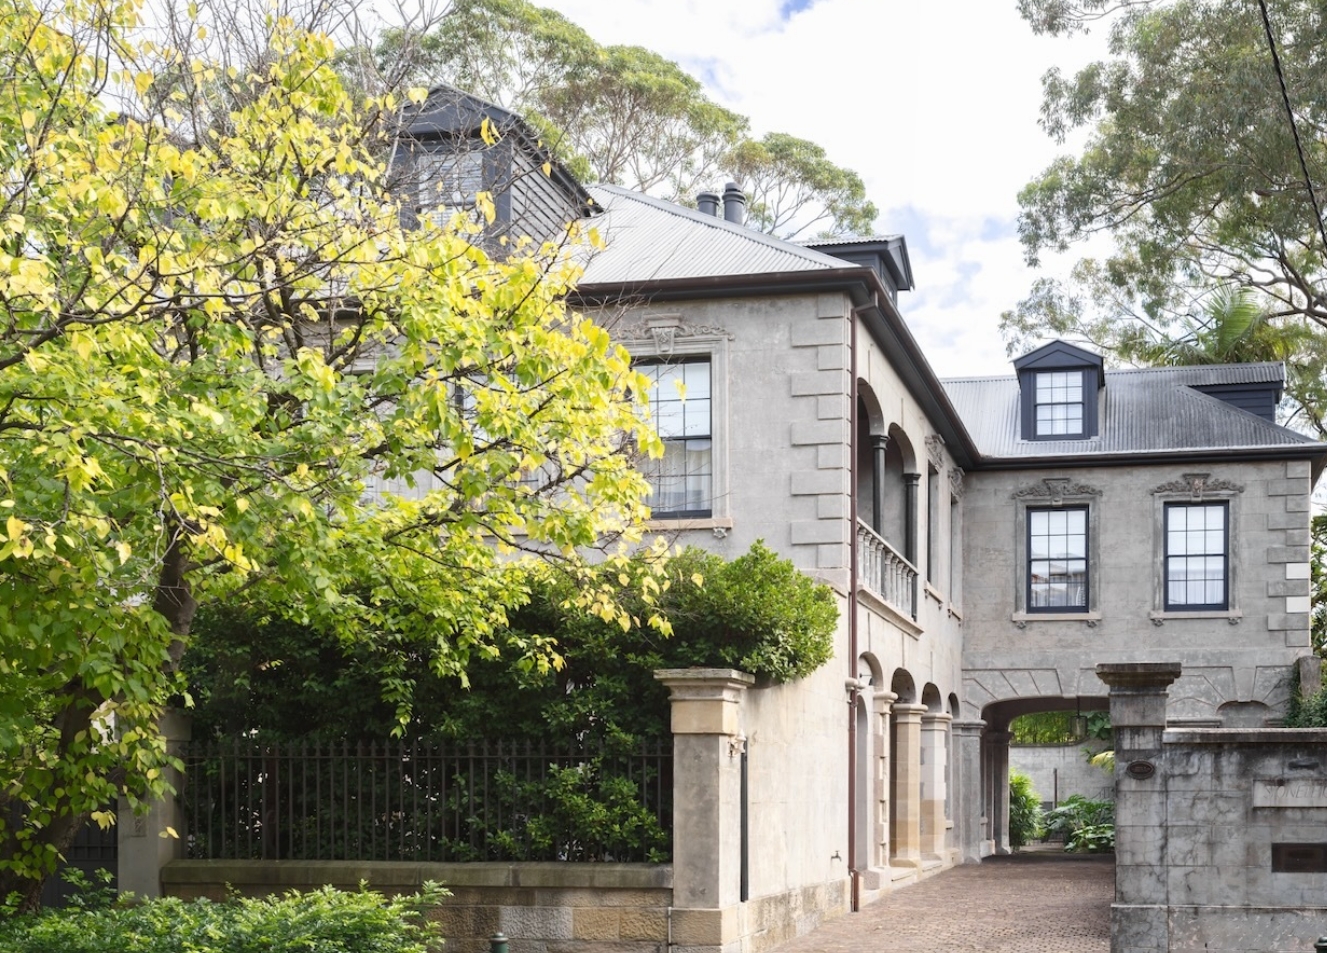
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …