Quit Being a Cynic at Work. It’s Holding You Back.
There are ways to fight the tendency to see the worst in everyone

 4 min
We don’t want to be friends with our co-workers . We don’t want to help out with that project. We don’t trust the CEO…or our boss…or that guy in accounting.
Have we taken our cynicism at work too far?
In some ways, our bad attitude makes sense. Many of us made work our church, only to end up laid off , burned out or underpaid. Now we check out, do less, gossip and snark.
It isn’t getting us anywhere good, according to Jamil Zaki , a Stanford University psychology professor who runs the school’s social neuroscience lab.
“Cynicism, if it were a pill, would really be a poison,” he says.
Zaki has spent years researching sunny concepts such as empathy and compassion. One of his studies, for example, found that giving away money activates a similar part of the brain as eating chocolate. His forthcoming book, “Hope for Cynics,” explores the rise of our darker sides, our belief that other people are selfish, greedy and dishonest.
Betrayed once, we practice what Zaki calls “pre-disappointment,” always assuming others will let us down. The mindset feels productive and cunning, like we’ll be able to protect ourselves. But Zaki says it can actually stunt our careers in the long run, and hurt our mental and physical health.
“By never trusting, cynics never lose,” he writes. “They also never win.”
He assures that you don’t have to become the company cheerleader, or even an optimist, to grow your faith in other people. You do have to take a chance on them, examining your own assumptions and suspending your conviction that you already know how this is going to turn out (not well).
While the approach might initially seem blasphemous to the more negative, sarcastic and skeptical among us—like, say, me—anyone can become less cynical , he says.
You might even find you like it.
How we got here
Once upon a time, Americans were less cynical, Zaki says. A longstanding survey from research organisation NORC at the University of Chicago, which has examined American attitudes since 1972, shows we used to trust each other more. Around the middle of the last century, many hummed along on the rosy glow of plum benefits, robust job security and the knowledge that the chief executive was making, say, 20 times a worker’s pay, instead of 200.
It isn’t that we never complained about work, but Zaki says we repaid our companies’ loyalty with commitment, as part of an unspoken covenant.
Today, that employee-employer pact can feel like a relic of a bygone era. Workers have swapped pensions and equity in their companies for more meagre benefits that put the risk and onus on individuals. Instead of reporting to paternalistic employers, many people now operate under tenuous contracts and gig work.
Some of us work from home in isolation or spend lonely days in the office trapped on back-to-back video calls. There’s less chitchat, less interaction.
“We don’t like people when they’re abstracted,” Zaki says, “but we love people who we actually know.”
Zaki understands why, given all this, we might scoff at the notion that our company is a family, or roll our eyes at the prospect of joining in forced fun at the office happy hour.
Sometimes, I suspect, we also adopt a toughness because we don’t want to look like we’re trying too hard, only to fail or be rejected. Maybe it stems from perfectionism, or anxiety, or insecurity after being exposed to everyone else’s highlight reel on social media for the past 15 years.
Fighting our own worst tendencies
It might seem like all the office snakes are scaling the ladder, but Zaki says studies show cynics’ earnings and leadership potential level off with time. To do good work and attain success, you have to build alliances and share information. Translation: You have to trust someone.
Cynics are prone to poor health, from depression to heart disease, he says, adding that at an organisational level, cynicism can lead to pervasive backstabbing, higher turnover and even corporate corruption.
Cynicism is also a self-fulfilling prophecy, he says. People often mirror how we treat them. Micromanage your team—surveilling them and wresting away their ability to make decisions—and they’ll become the slackers you think they are, doing the bare minimum and buying mouse jigglers to mask time away from their home computers.
“Cynics tell a story full of villains and end up living in it,” he writes.
Resisting cynicism’s pull starts with being open-minded. Examine the data of your life like a scientist would, he says, instead of jumping to conclusions, positive or negative. Think everyone at your job is out for themselves? Ask 10 colleagues for a favour, and see if anyone agrees to help. Convinced every conversation with a co-worker will be painful? Spend a day rating your interactions with them on a scale from 1 to 10.
Challenging your assumptions will leave you pleasantly surprised, Zaki promises, because people often rise to the occasion when we let them. You can start by doling out what you hope to receive. Try engaging in “positive gossip,” speaking highly of others. Take a leap of faith in someone, and do it obviously.
“I trust you,” a manager might say to her direct report. “I really think you can do this.”
Calibrating our hope
Could all this make us too soft? Rejecting cynicism doesn’t mean you can’t hold workers to high standards, Zaki says. Just don’t pit them against each other, with practices like stack rankings, where collaboration is discouraged as workers try to claw above each other on a scoreboard.
Your humour can still be irreverent, even biting, he adds, but jokes should ultimately bring people together or improve something.
“Snark, in the absence of any hope, kind of curdles,” he says.
And don’t be blindly optimistic, he adds. If leadership isn’t giving you any reason to have faith in them, don’t. Find another group to trust—maybe your small team or a union. Band together to provide a buffer to the daily stress of working in your organisation, or enact change by fighting for something better.
“We often underestimate how much influence we have,” he says. “Own that power.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Micro-needling promises glow and firmness, but timing can make all the difference.
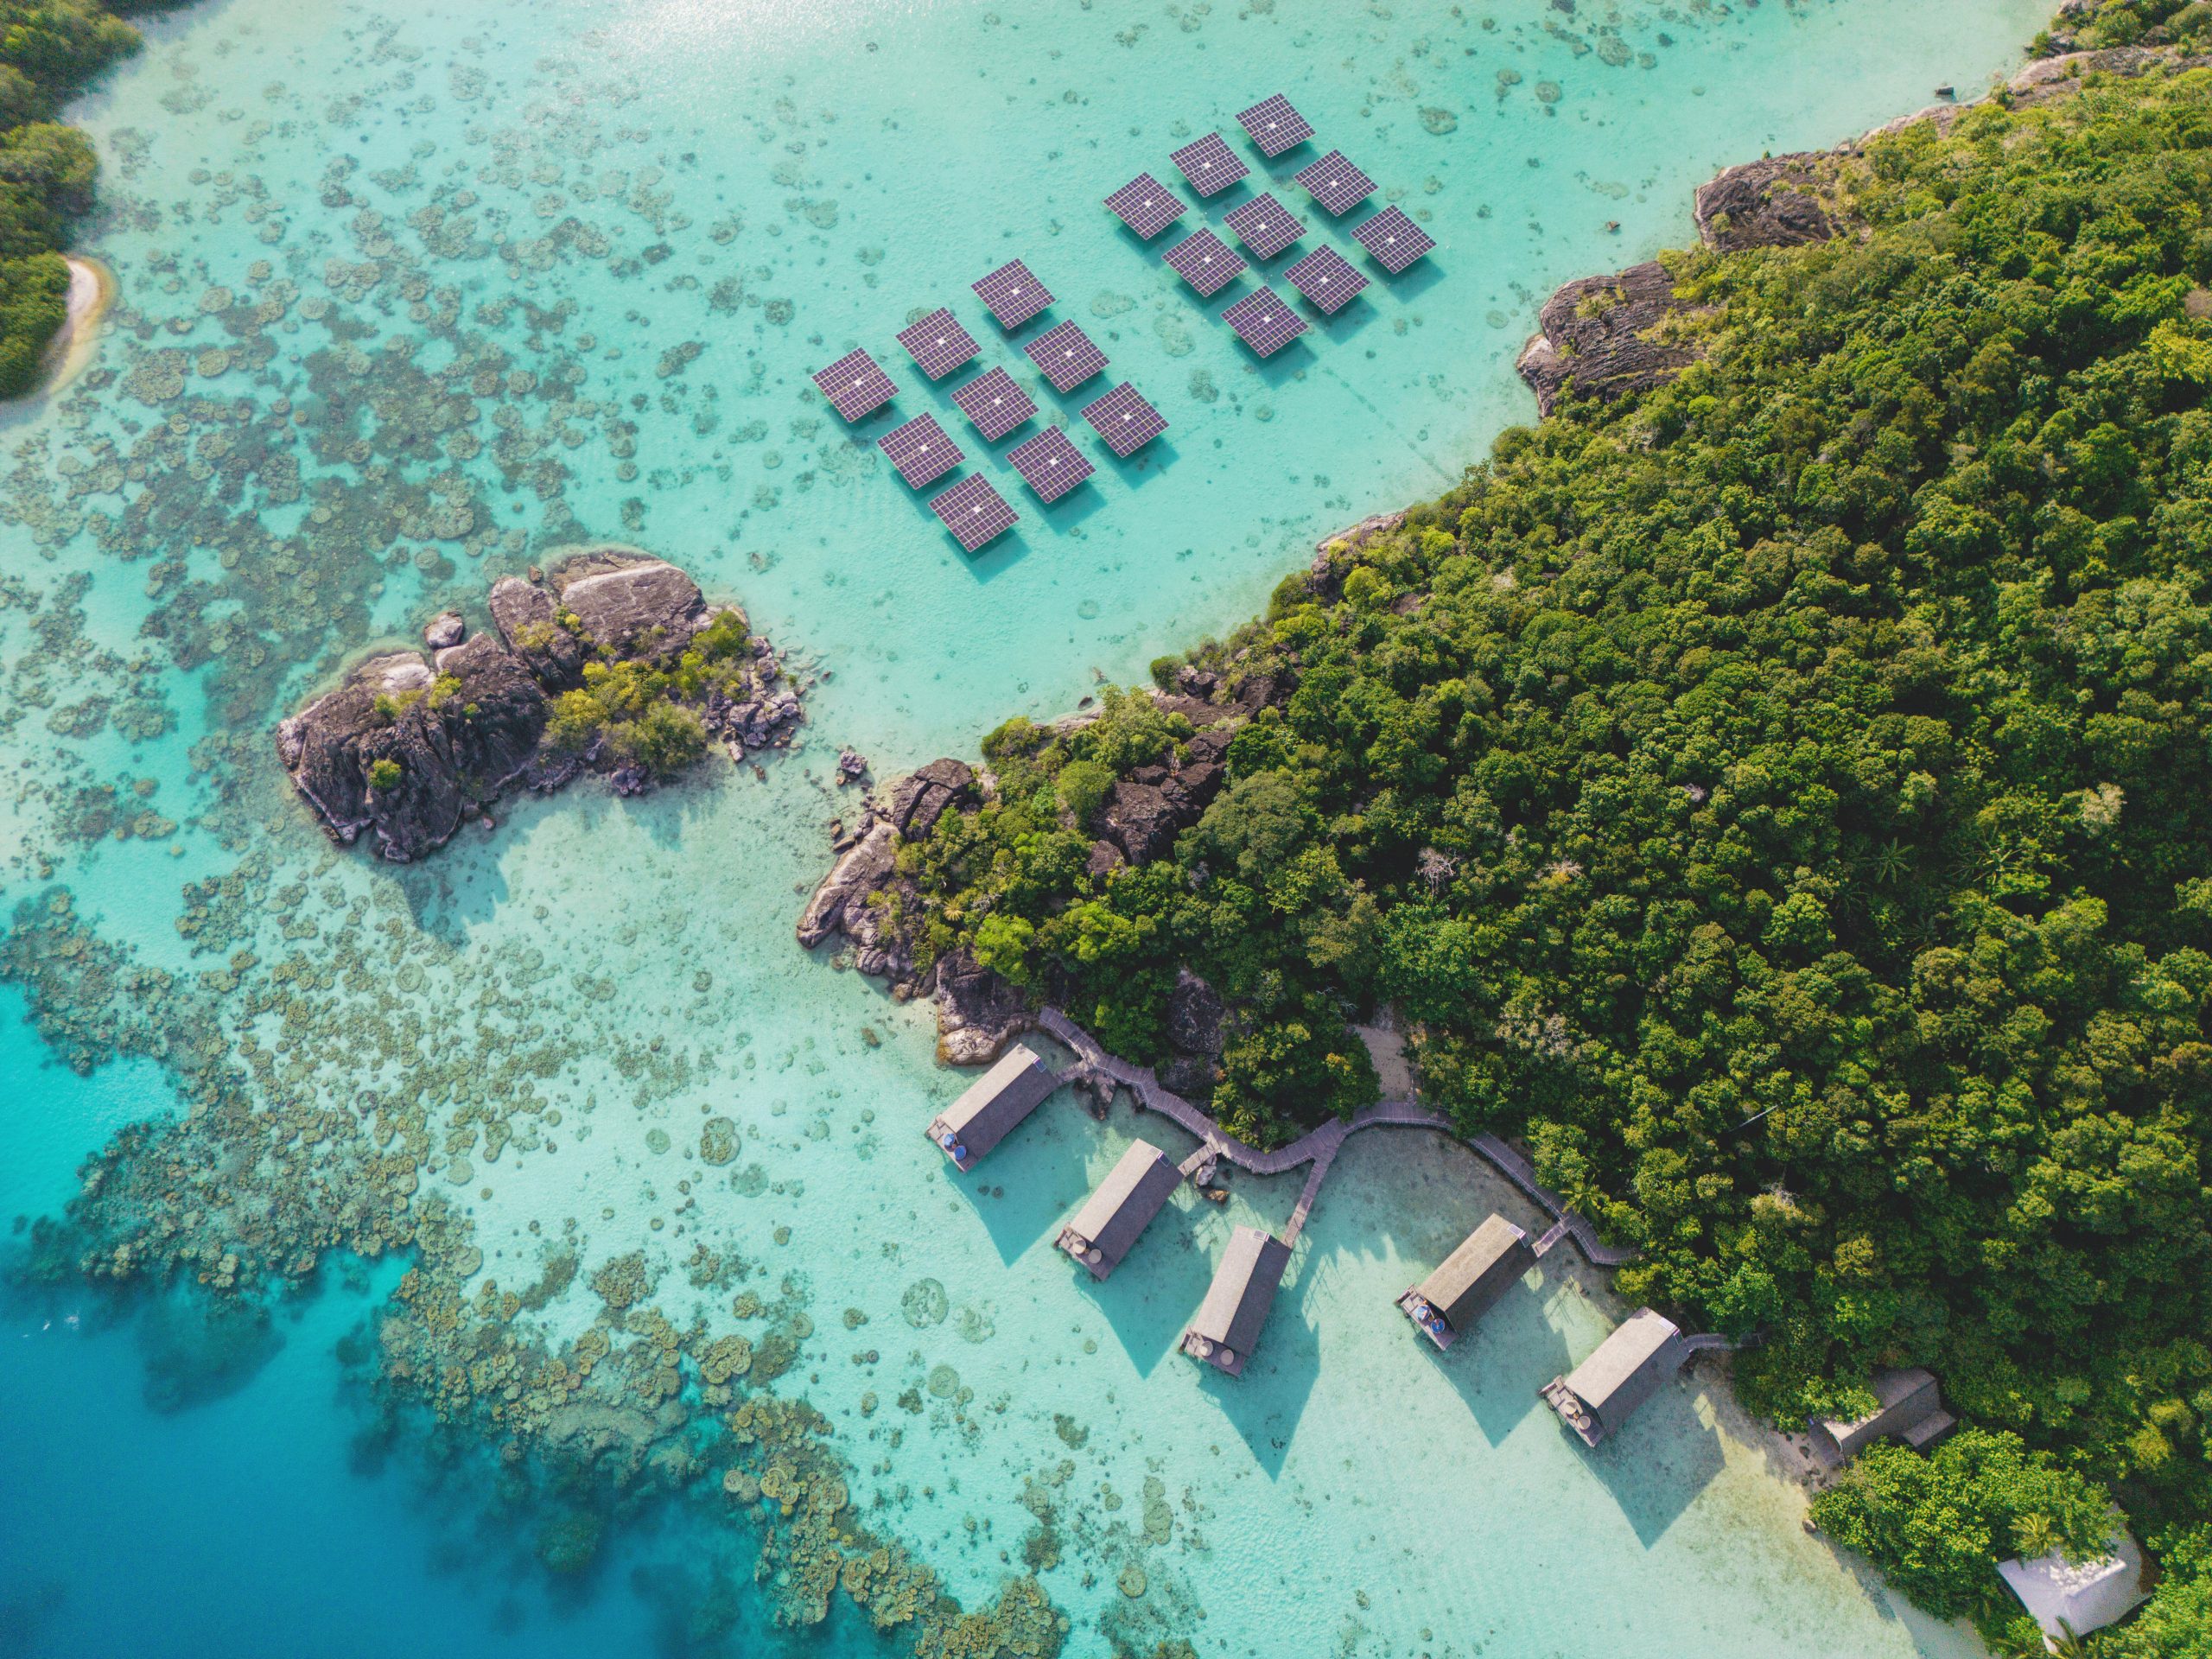
In the remote waters of Indonesia’s Anambas Islands, Bawah Reserve is redefining what it means to blend barefoot luxury with environmental stewardship.