One Country’s Dream of EV-Driven Prosperity Helps Fuel a Coal Binge Instead
Indonesia pitches its plan to leverage natural resources as a model for other developing nations

 4 min
A few years ago, Indonesia set out to turn its treasure trove of nickel into an electric-car manufacturing boom.
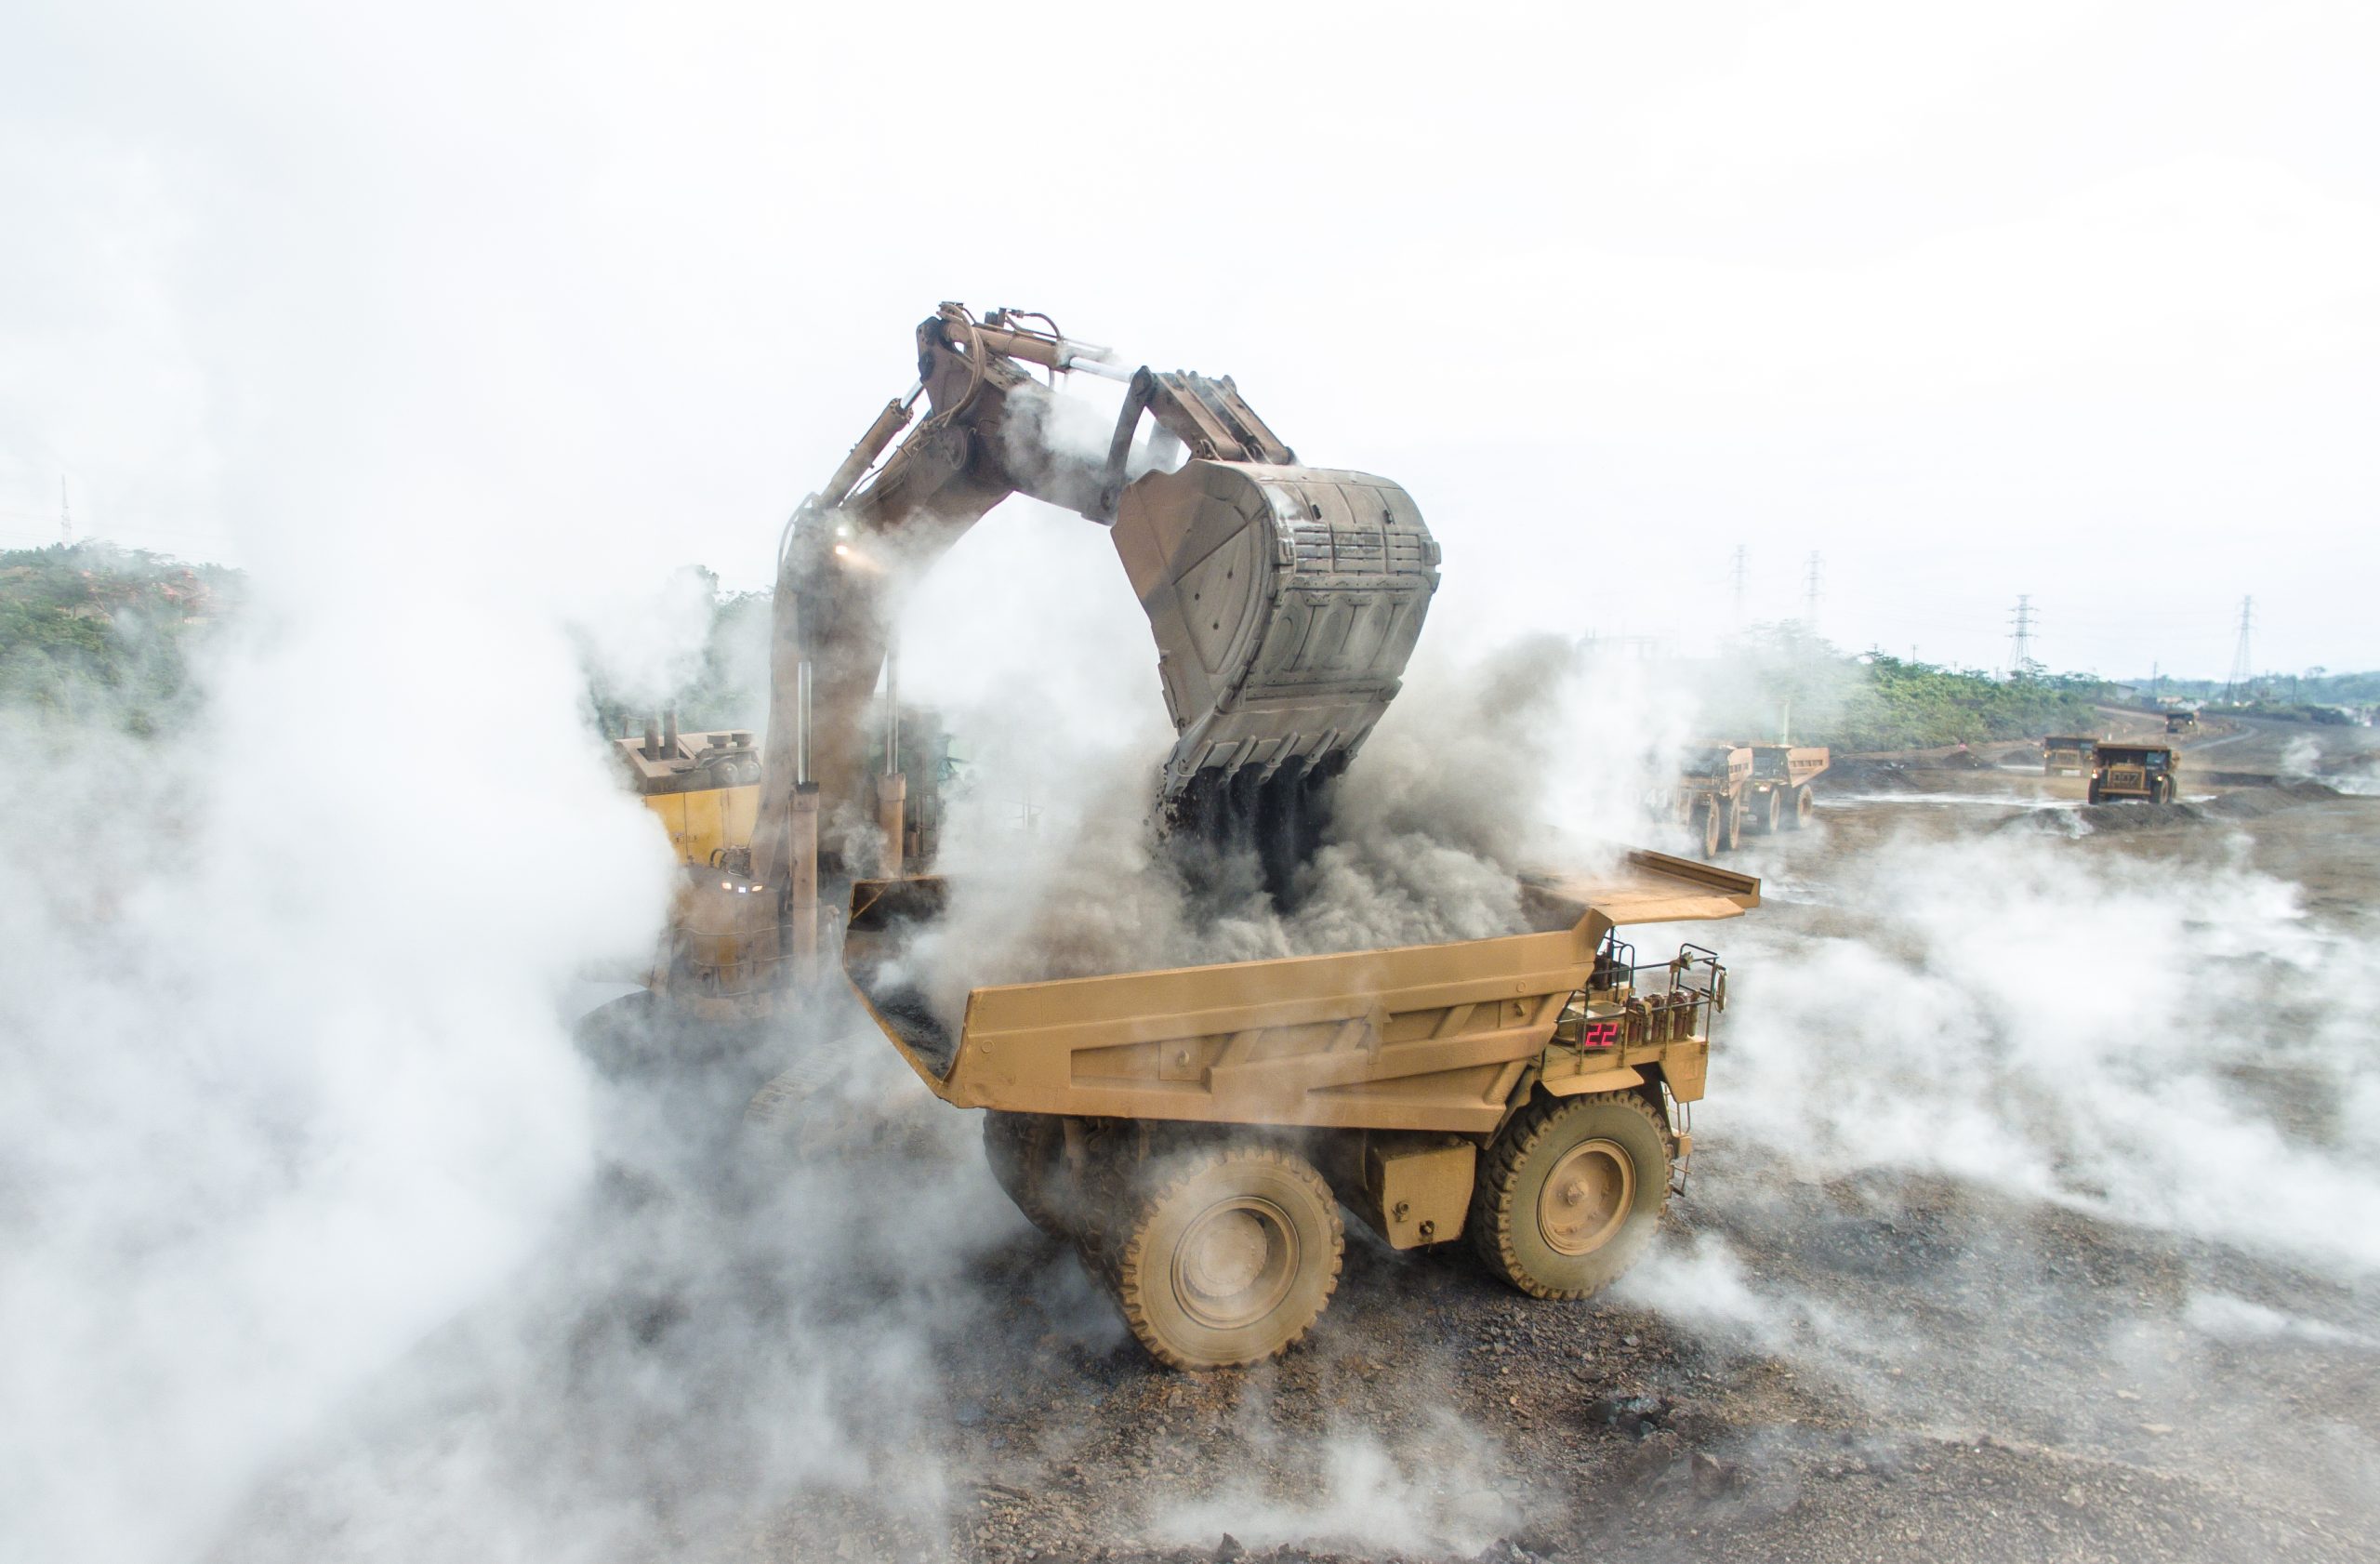
It imposed a sweeping ban on the export of raw nickel. That meant that companies wanting to tap the world’s largest source of the mineral—used in the most powerful type of EV batteries—would have to build smelters in Indonesia. Officials bet that factories to make EV batteries and entire electric cars would also follow, spawning end-to-end supply chains close to the mineral bounty.
The smelters came, and Indonesia’s nickel industry witnessed explosive growth. But powering it is a coal binge that is throwing off the country’s climate goals. And Indonesians are still waiting for EV makers to lay down production lines.
As President Joko Widodo prepares to leave office this year after a decade—the most he can serve—he is exhorting his potential successors to stick with the policy that is at the centre of his economic legacy. Indonesia holds presidential elections on Feb. 14, and a new leader will take charge in October.
Widodo has cast his plan, referred to in economist-speak as downstreaming, as the answer to the question of how Indonesia will become a rich nation. He says the country is reversing a 400-year pattern dating back to colonial times of being exploited for its natural resources and getting little in return. He has prodded other developing nations to follow its lead.
Last year, officials escorted delegations from mineral-rich Papua New Guinea and the Democratic Republic of Congo to one of Indonesia’s largest nickel industrial parks to show them the scale of Indonesia’s achievements. New Chinese-built smelters dot the archipelago. The value of Indonesia’s nickel exports is up four times since 2019 to around $33 billion.
Not everyone believes the silver metal is a silver bullet.
Nickel smelters have led to a surge in coal use, with new coal plants coming up at a time when the world is trying to phase out the fossil fuel. A January report by Climate Rights International, a U.S. environmental group, said that a single nickel-focused industrial park located on eastern Indonesia’s Maluku islands will burn more coal than Spain or Brazil when it is fully operational.
“We are sacrificing the environment and society, while at the same time getting limited profits for the country,” Muhaimin Iskandar, a vice-presidential candidate in the coming election, said during a televised debate with his political opponents.
Other candidates have pledged to carry forward the president’s nickel policies, including the front-runner for president, Prabowo Subianto, who has said it is much better to export electric-vehicle batteries than raw nickel.
The “dirty nickel” reputation is threatening the very economic opportunities Indonesia covets. In October, nine U.S. senators signed a letter opposing a proposed free-trade agreement to source critical minerals from Indonesia, citing environmental and safety concerns. Without a free-trade deal, EV batteries with substantial quantities of Indonesia-processed nickel won’t be eligible for a major U.S. tax credit.
That makes the country’s nickel less attractive to Western EV makers, who are already battling questions from green groups about the environmental fallout of the country’s sprawling nickel operations.
In a sign of the growing unease, a deputy director for batteries and critical materials at the U.S. Energy Department, Ashley Zumwalt-Forbes, voiced concern in a LinkedIn post last month about what she called the grip of dirty Indonesian nickel on the market. Indonesia accounts for half the global nickel supply, up from a quarter in 2018.
The problems with nickel are also pushing EV makers to rework car batteries and go nickel-free. A lithium-iron-phosphate alternative is gaining traction, though it remains less powerful than batteries containing nickel.
Then there is the question of whether the policy is taking Indonesia toward Widodo’s goal of downstreaming—that is, a shift to higher-value manufacturing. Widodo has long said the endgame isn’t localising nickel processing but rather attracting EV and battery factories. Anything less, he says, could put Indonesia on the same track as some commodity-rich Latin American economies that have languished.
But so far, EV makers haven’t rushed into Indonesia. Tesla, which Widodo has assiduously courted, including on a 2022 trip to Texas to meet with founder Elon Musk, hasn’t shown any signs it plans to set up a factory in the country. No other Western automakers have built EV factories either, though General Motors has a stake in one China-based automaker producing electric cars in Indonesia. Some, like Ford, have made deals to tie up nickel supply.
Korean automaker Hyundai has since 2021 operated one of Indonesia’s only EV factories, focused on the domestic market. The unit can produce 150,000 vehicles a year, but made fewer than 9,500 in 2022 and 2023. Hyundai and Korea’s LG expect to begin producing battery cells at a plant in West Java this year.
Automakers generally look to set up battery and EV plants in the markets where people are already buying electric cars. That puts Indonesia, where few consumers have switched from combustion-engine vehicles, at a disadvantage. The country has a limited charging network and gasoline is heavily subsidised.
Indonesian policymakers who believe the country’s nickel bounty gives it leverage over carmakers are mistaken, said Tom Lembong, a former trade minister under Widodo. He pointed to the growth of nickel-free batteries as a warning against betting big on nickel.
Lembong, who is advising presidential candidate Anies Baswedan—whose ticket advocates focusing on promoting labor-intensive industries—said Indonesia has made limited progress moving up the value chain.
“The irony about this is they call it downstreaming, but we’re still very upstream,” he said.
Septian Hario Seto, a senior Indonesian official involved in nickel policymaking, acknowledged that EV battery and car factories have been slower to come than nickel smelters. The government has brought new regulations to address that, he said, such as one that makes it easier for EV makers to import cars into Indonesia on the condition they later build a factory.
Last month, Chinese EV giant BYD said it would begin car sales in Indonesia, and break ground on a manufacturing unit later this year.
Overall, Seto said the nickel policy has been successful, boosting economic growth in less-developed eastern regions where the nickel is found, and providing jobs and tax revenue. The government has taken steps to limit environmental degradation, such as by banning companies from jettisoning mining waste into the ocean, and will try to bring hydropower projects online as an alternative to coal, he said.
Cullen Hendrix, a senior fellow at the Peterson Institute for International Economics in Washington, D.C., said there are two ways to assess Indonesia’s industrial policy.
“It’s been successful at driving foreign investment and building nickel processing capacity,” he said. “So far it hasn’t achieved the fully integrated mine-to-EV battery assembly to which it aspires.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
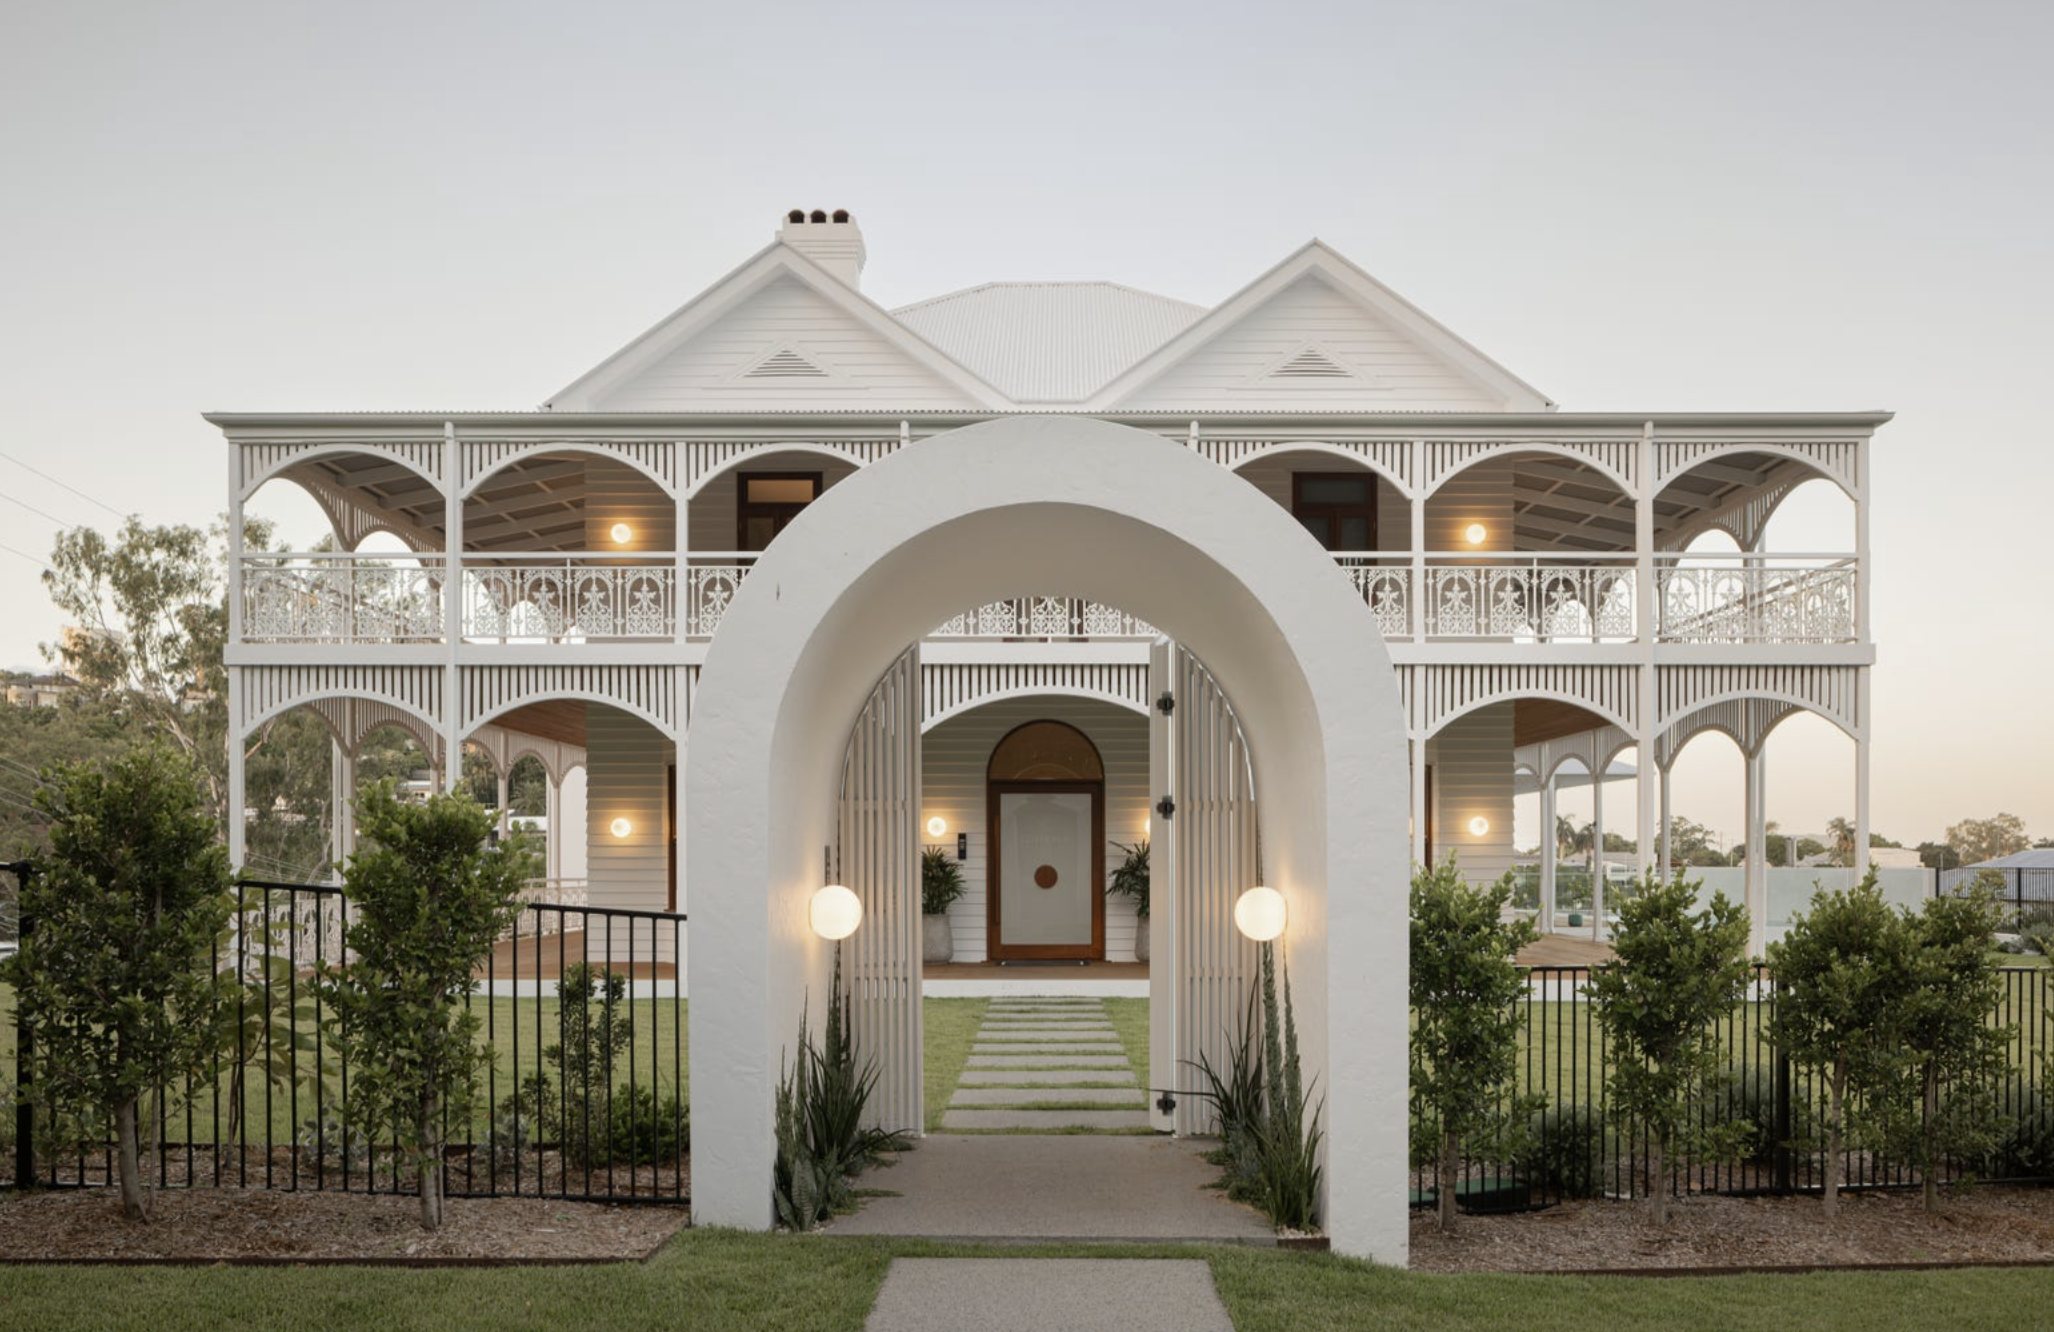
A restored 1860s Brisbane residence transformed by GRAYA has smashed Paddington’s house price record, selling for more than $12 million.

A&K Sanctuary unveils Kitirua Plains Lodge, a sustainability-focused luxury property shaped by landscape, local craft and contemporary safari architecture.